

“It was the best of times, it was the worst of times, it was the age of wisdom, it was the age of foolishness, it was the epoch of belief, it was the epoch of incredulity, it was the season of light, it was the season of darkness, it was the spring of hope, it was the winter of despair.”
— Charles Dickens, A Tale of Two Cities

As announced last week, this is our quarterly special edition of The Quotedian, where we review some of the decisions and most impactful charts of NPB’s investment outlook for the coming three months (and beyond).
But just before we start, here’s a housekeeping matter from the previous Quotedian, where I asked you whether the two editions (weekly and daily) should be merged into one. Here is how you have voted:
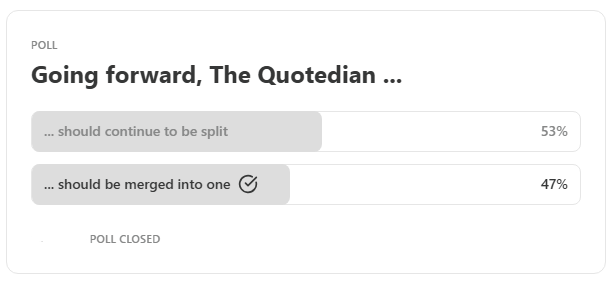
A close outcome, but given this is a true democracy: You have spoken!
Ok, with that out of the way, to some of the key elements of our outlook. And please forgive me for heavily copy/pasting from our outlook document, but after an intense 10-day of preparing, meeting & deliberating and then putting the material into presentable form, both, my fingertips and grey brain cells are in need of a break…
But I need to admit something first …
Back in April of 2020, during the first weeks of the COVID-related lockdown, I wrote a piece for my then stakeholders titled “A Tale of Two Cities” and started with “ It was the best of times, it was the worst of times …” you know the rest.
At the time, the human aspect of the pandemic was definitely close to the “worst of time”, whilst financial markets quickly recovered and then same in the “best of times”.
Today, as I am recycling this title, it feels a bit the opposite, where we are coming from some of the “best of times”, potentially moving into the “worst of times” (tbc of course).
Here’s the slide of our Executive Summary out of the deck:
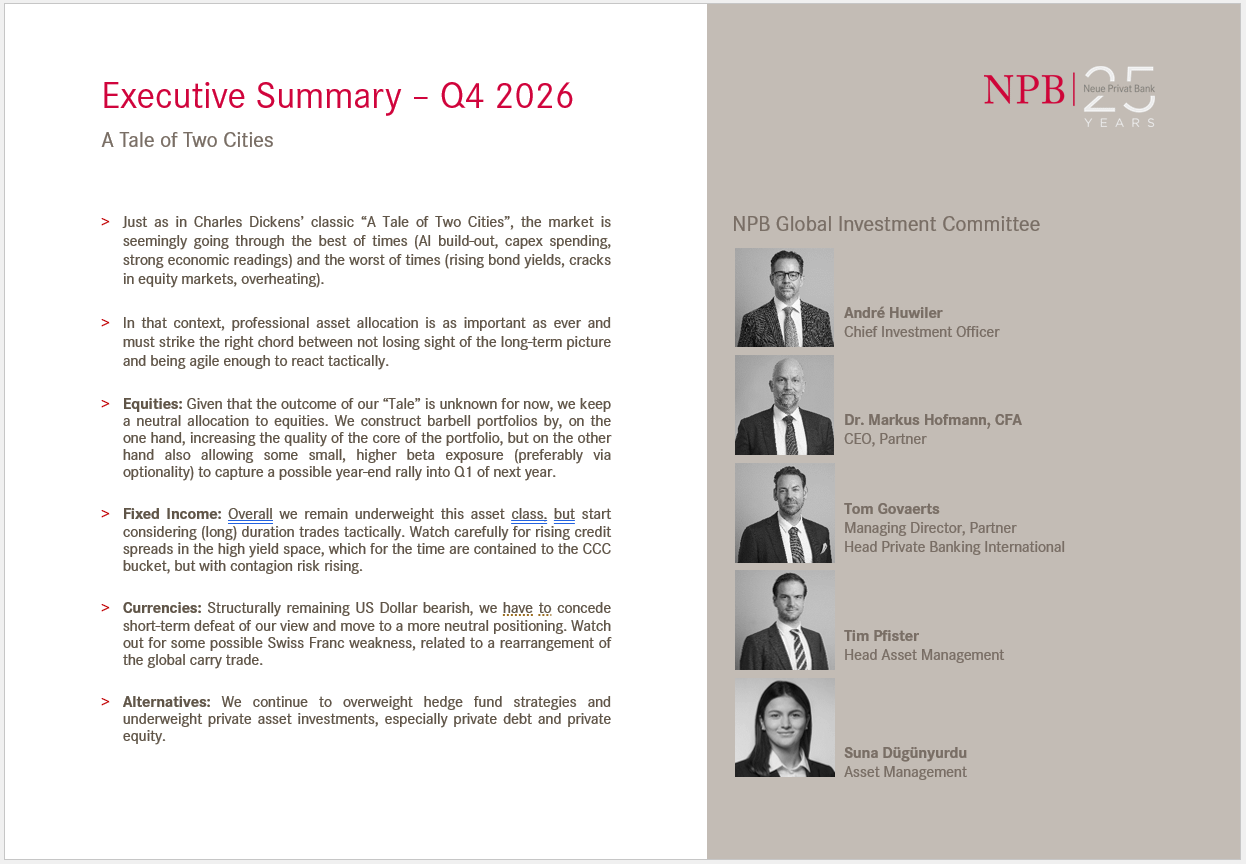
Both decks, the Global Asset Allocation and the accompanying chartbook should be available soon on our home page (www.npb-bank.ch), but for those of you who cannot wait, feel free to ping me at ahuwiler@npb-bank.ch to receive either or both documents.
To follow some key slides out of the chartpack.
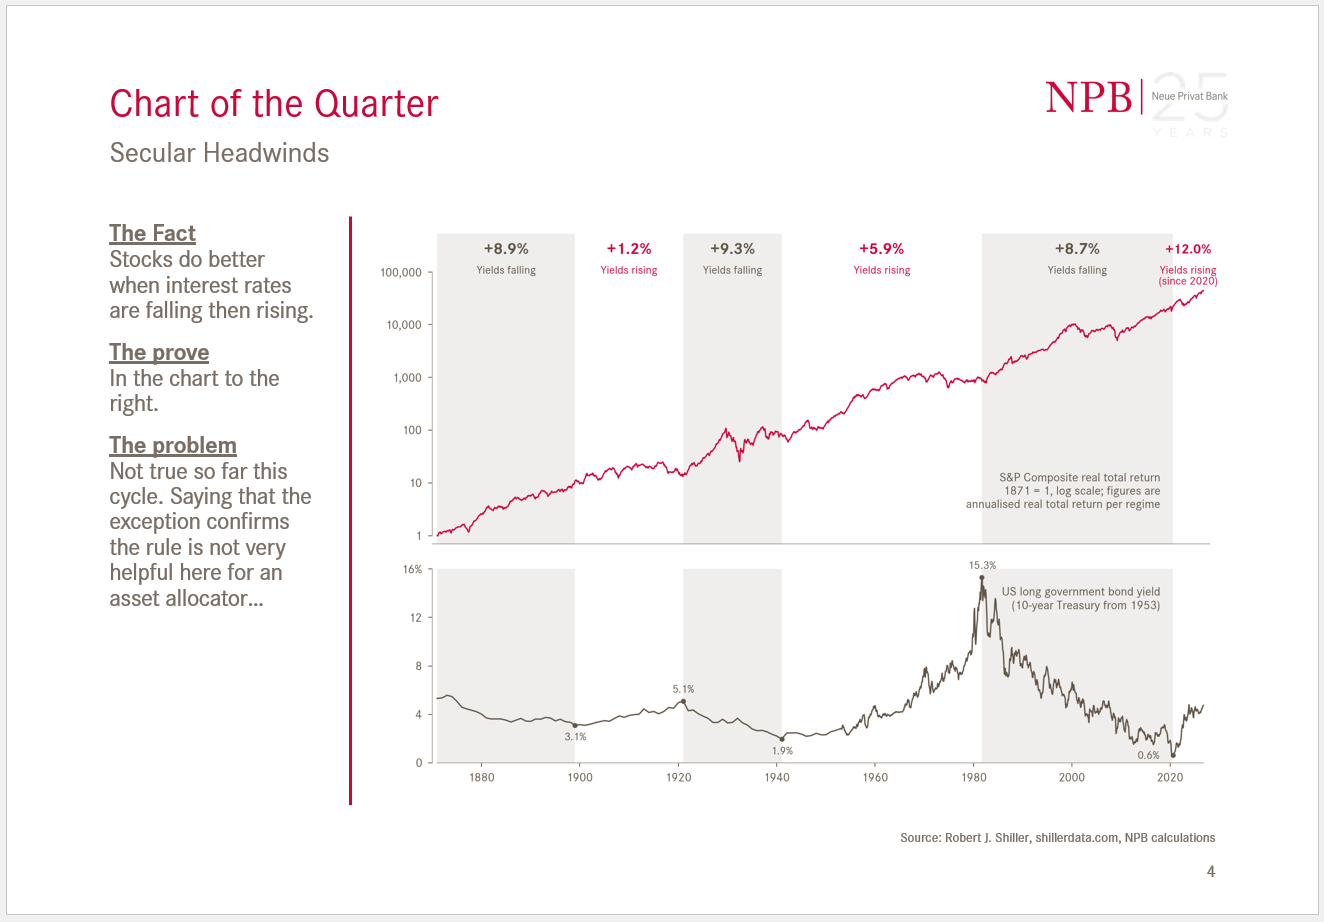
Our “Chart of the Quarter” is a true stunner:
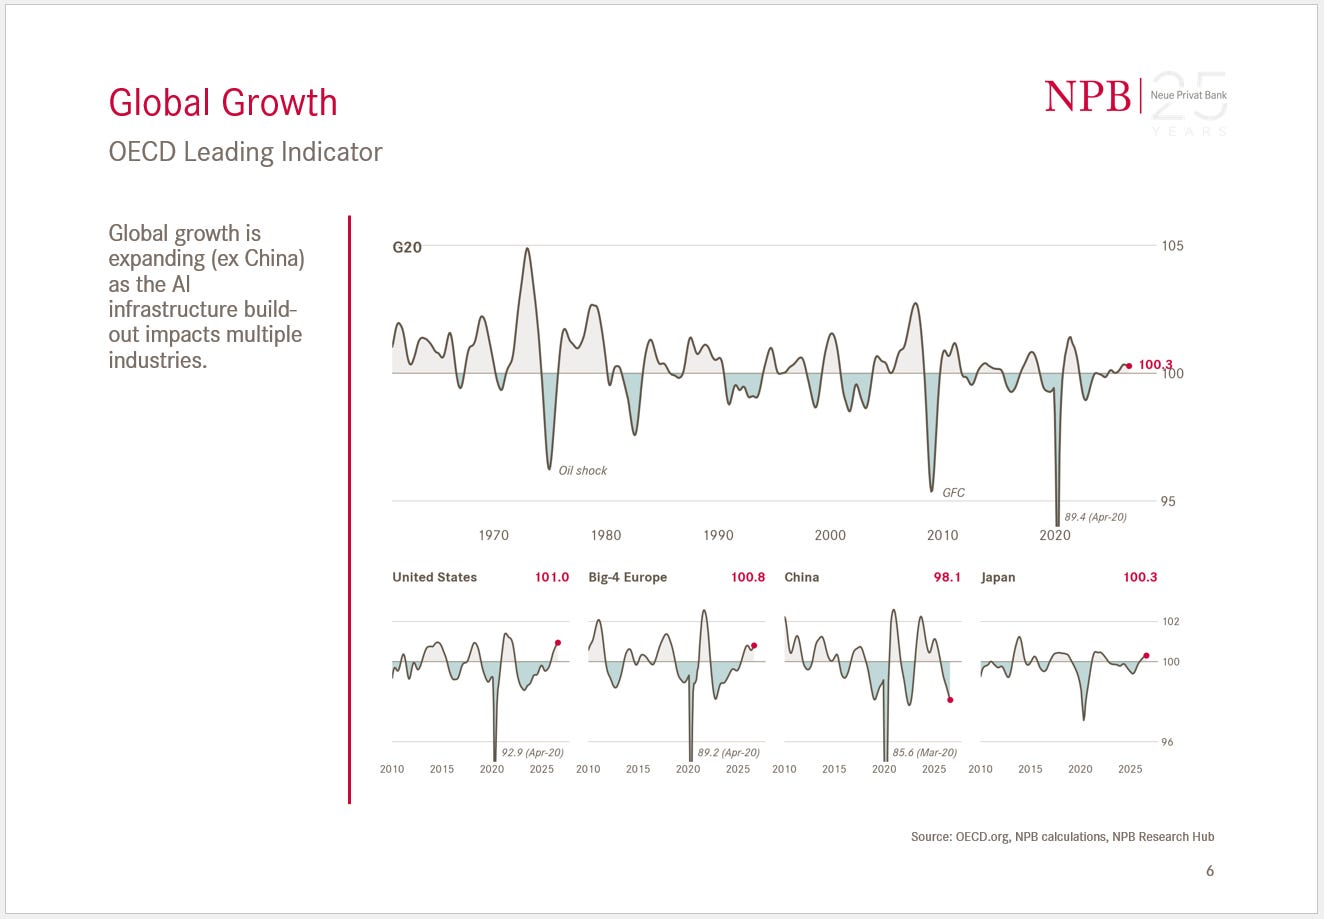
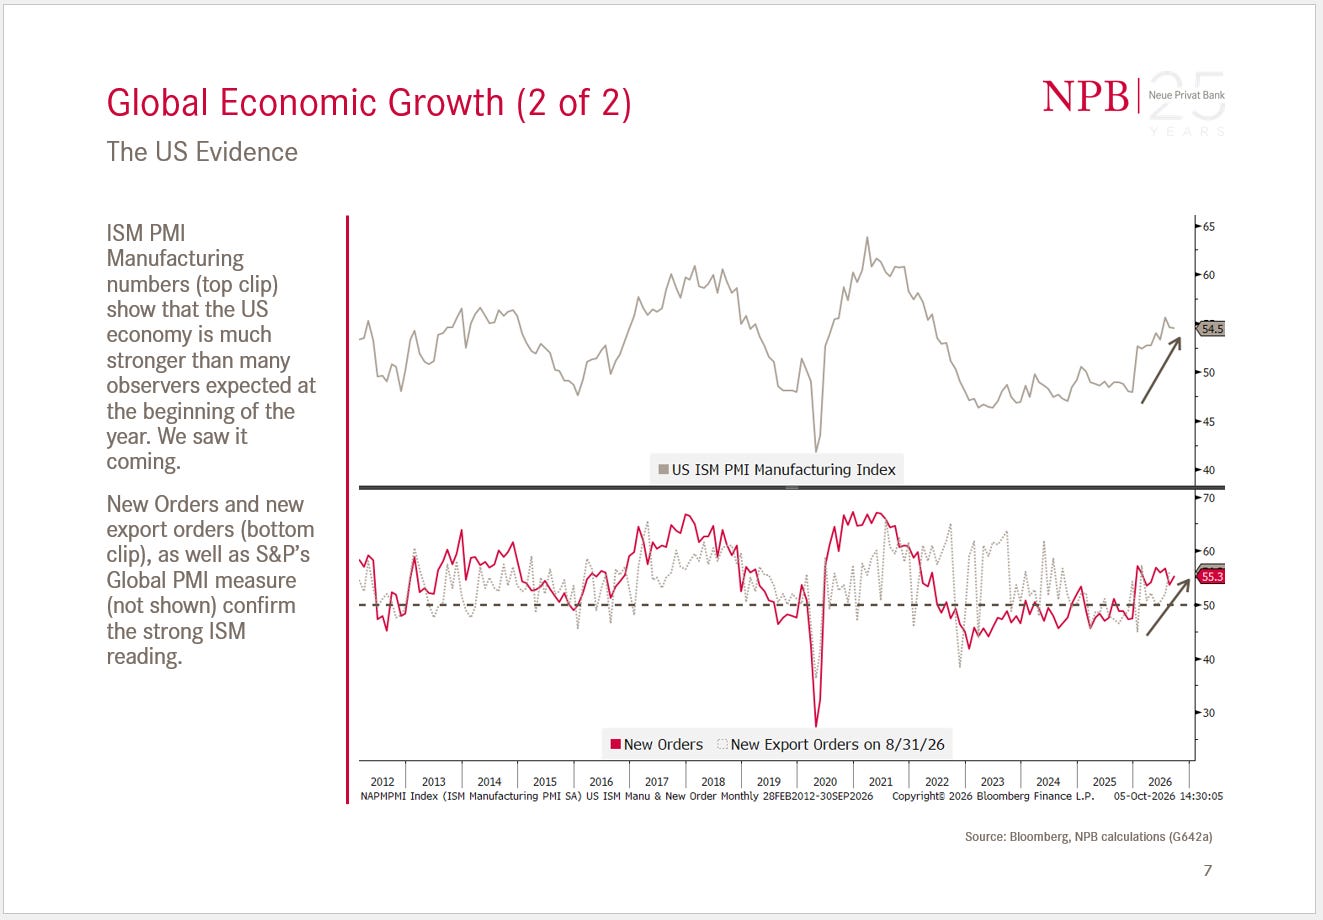
Overall, we argue that growth is good and probably even better than expected,
especially in the US
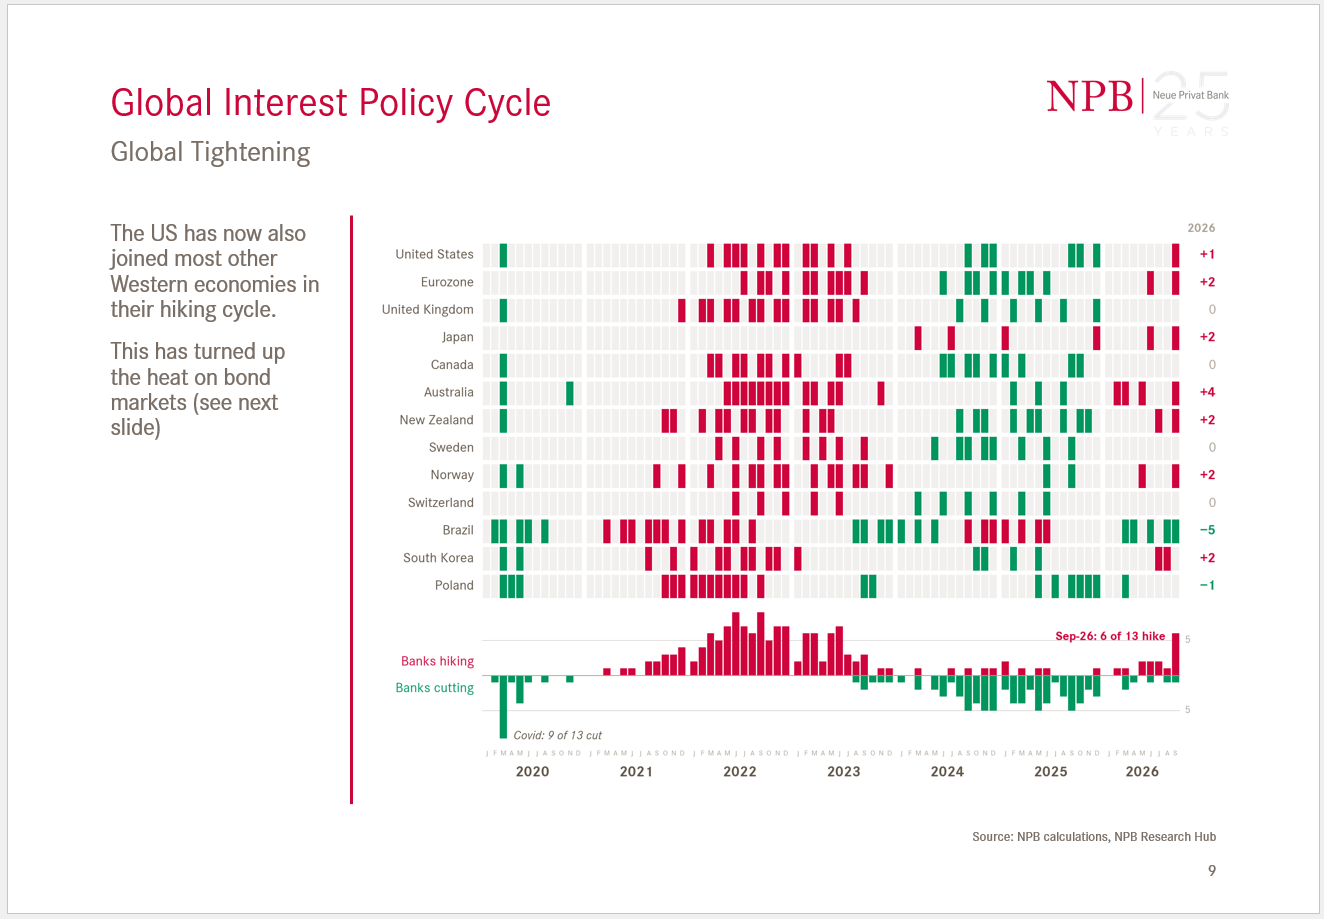
However, this economic strength may provoke further rate hikes from central banks around the globe,
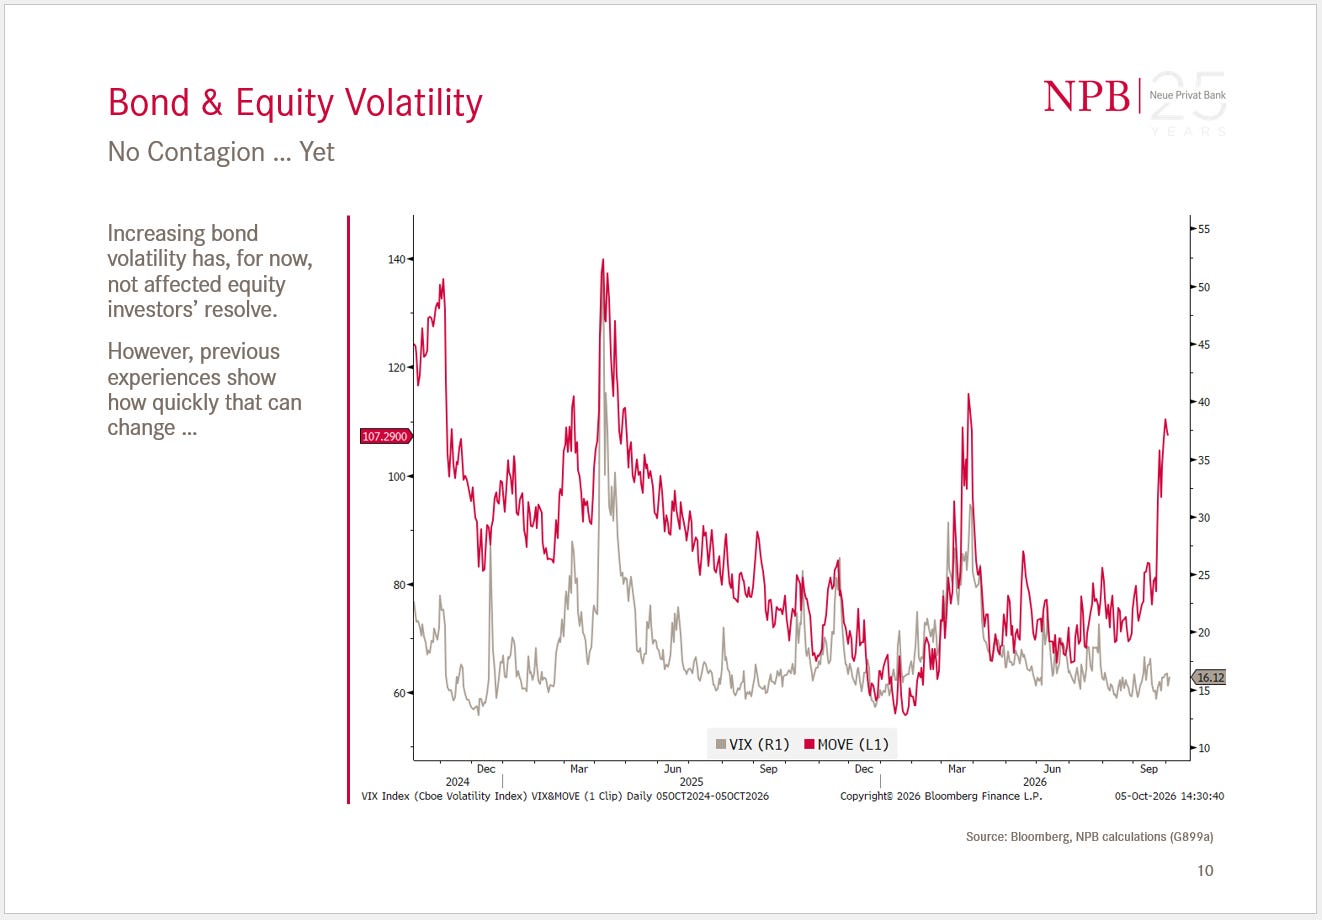
which in turn may lead to a tightening of financial conditions, which today are still pretty relaxed:
Underweighting bond duration has been one of our best calls this year, as global government bond yields have been shooting higher, with one notable exception…
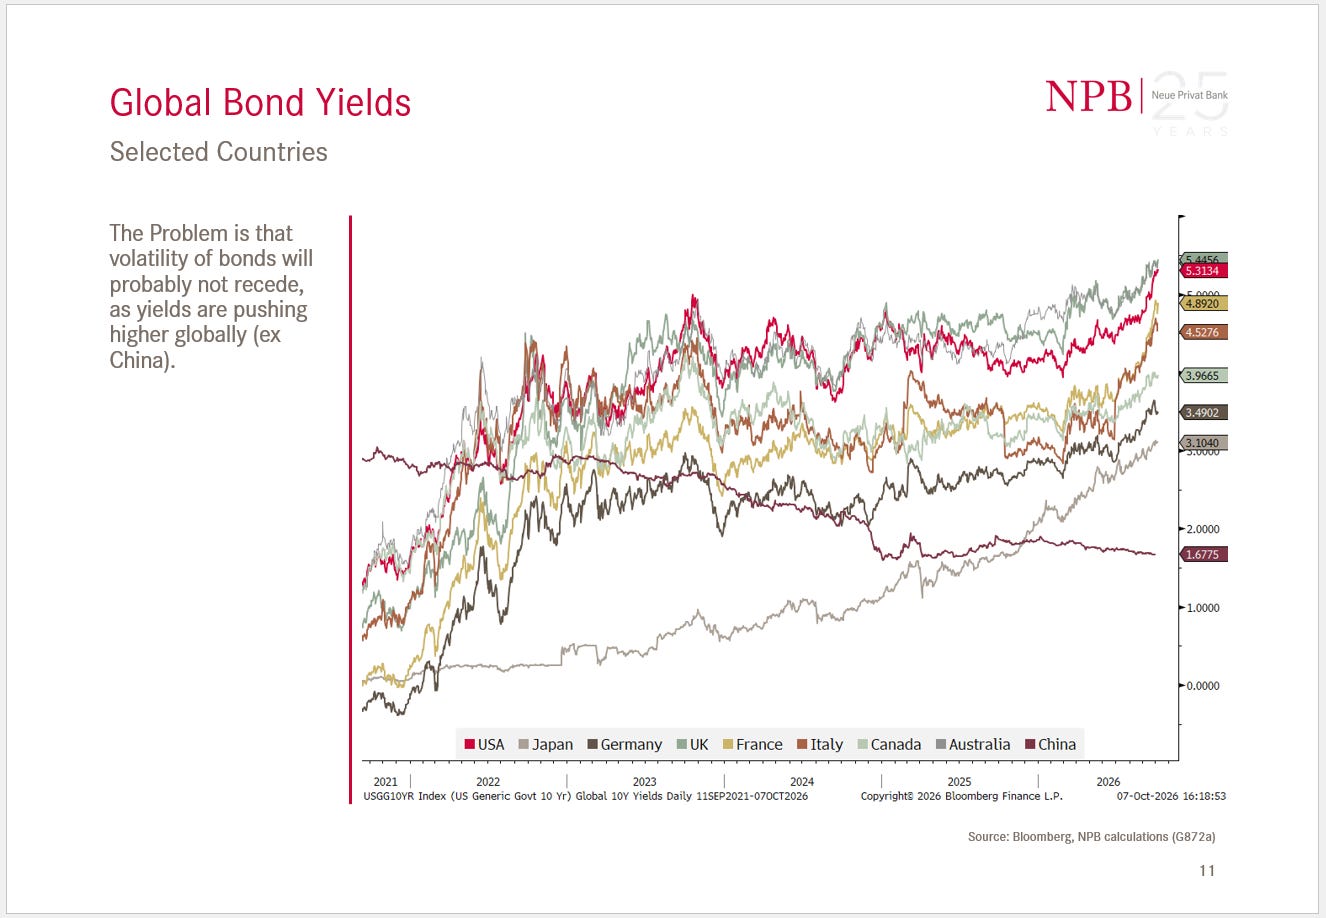
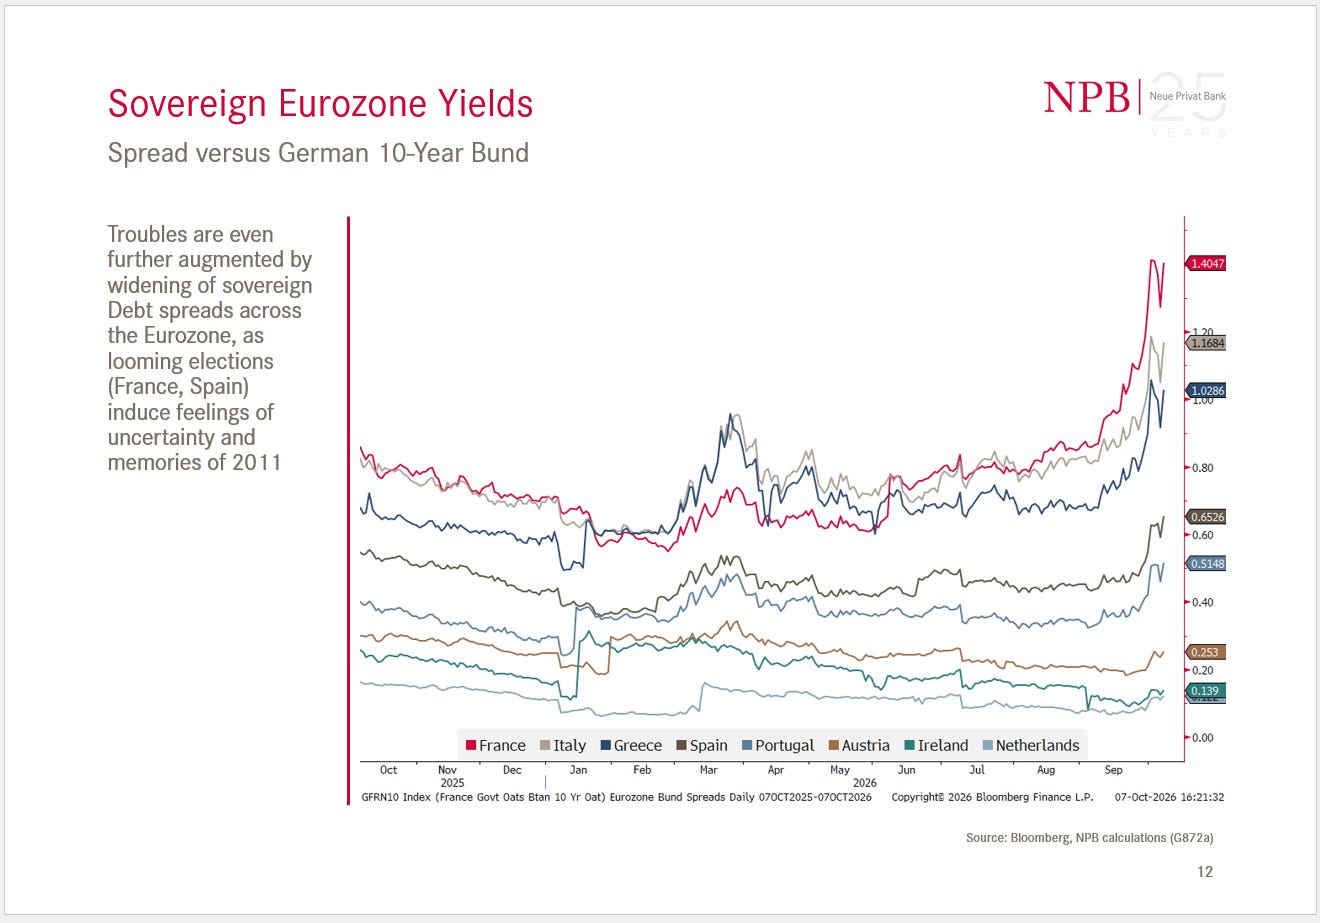
Whilst rising inflation expectations, but especially also the aforementioned better-than-expected economic growth numbers, are largely responsible for the rise in yields, the culprits in Europe are rather political, fiscal and social turmoil:
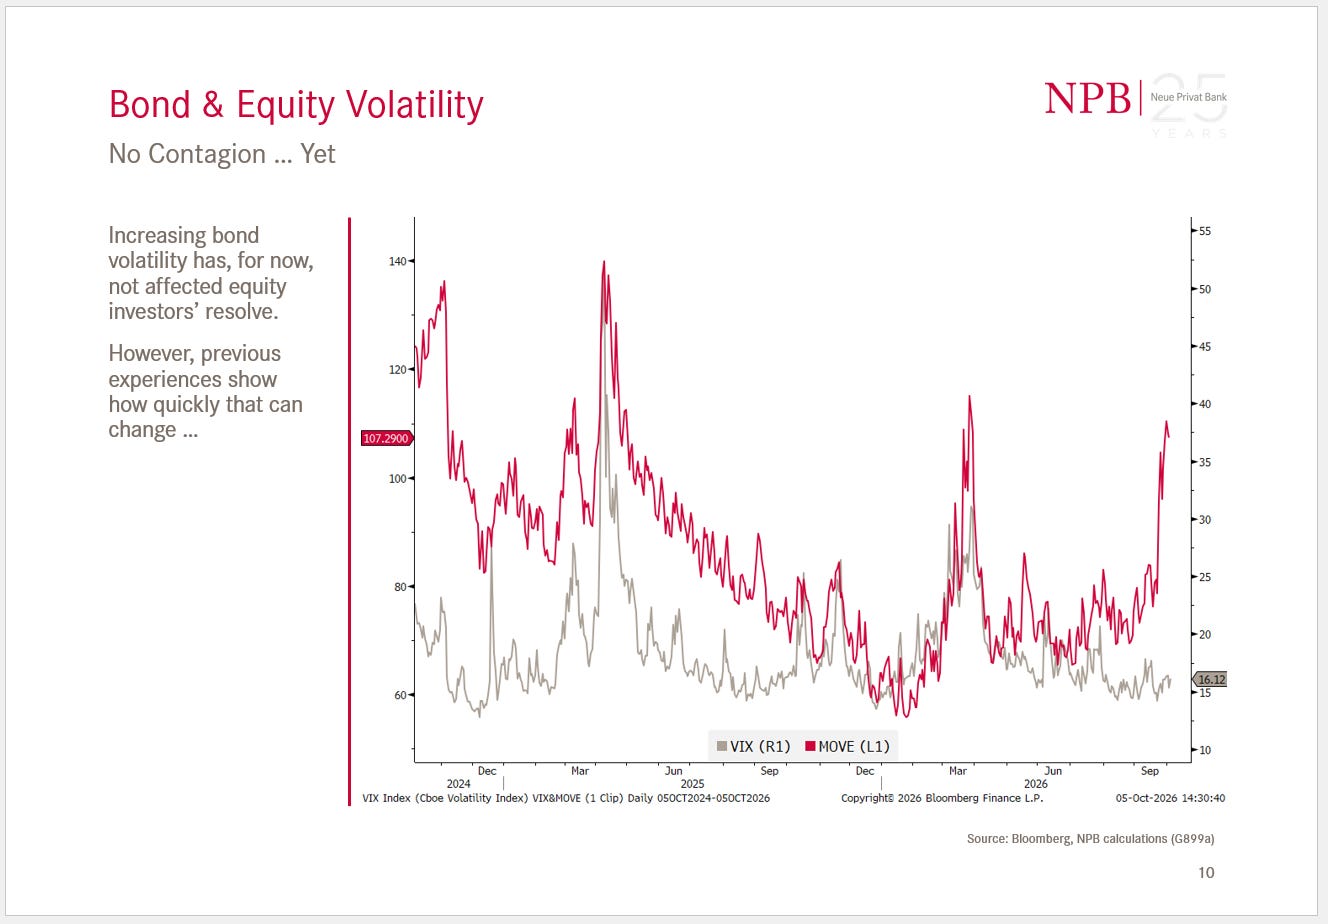
For now, the bond ‘panic’ has not swapped over into equity markets:
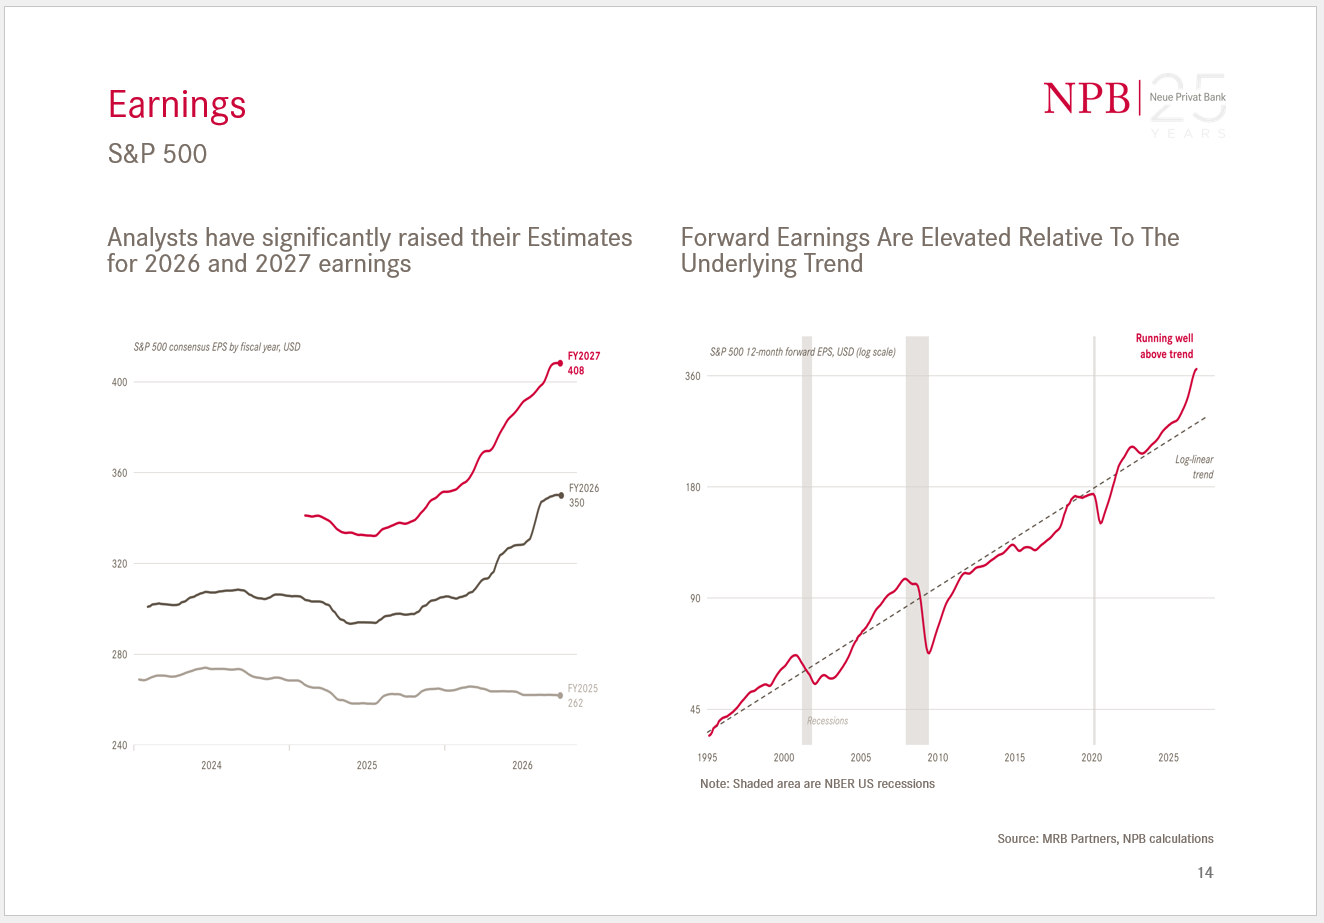
Earnings have been supportive to the move higher in stock markets, however, the seem to be at the upper end of the typical cycle:
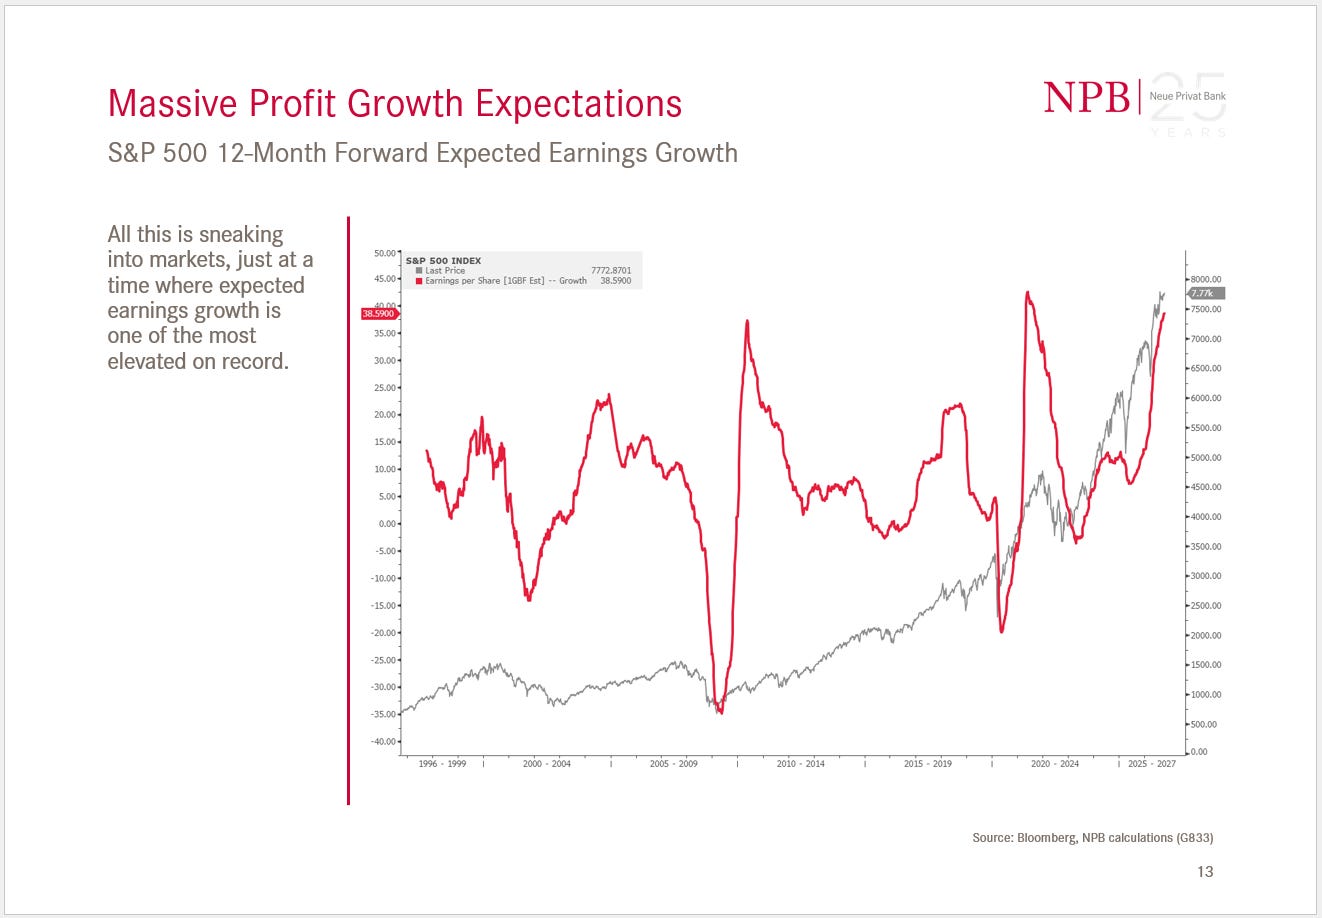
Expectations may need to cool down:
Will the passive avalanche ever end?
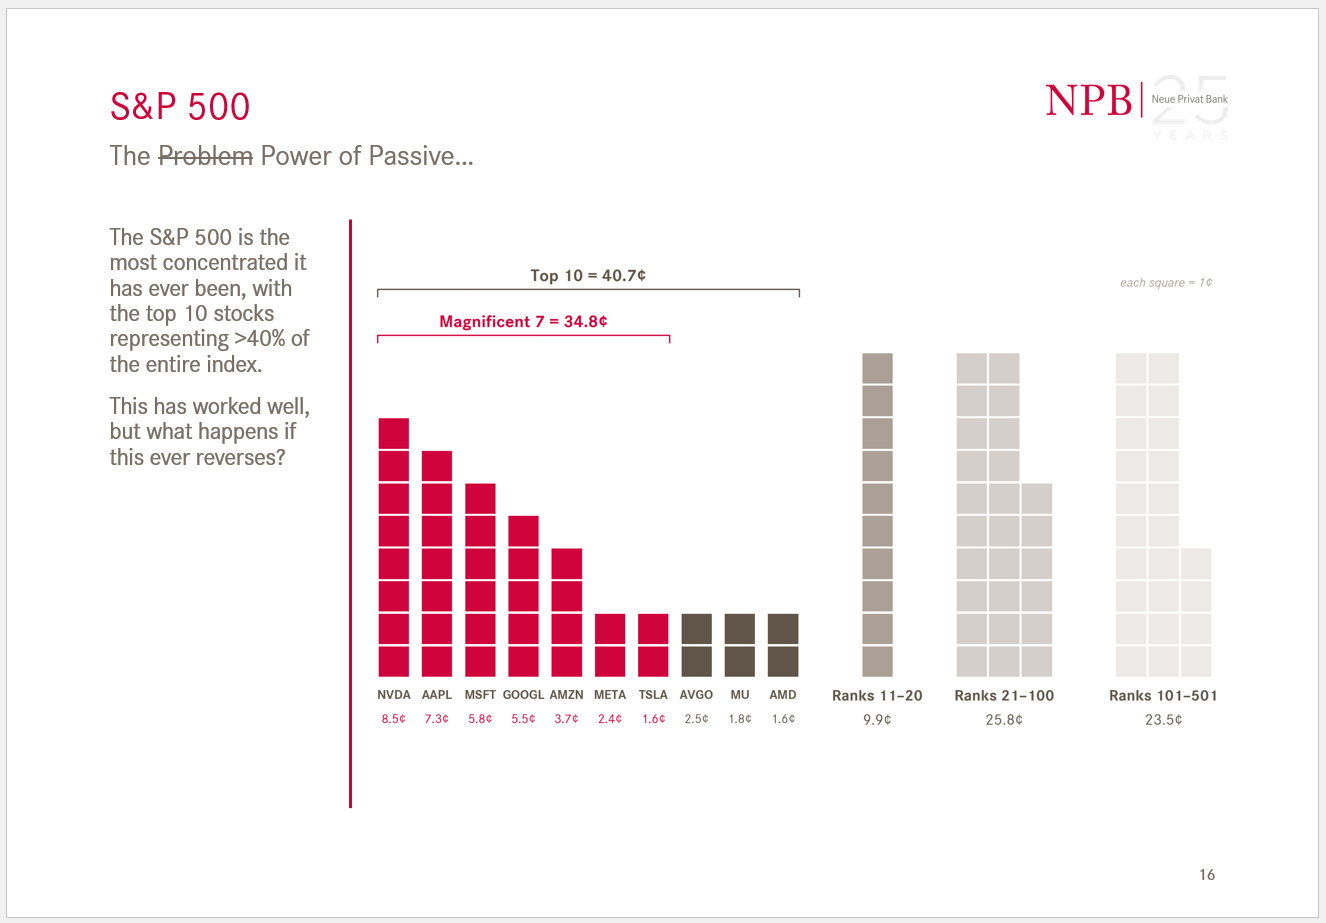
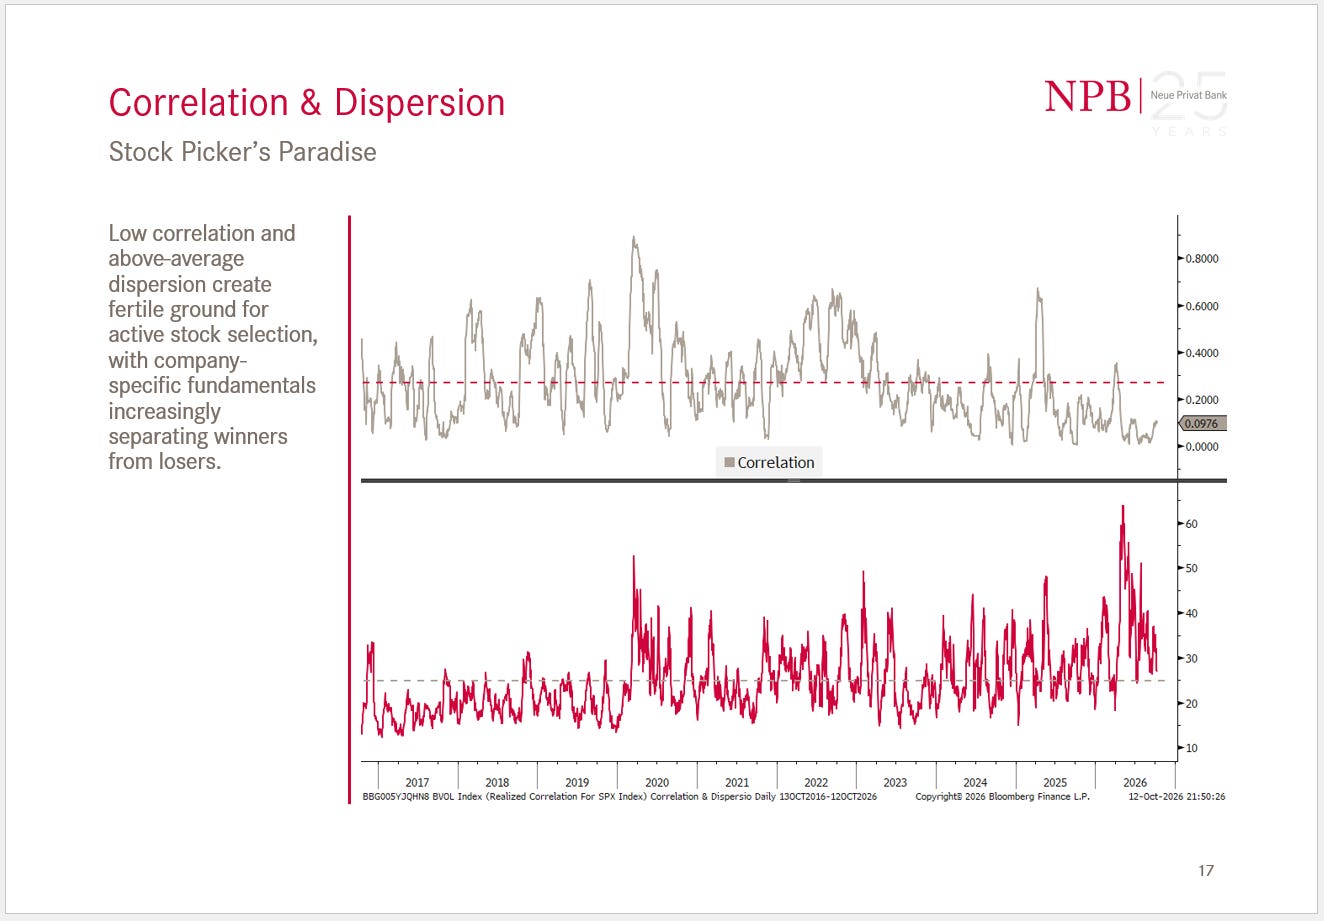
As natural born optimists, we see opportunities arising out of the obsession for passive in the market:
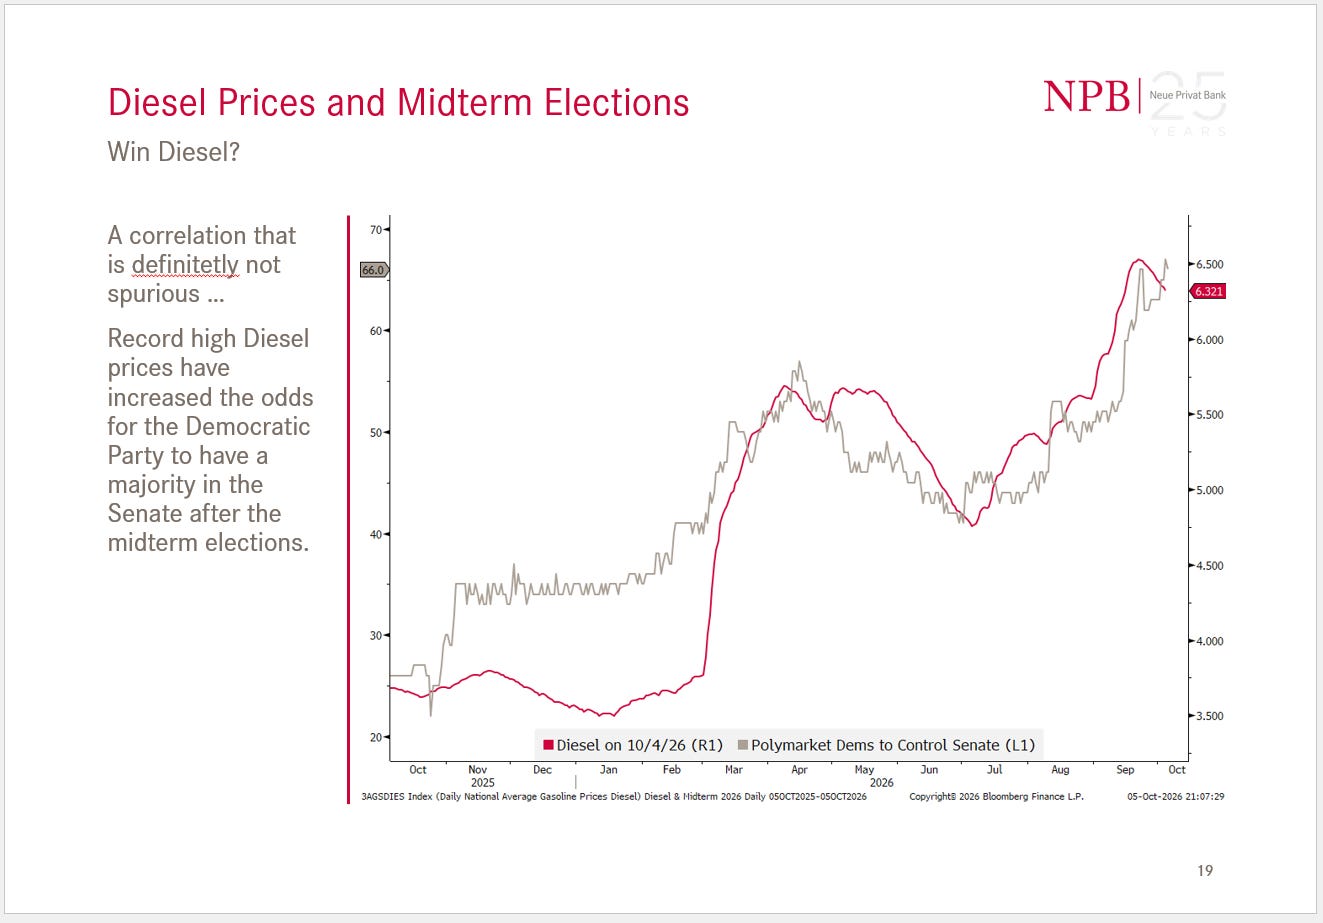
And finally, this chart explains why Trump let his pants down (sorry, this is the technical and above all correct term) last weekend, when agreeing on Diesel imports from Russia with Russia:
These are only about a dozen charts out of our 170-pages chartbook - again, feel free to ask for your company by dropping me a friendly email:
And, of course, feel free to share The Quotedian with friends and family:
That’s all for today - May the Trend be with You!
André

The Important One:
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG
The Legal One: