

“When the capital development of a country becomes a by-product of the activities of a casino, the job is likely to be ill-done.”
— John Maynard Keynes
IMPORTANT NOTE:
Due to the visit of an intense flu, I have not been able to do the usual work on this week’s Quotedian. However, it would be a shame to just bin whatever I achieved to prepare over the weekend before falling sick. So, please accept my apologies for the briefness/incompleteness of this week’s letter - I hope there is still one or the other gem in there that nudges your interest.

Not a rant, but a critical observation:
It all started with MEME stocks during the pandemic, when furloughed workers metamorphosed into armchair speculators.
0DTE options followed.
Then leveraged ETFs.
Then prediction markets such as Kalshi and Polymarkets.
Rightfully, you would be inclined to ask where the regulator is in all this?
But not only is the SEC (Securities & Exchange Commission) in the US for example completely blindfolded to the gamification of financial markets, it actually is in full support of it!

Key Details of the Approval
What it is: Binary “yes/no” options contracts that pay out based on whether a publicly traded company beats or misses specific performance metrics (such as Tesla deliveries, Apple iPhone sales, or Alphabet YouTube ad revenue).
Initial Rollout: Covers 23 major U.S.-listed companies, with Robinhood acting as the primary retail brokerage platform.
Fees: Cboe will waive exchange fees through the end of 2026, and Robinhood plans to offer the contracts with no platform fees through year-end.
We all know how this will end.
But if you don’t know, I will resolve your doubts at the end (aka the bottom) of this week’s Quotedian.
But before that, let’s have a cross-asset look at financial markets after what has been an agitated week.
It was a difficult week for equities:
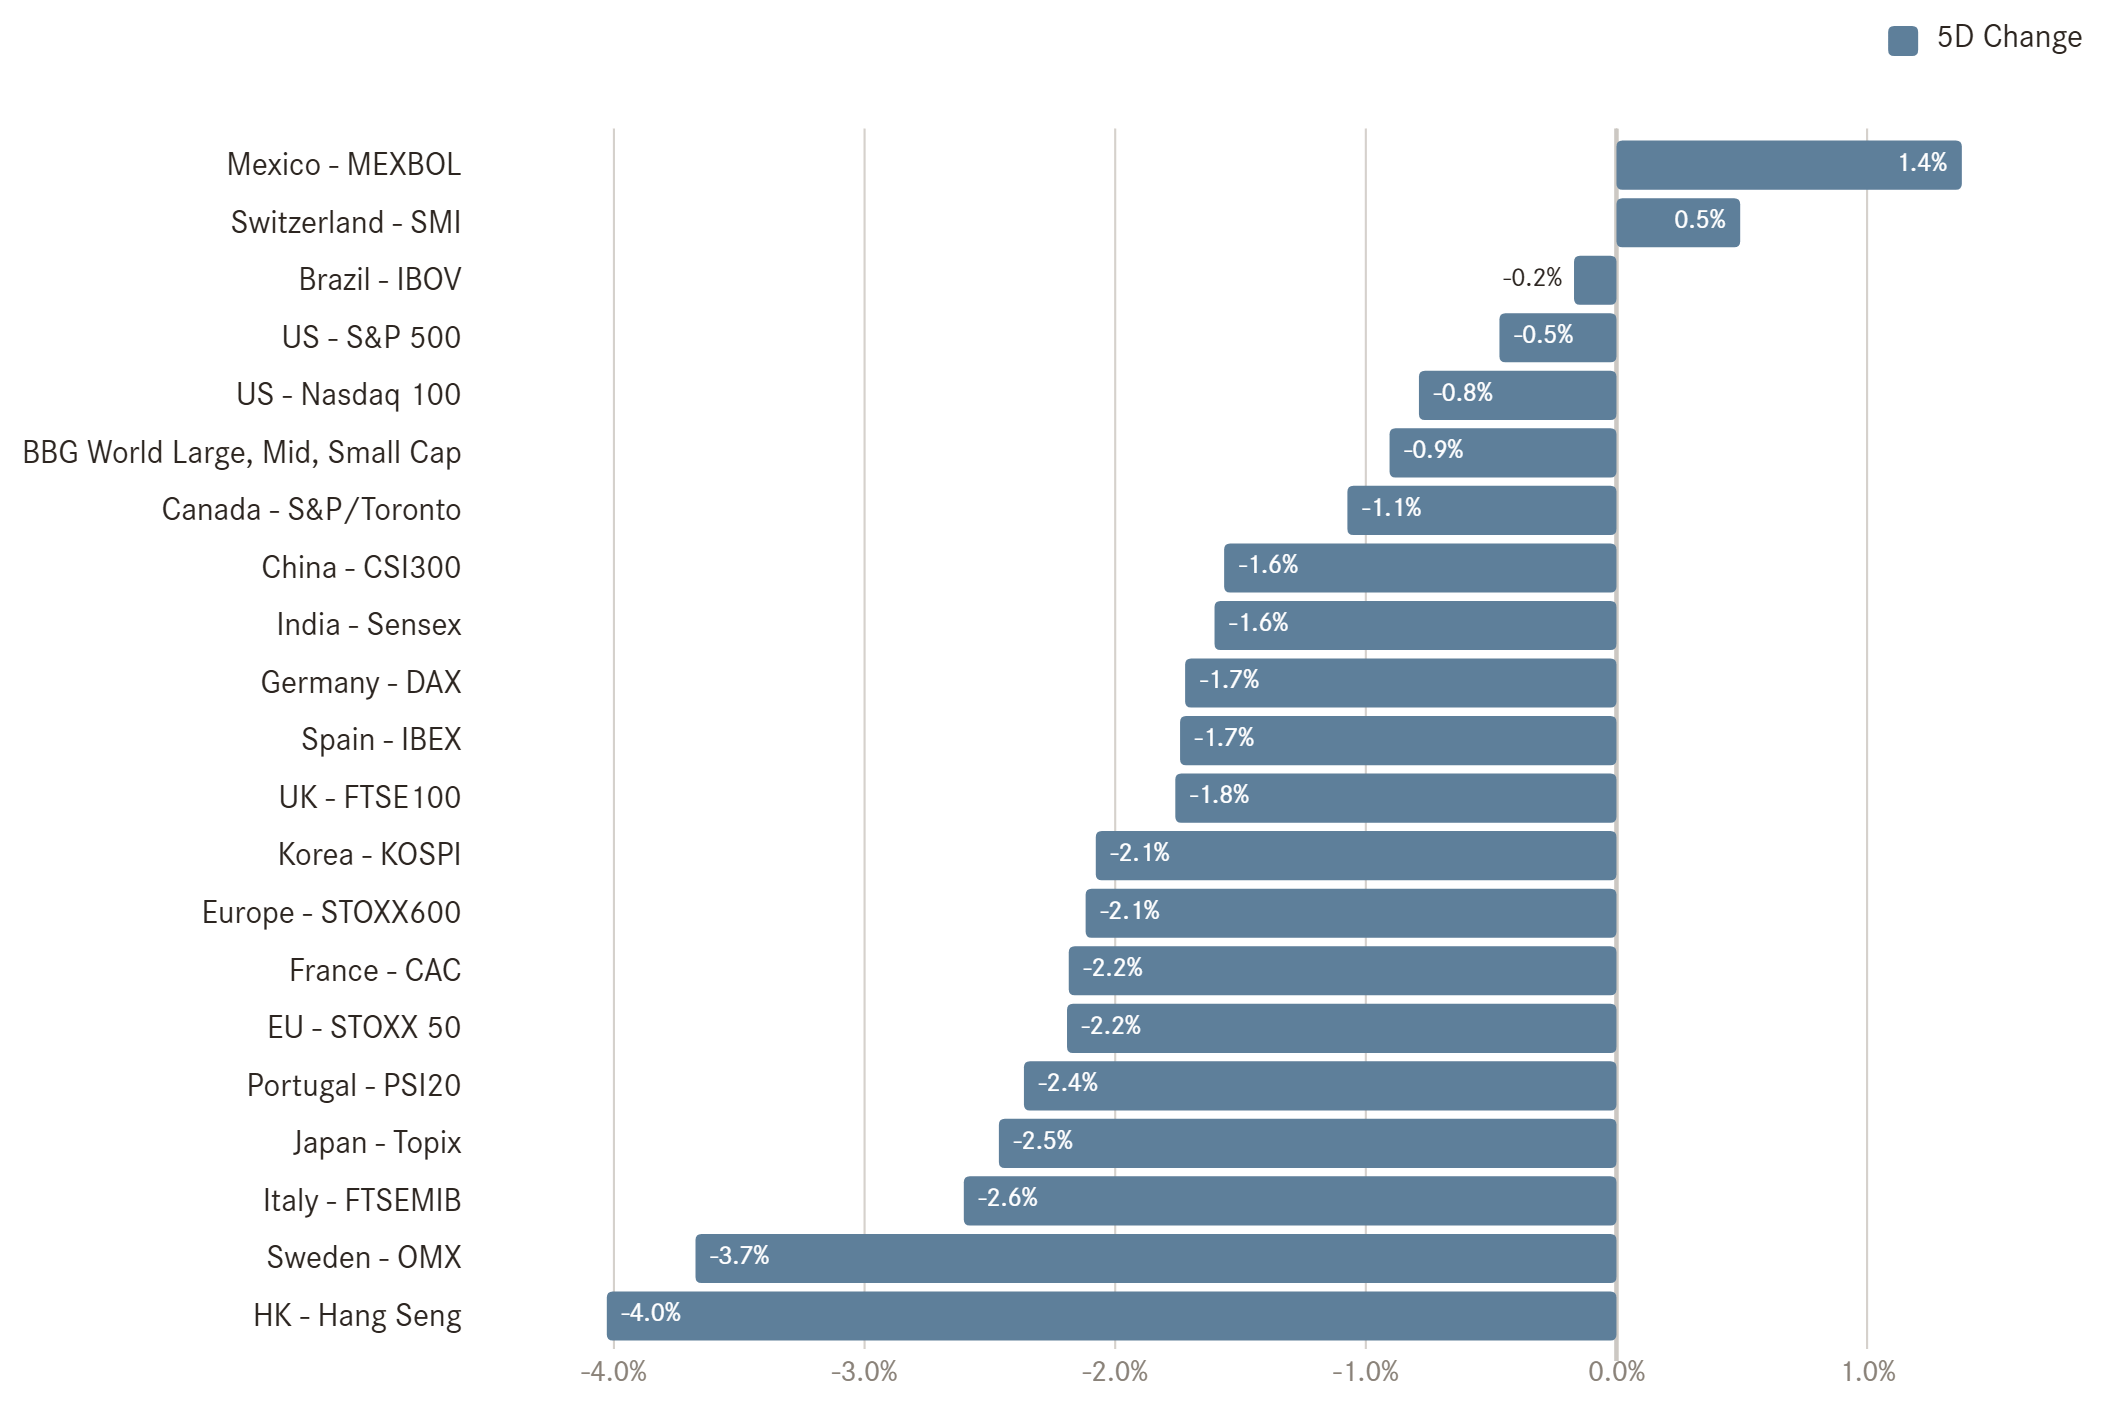
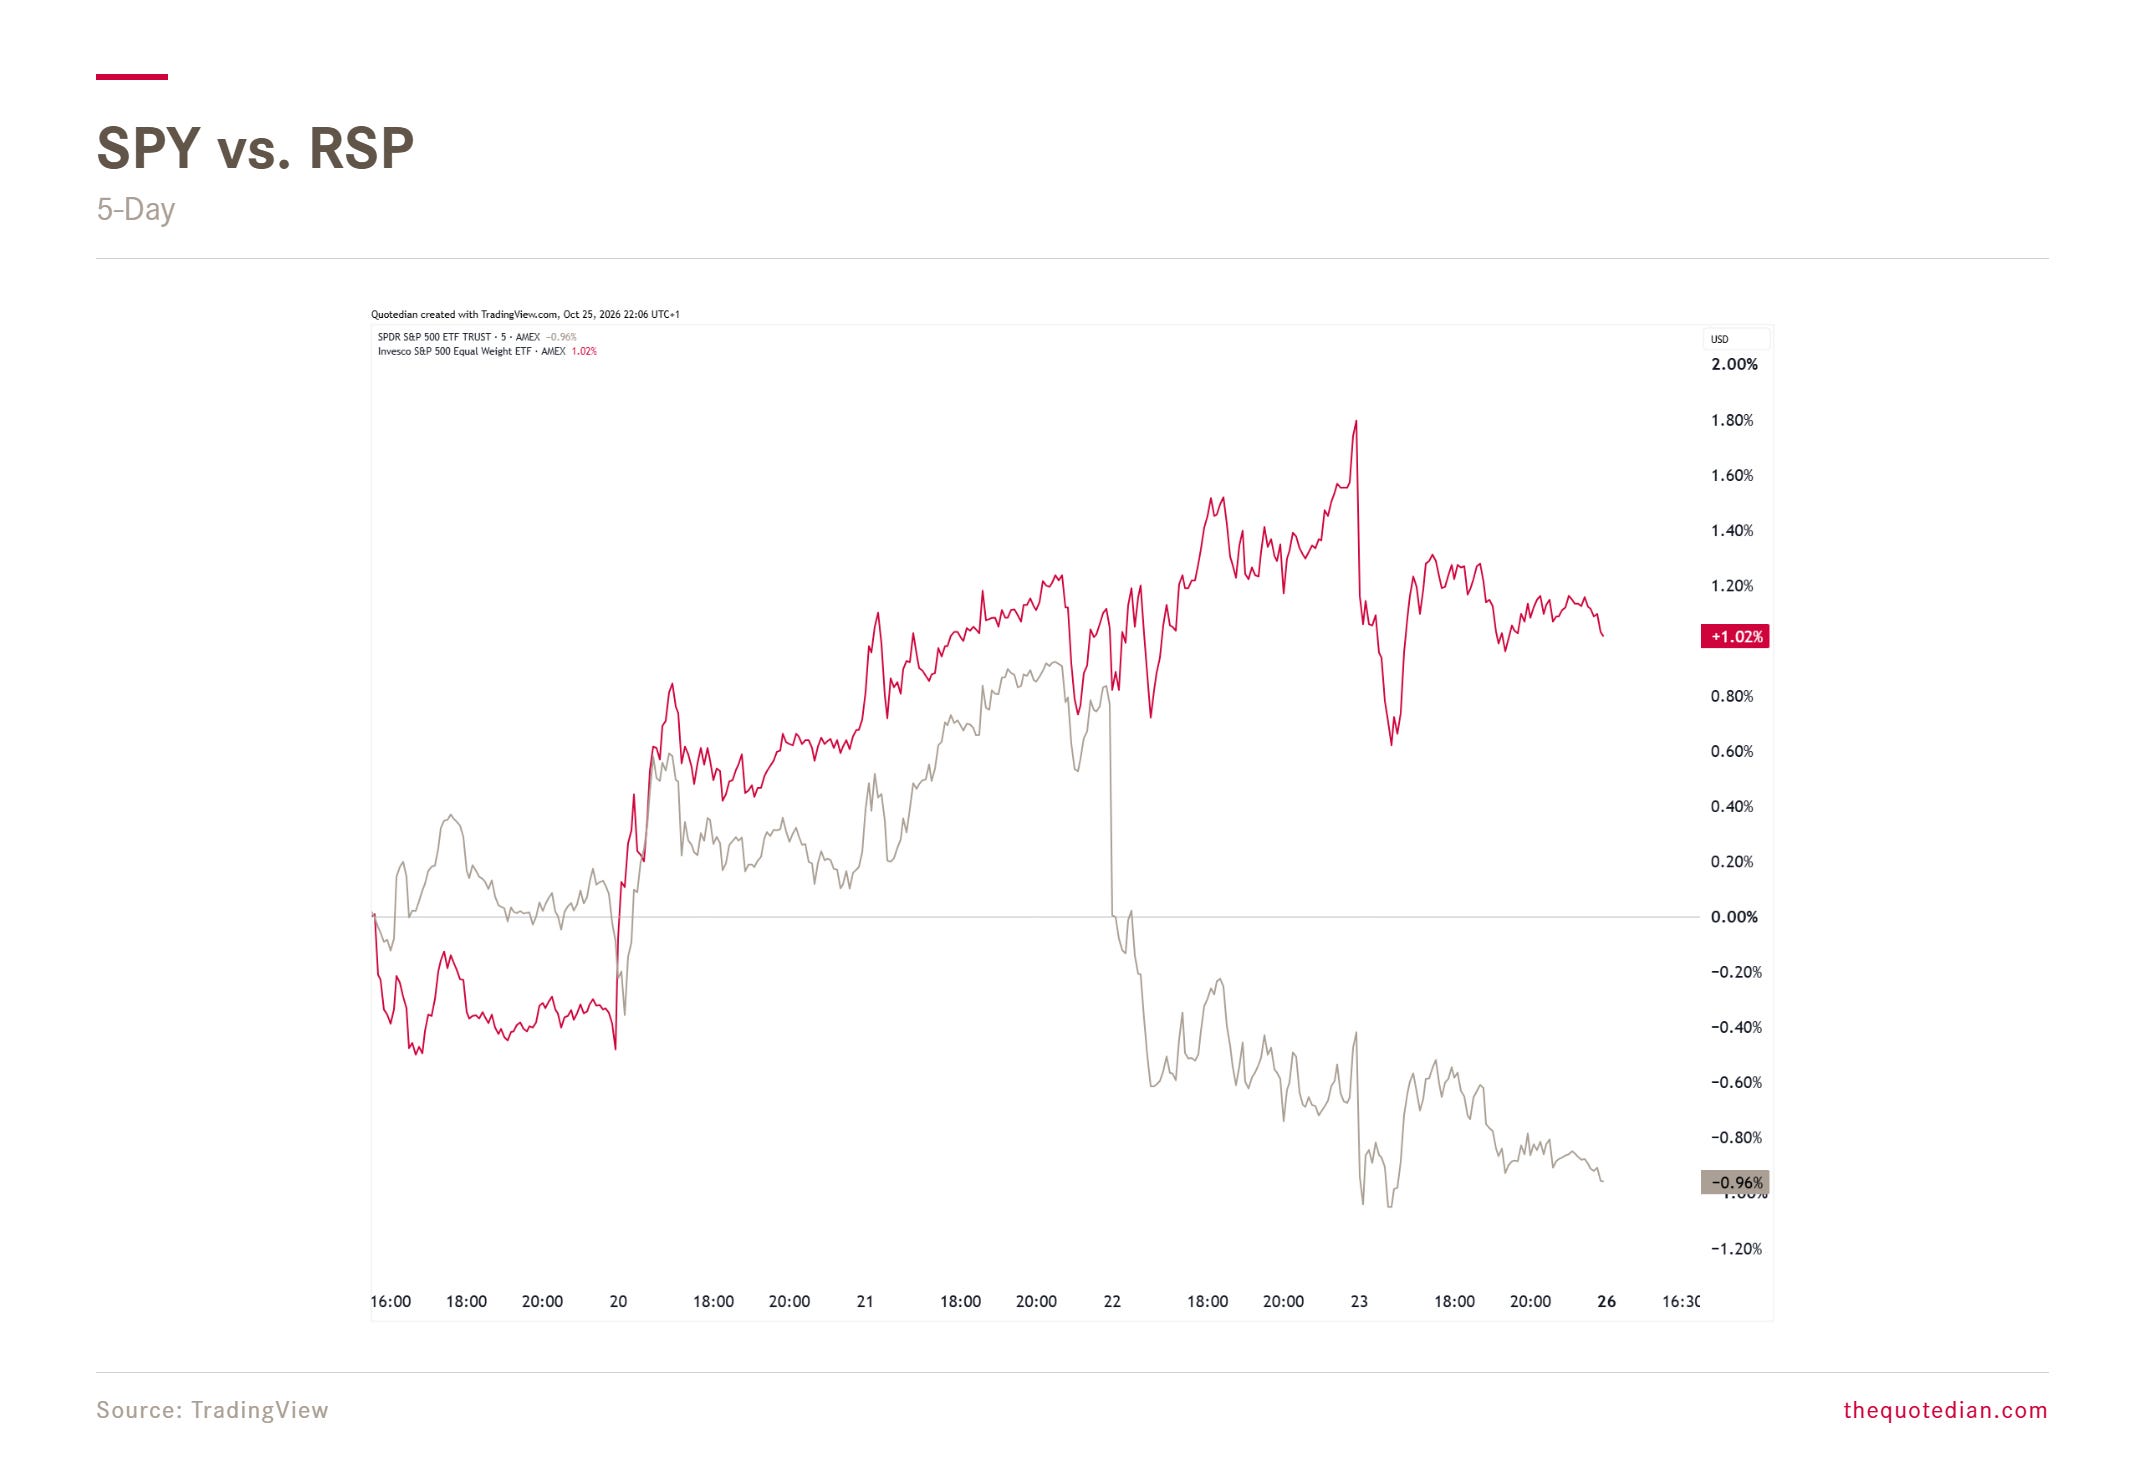
Though actually, it was not THAT bad … mostly so for passive investors which allocate to the most expensive overweight stocks in the cap-weighted indices:
Or those riding the AI-trade to the full, where the past month has been an authentic sh.t show:
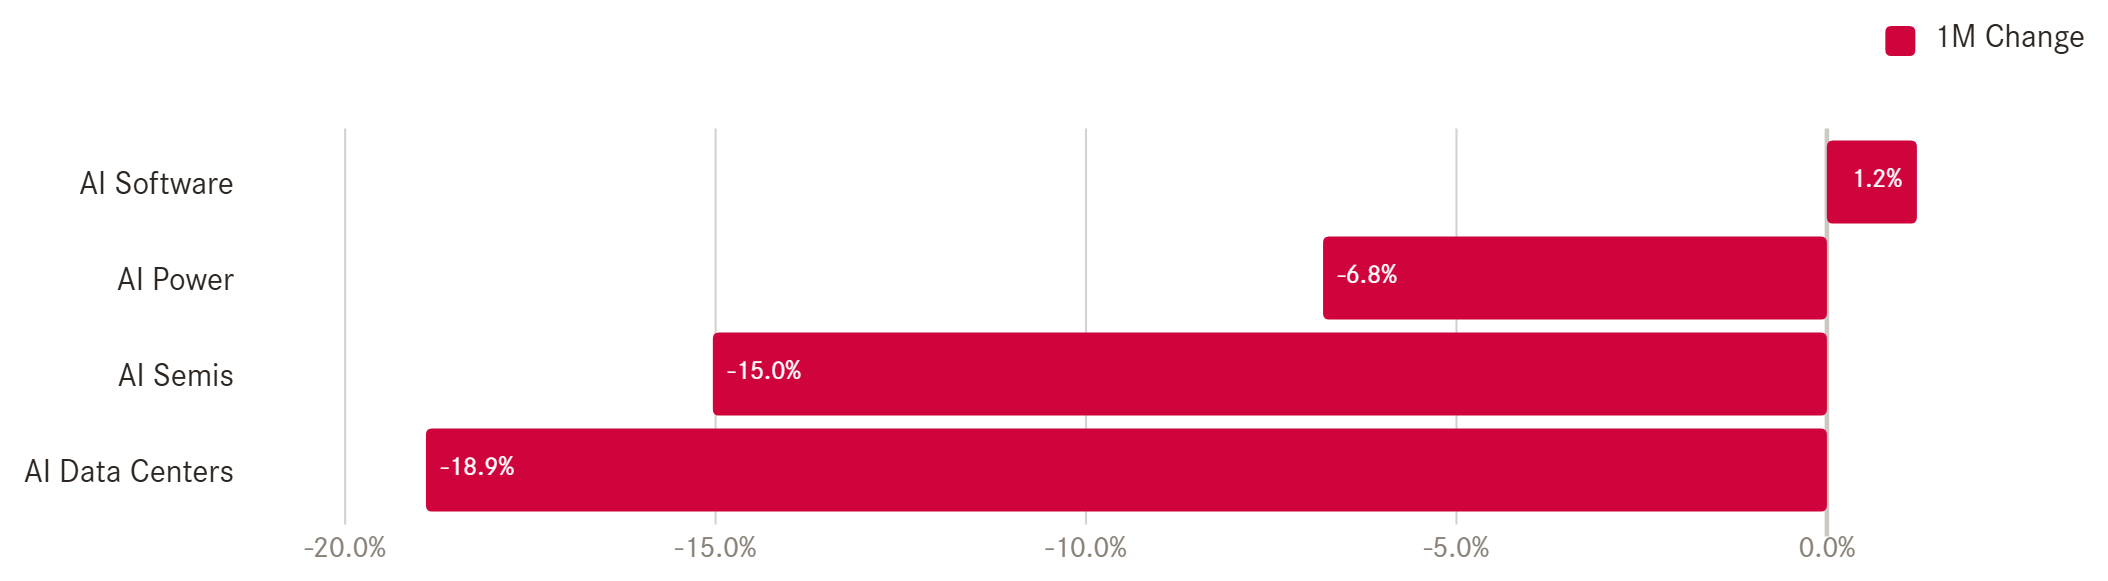
As a matter of fact, the GS US Broad AI basket, which according to its Bloomberg description, consists of US-listed companies that are pursuing the development of artificial intelligence across all categories: hyperscalers, data centre infrastructure, equipment suppliers, power, and commodities is down to a nearly identical drawdown during the July sell-off:
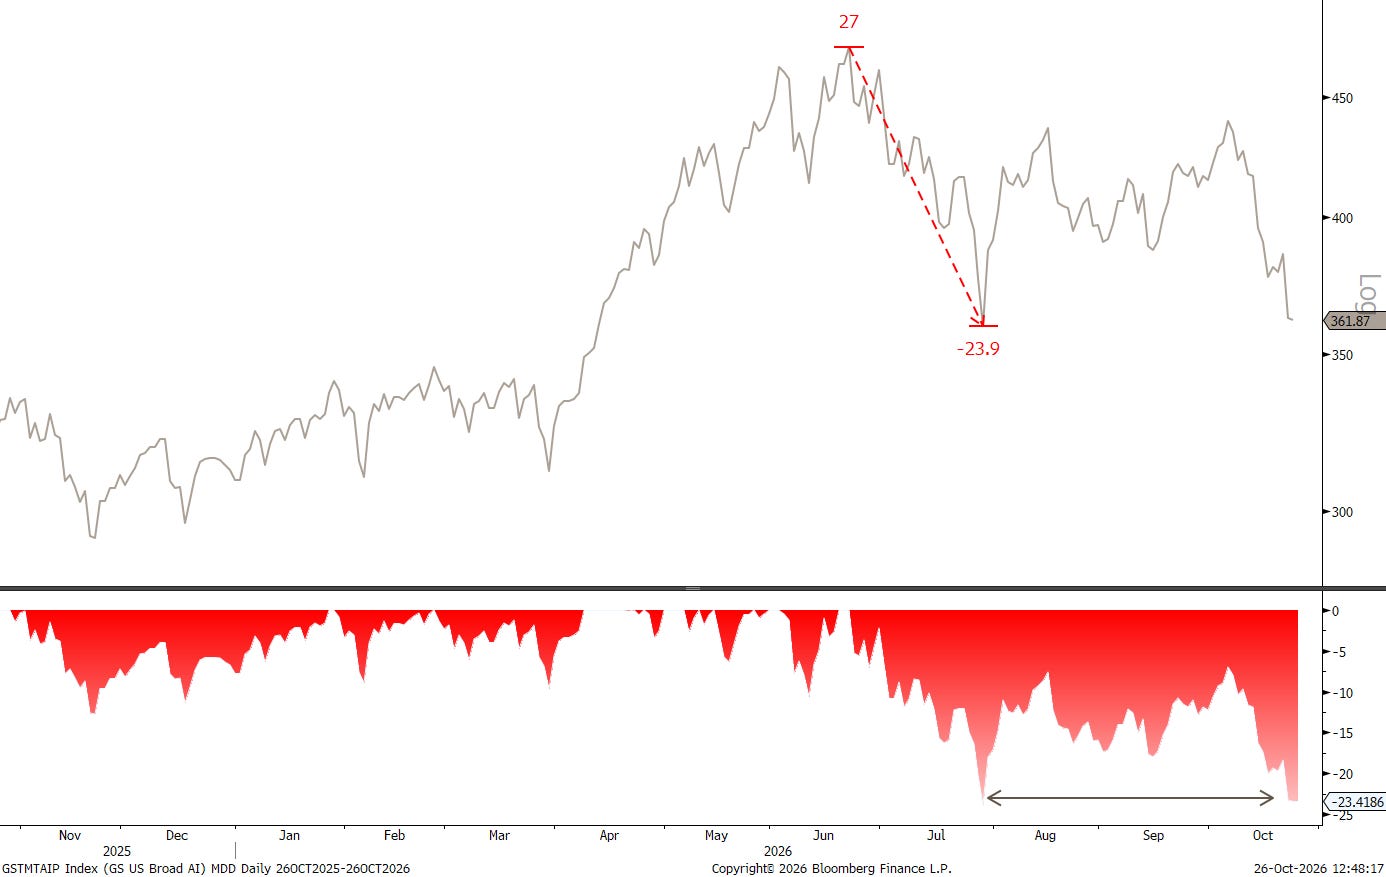
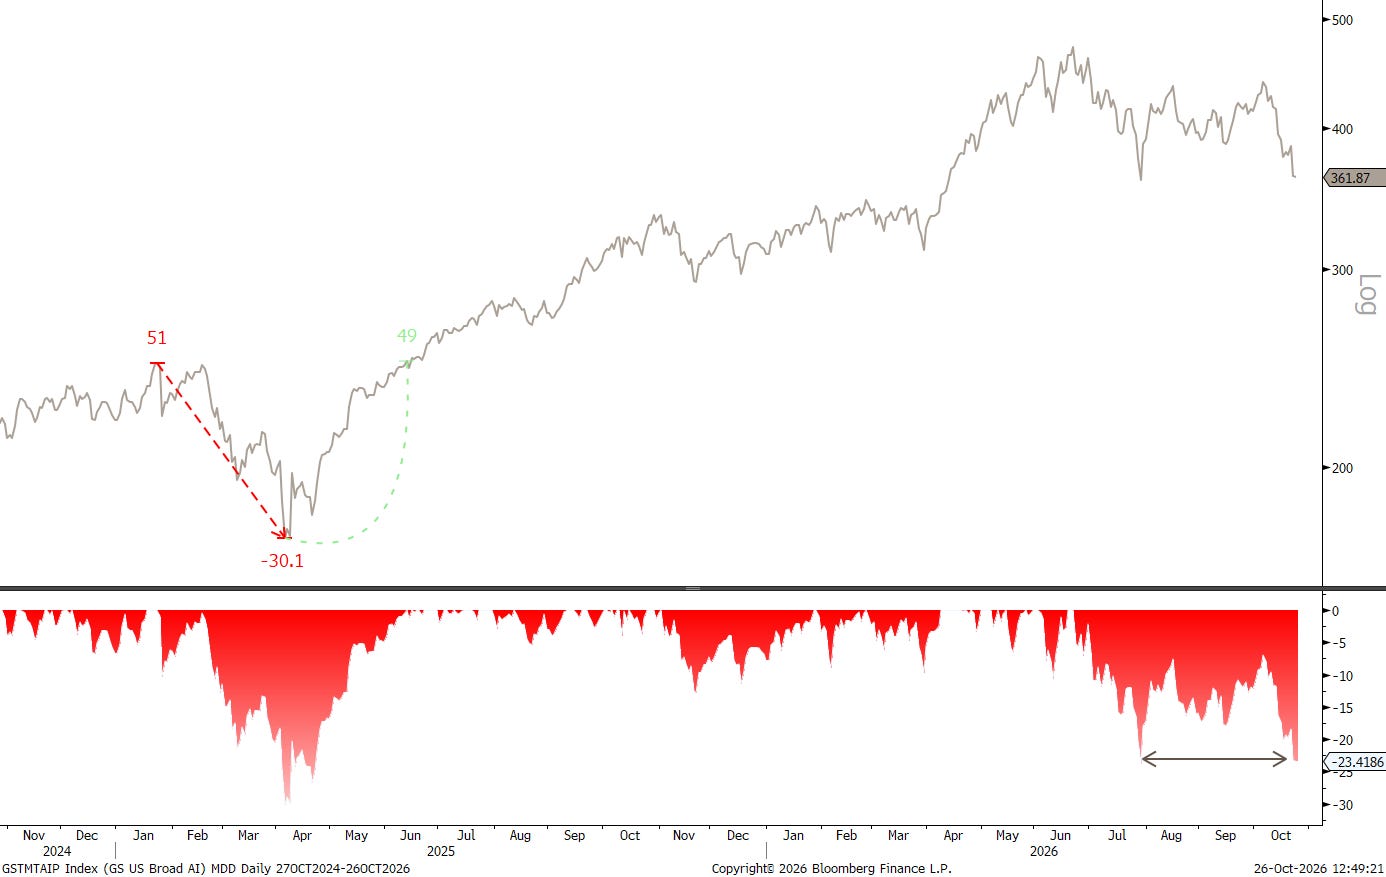
But before you dive and try to catch that falling knife, there have been larger pullbacks, like for example during Q1 of last year:
But then again, the setup in semiconductor stocks for example is tempting:
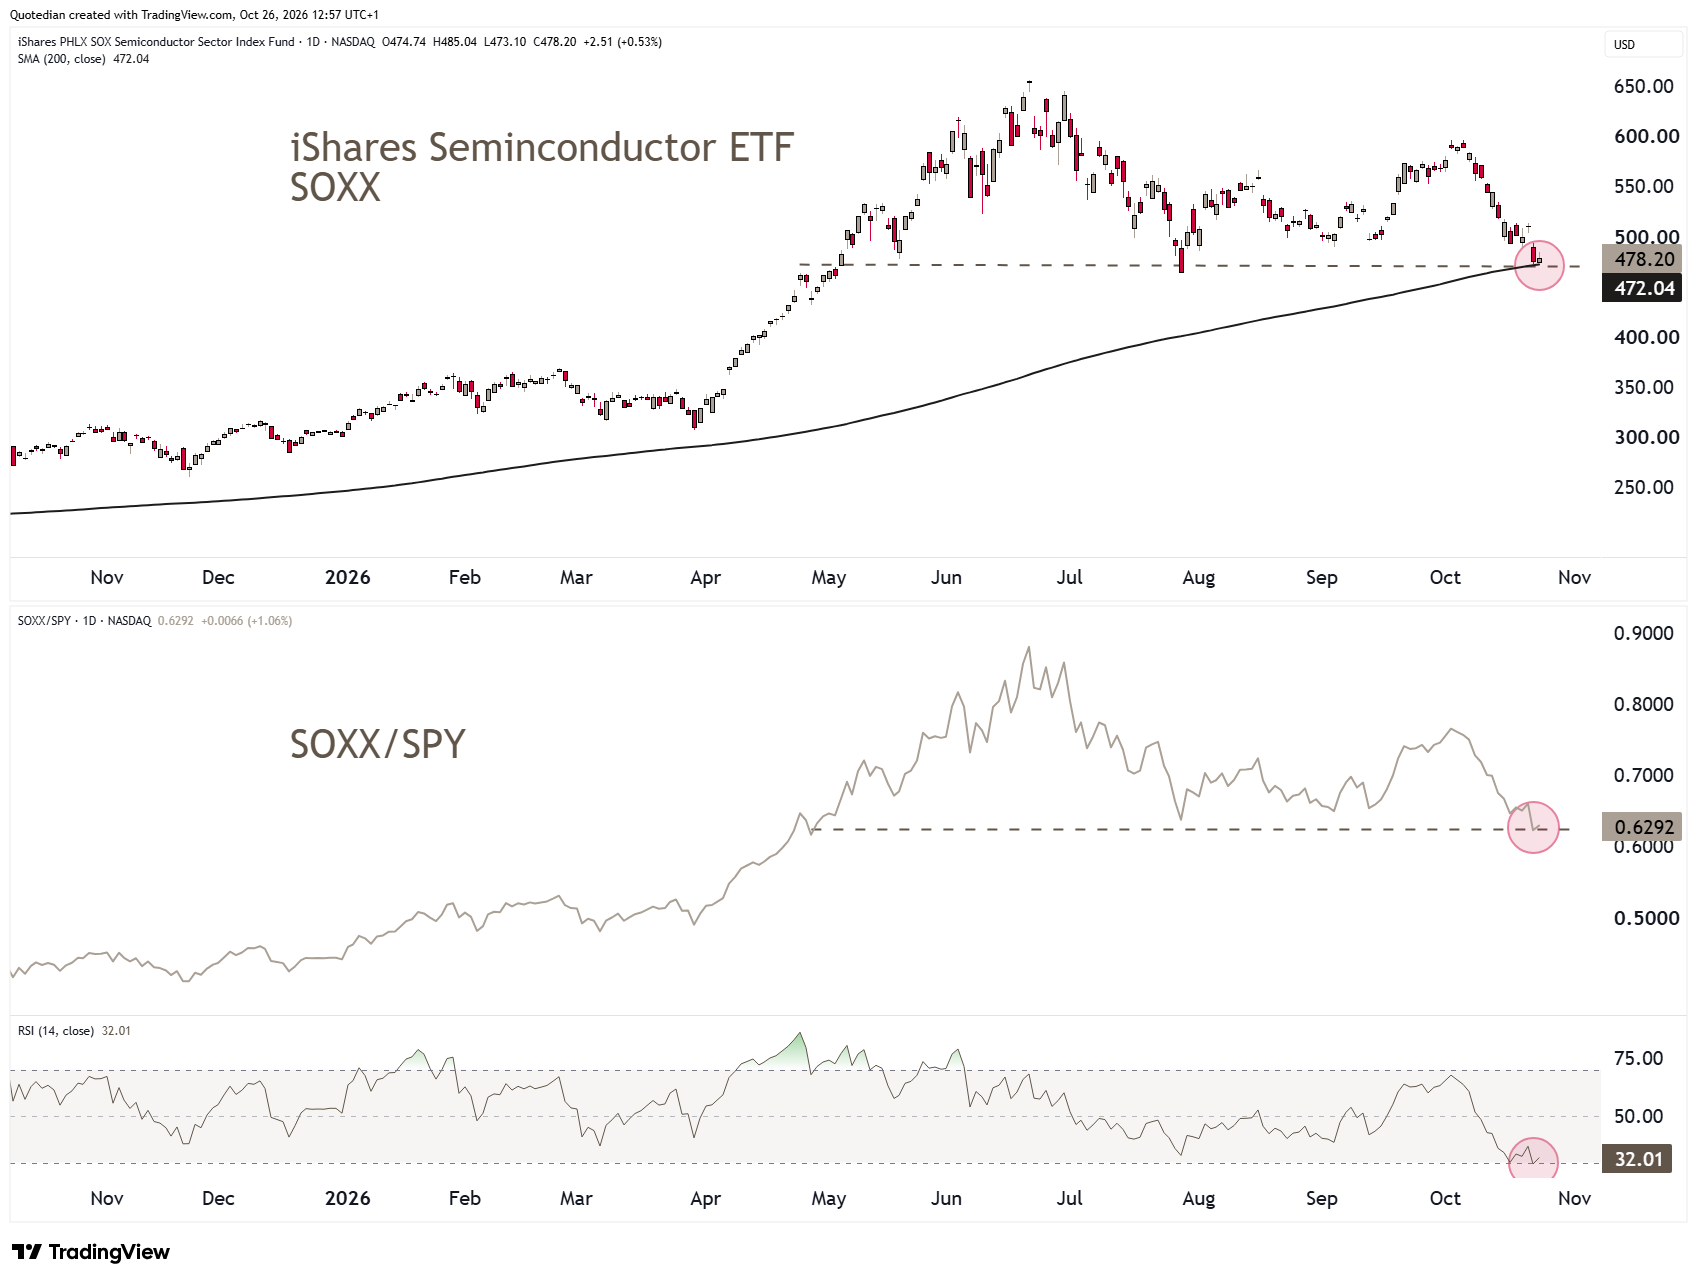
Worthwhile a dabble to the upside?
Probably!
Just don’t forget to set a stop loss!
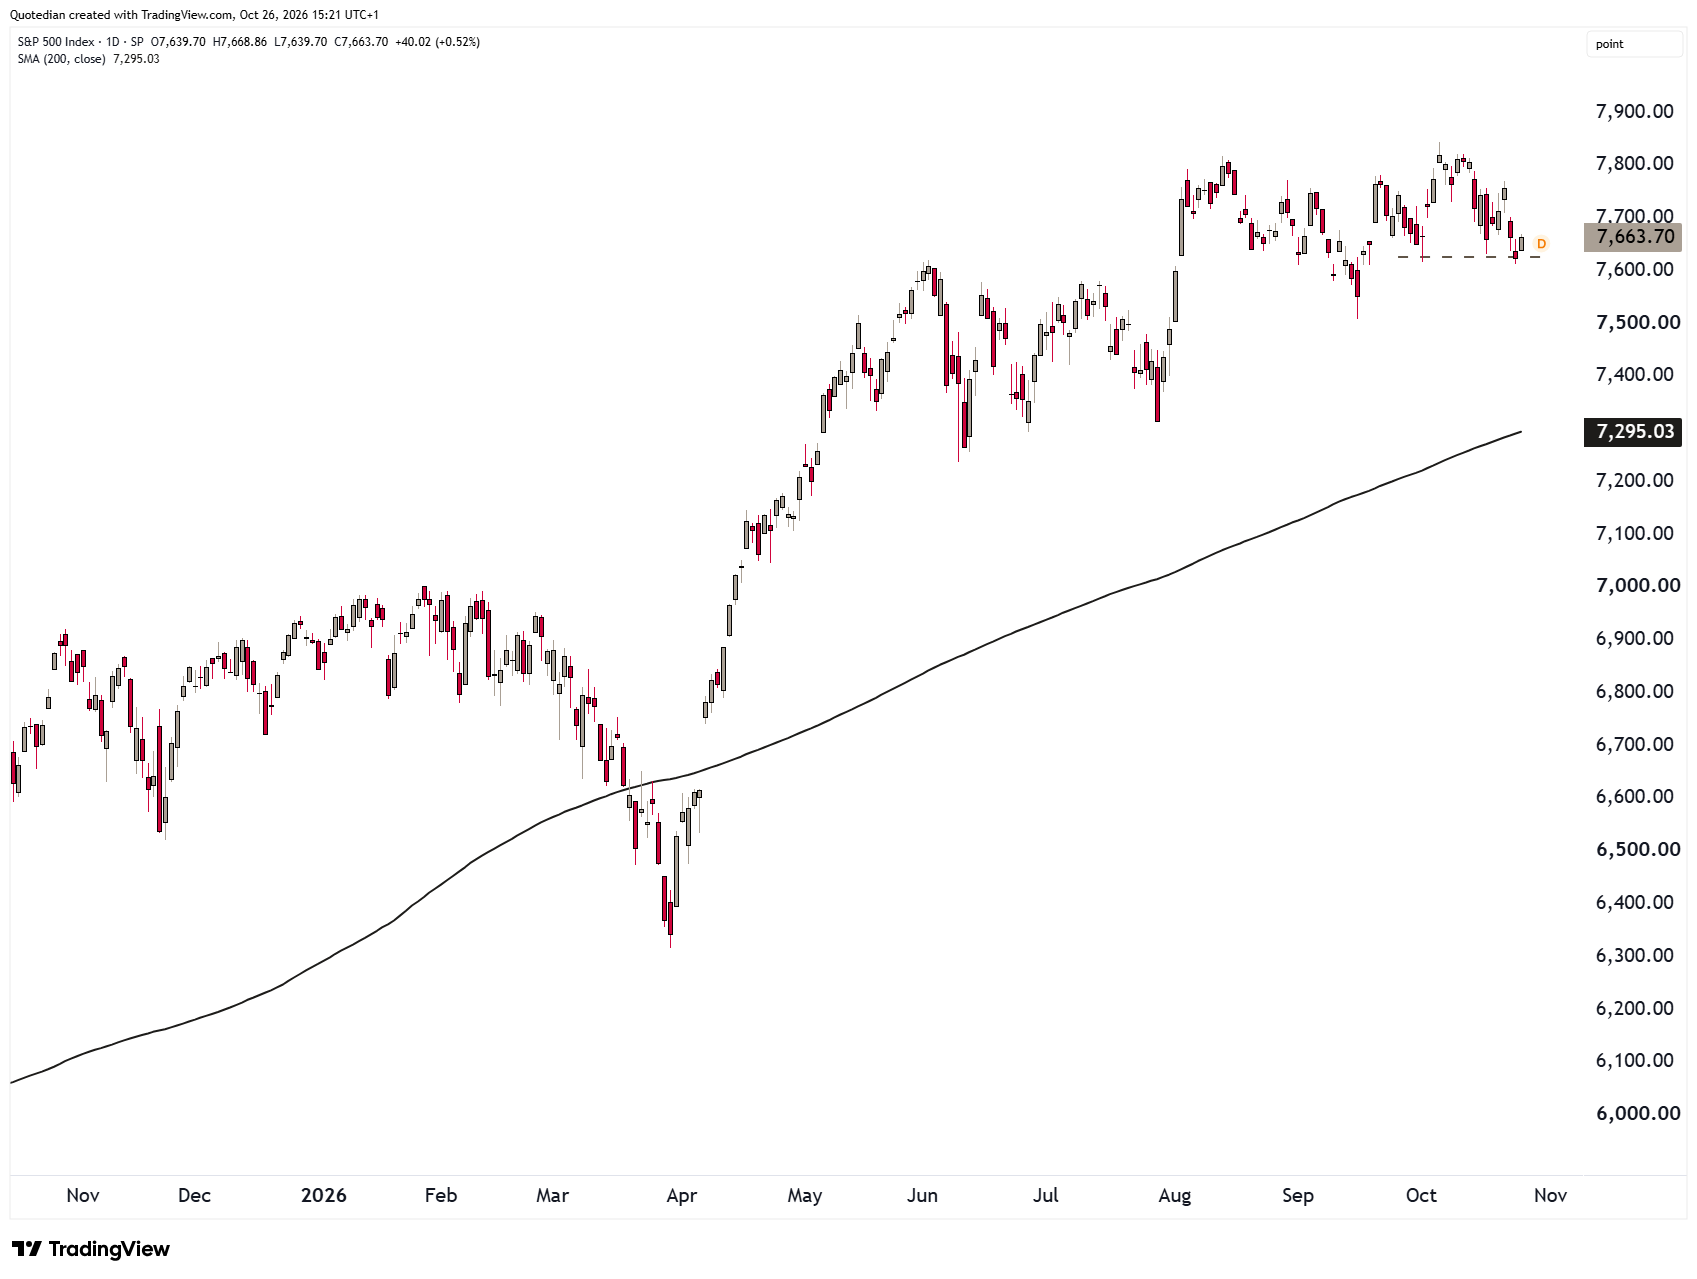
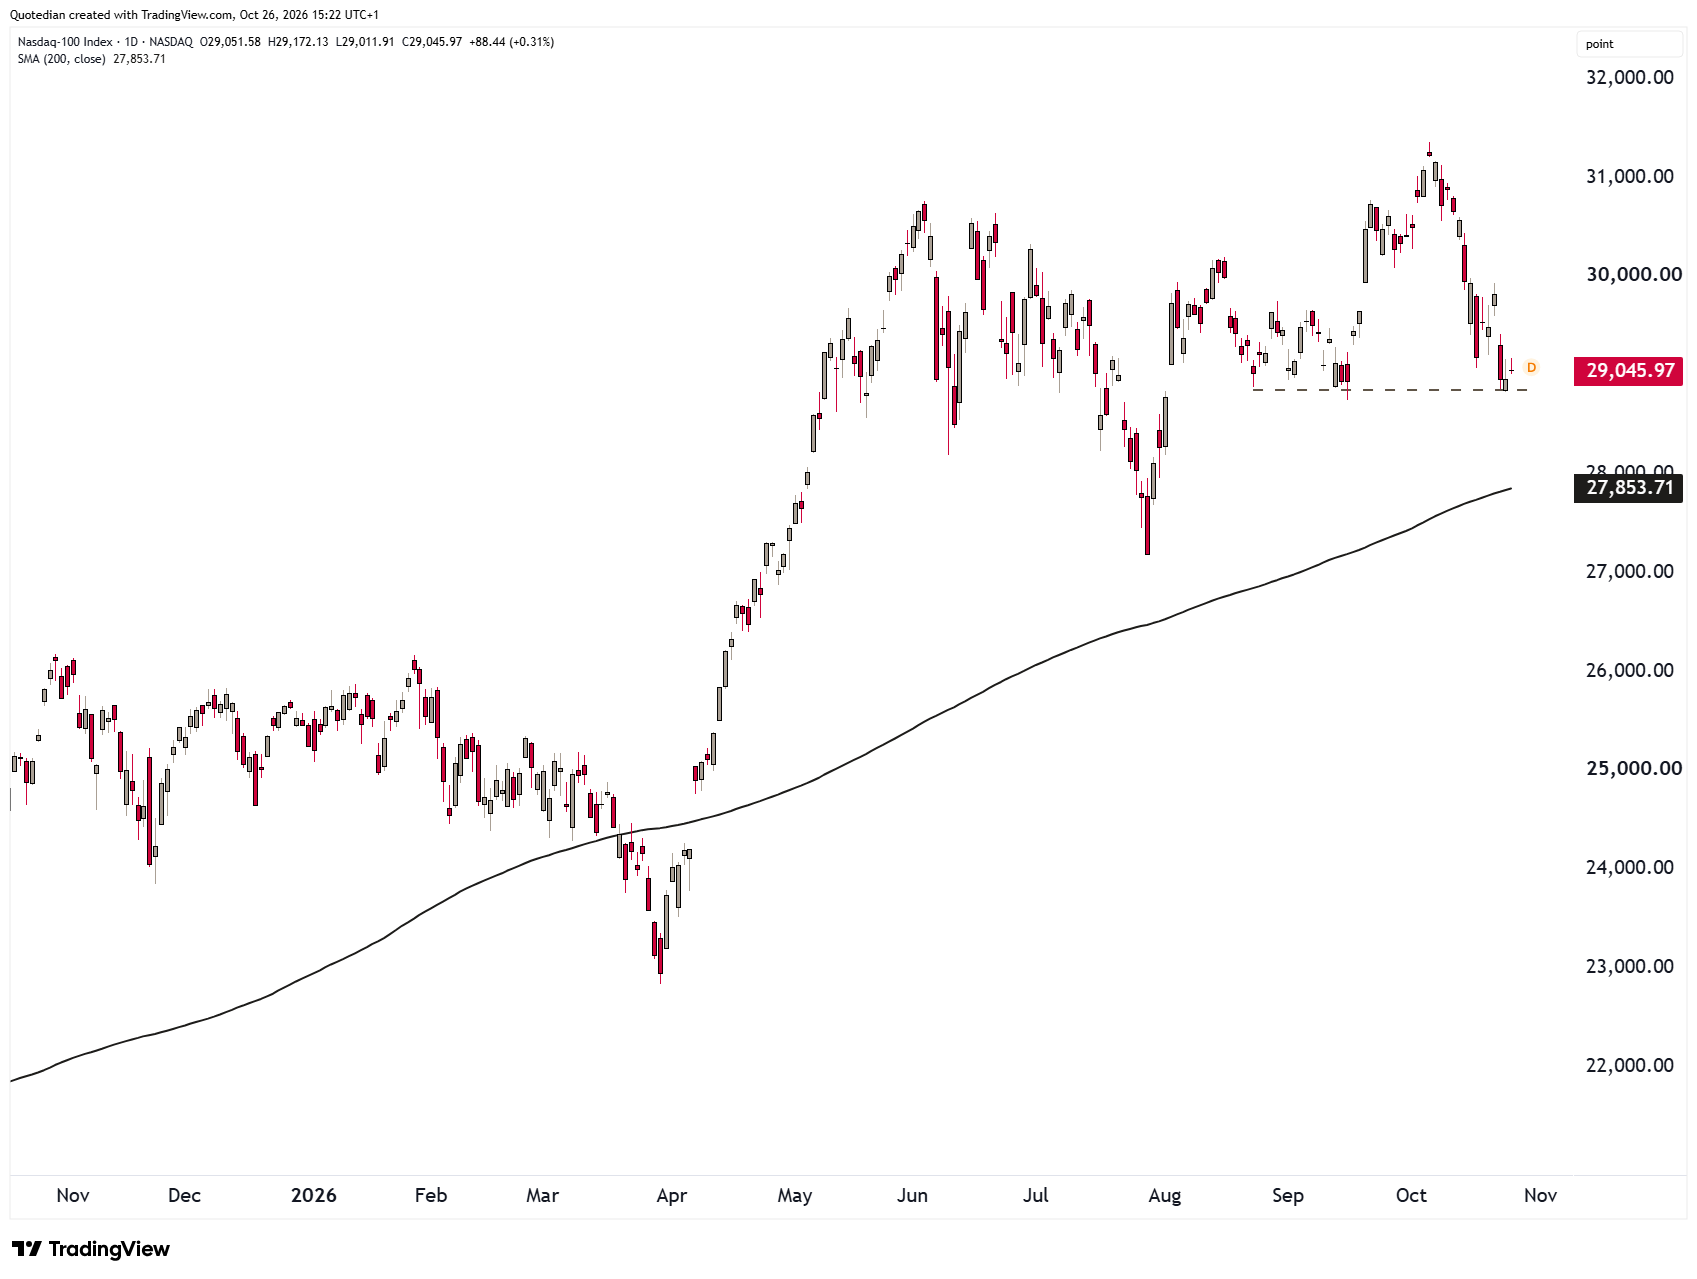
Many indices may be poised for an at least short-term bounce here. For example the S&P 500:
Or the Nasdaq 100:
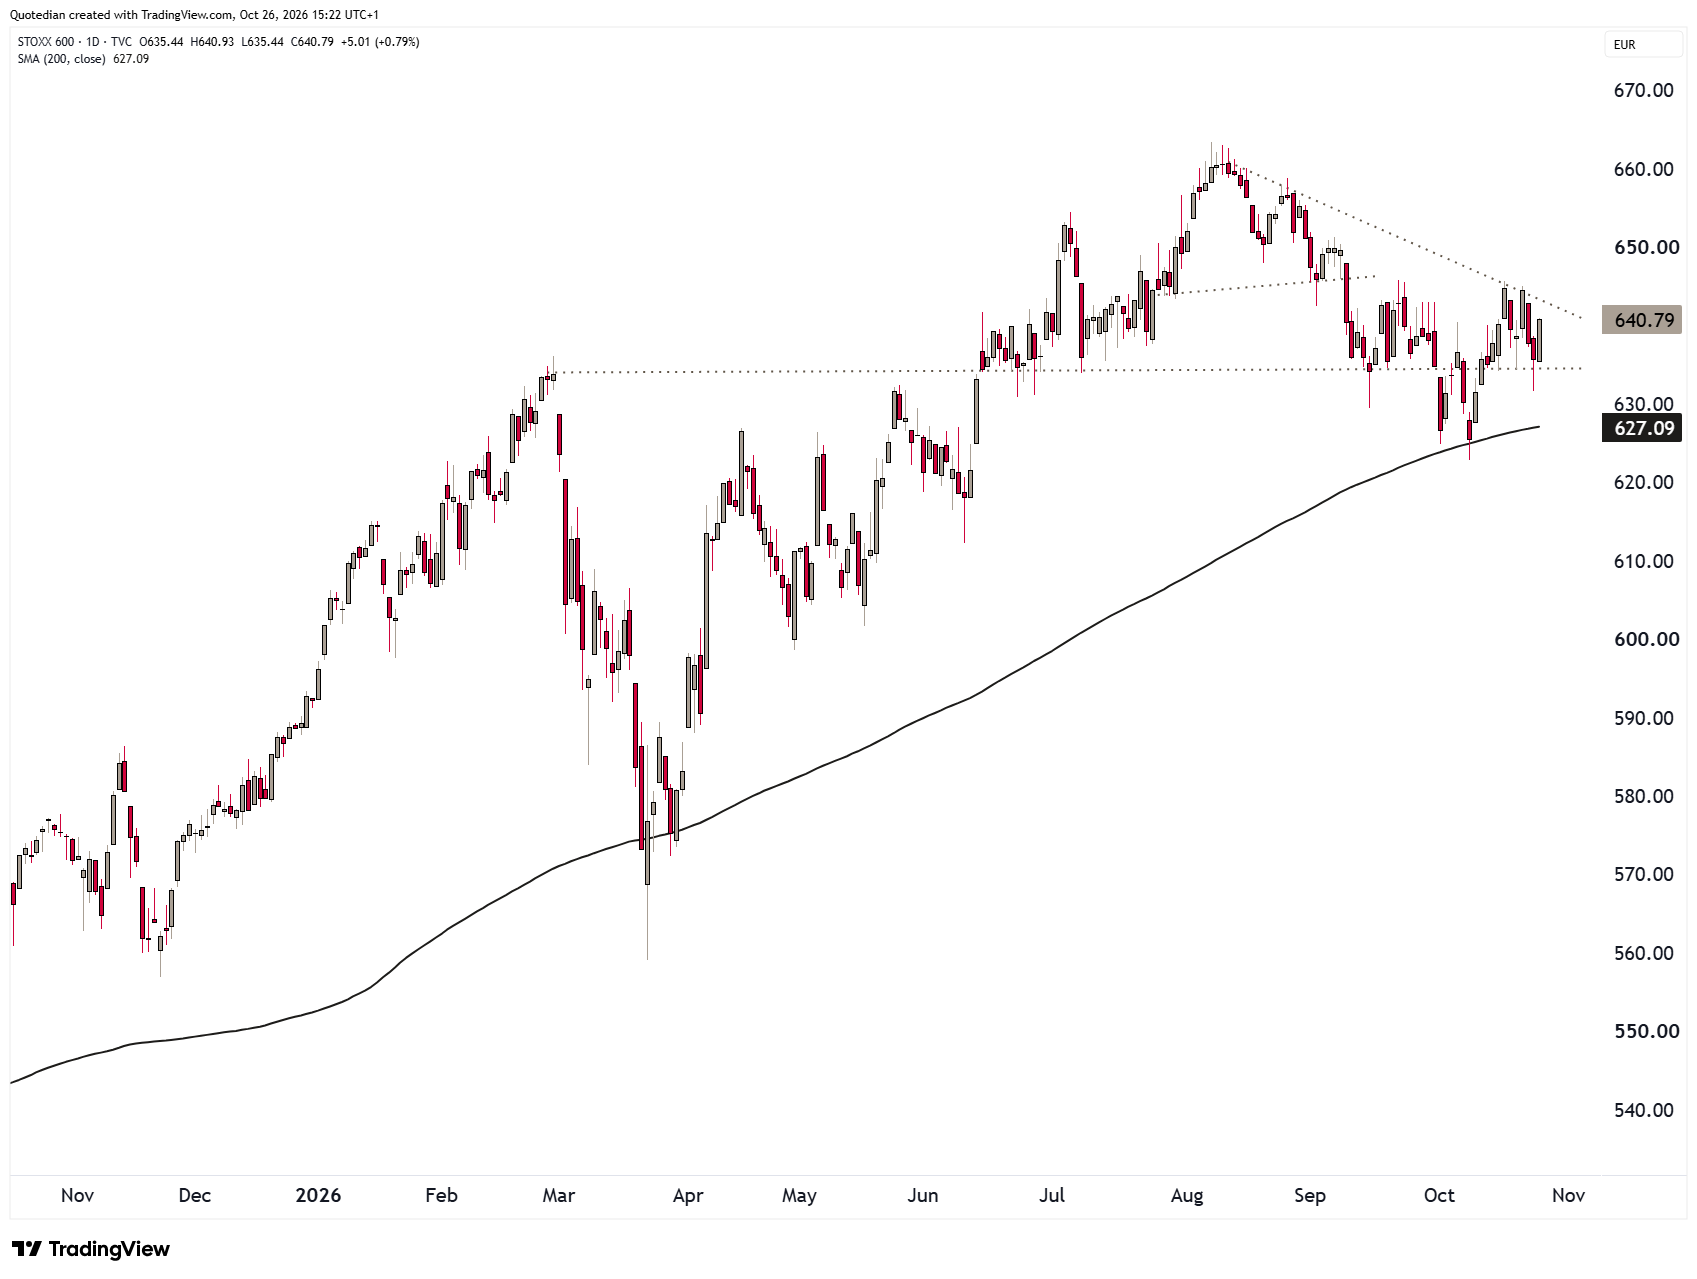
European stocks (SXXP) even look halfway constructive here,
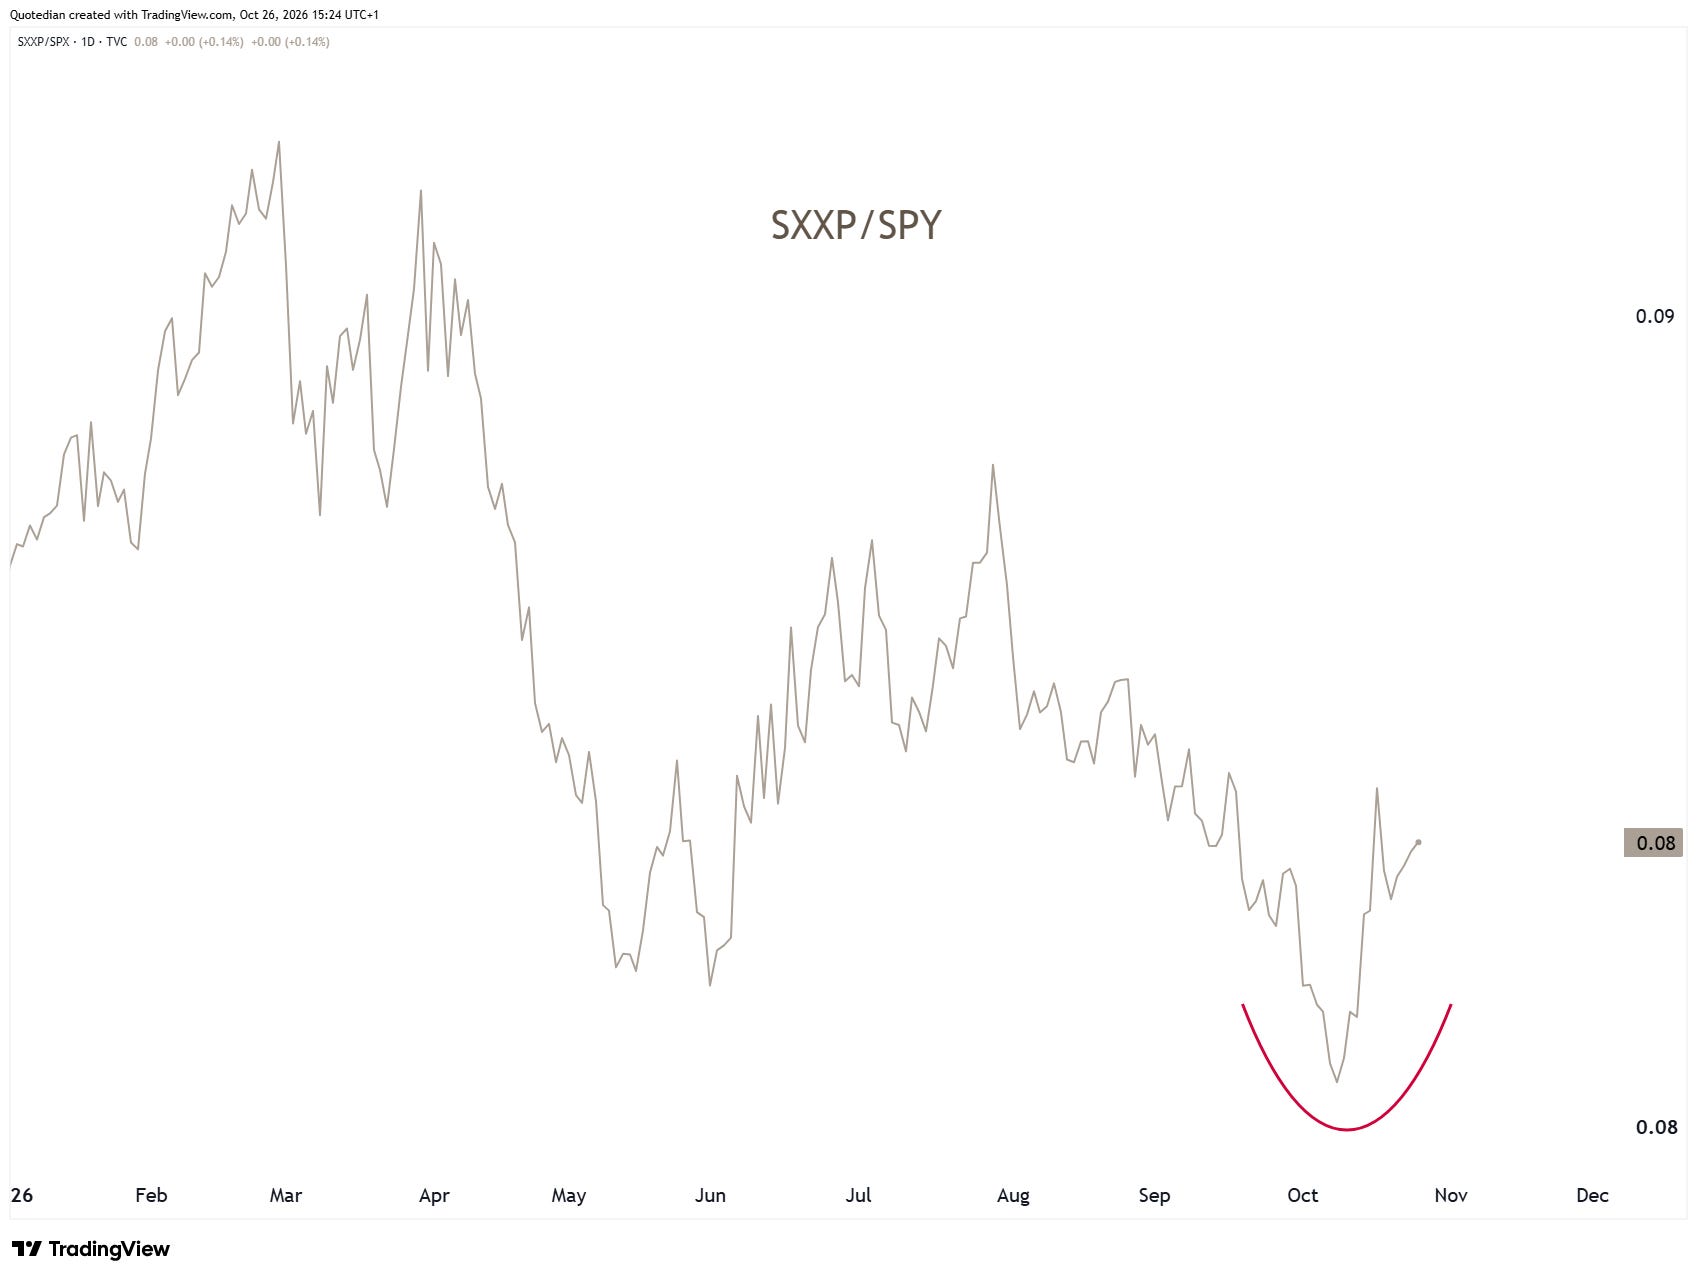
and have been outperforming their US counterparts on a relative basis over the past two weeks:
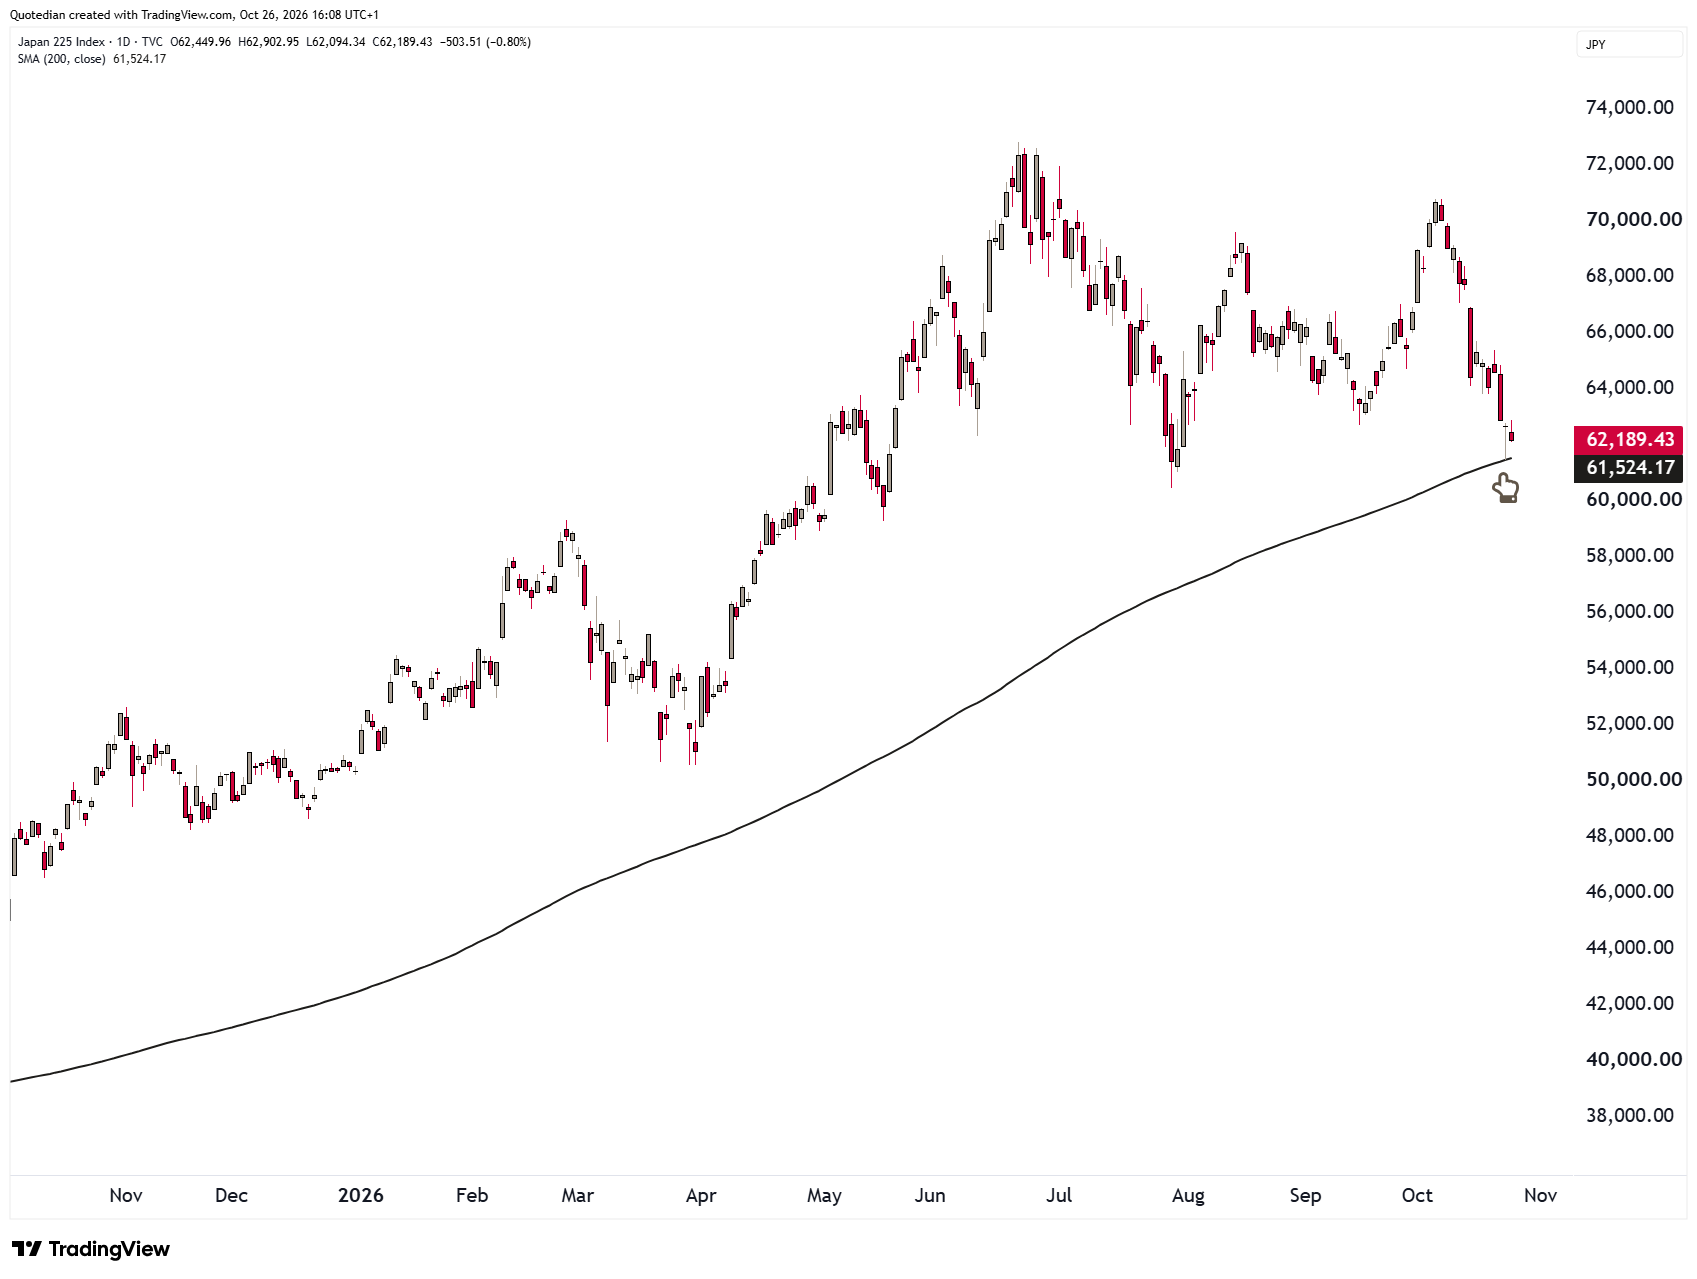
If you don’t buy the Nikkei here, don’t buy it until much lower then:
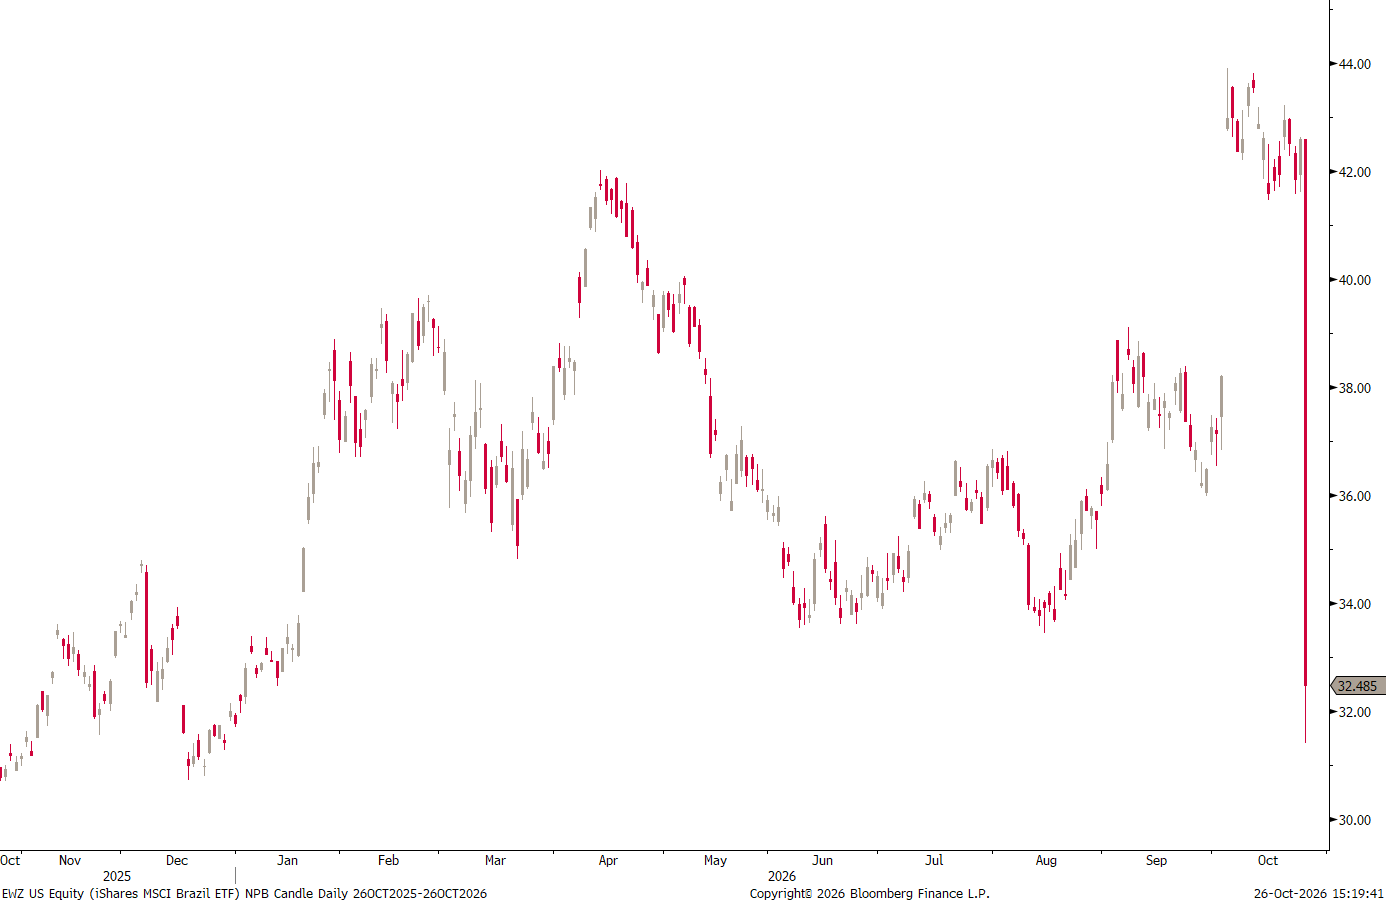
And just to finish the equity section - now, THAT is what I call a candle on the iShares MSCI Brazil ETF (EWZ), after Lula’s surprise election turnaround:
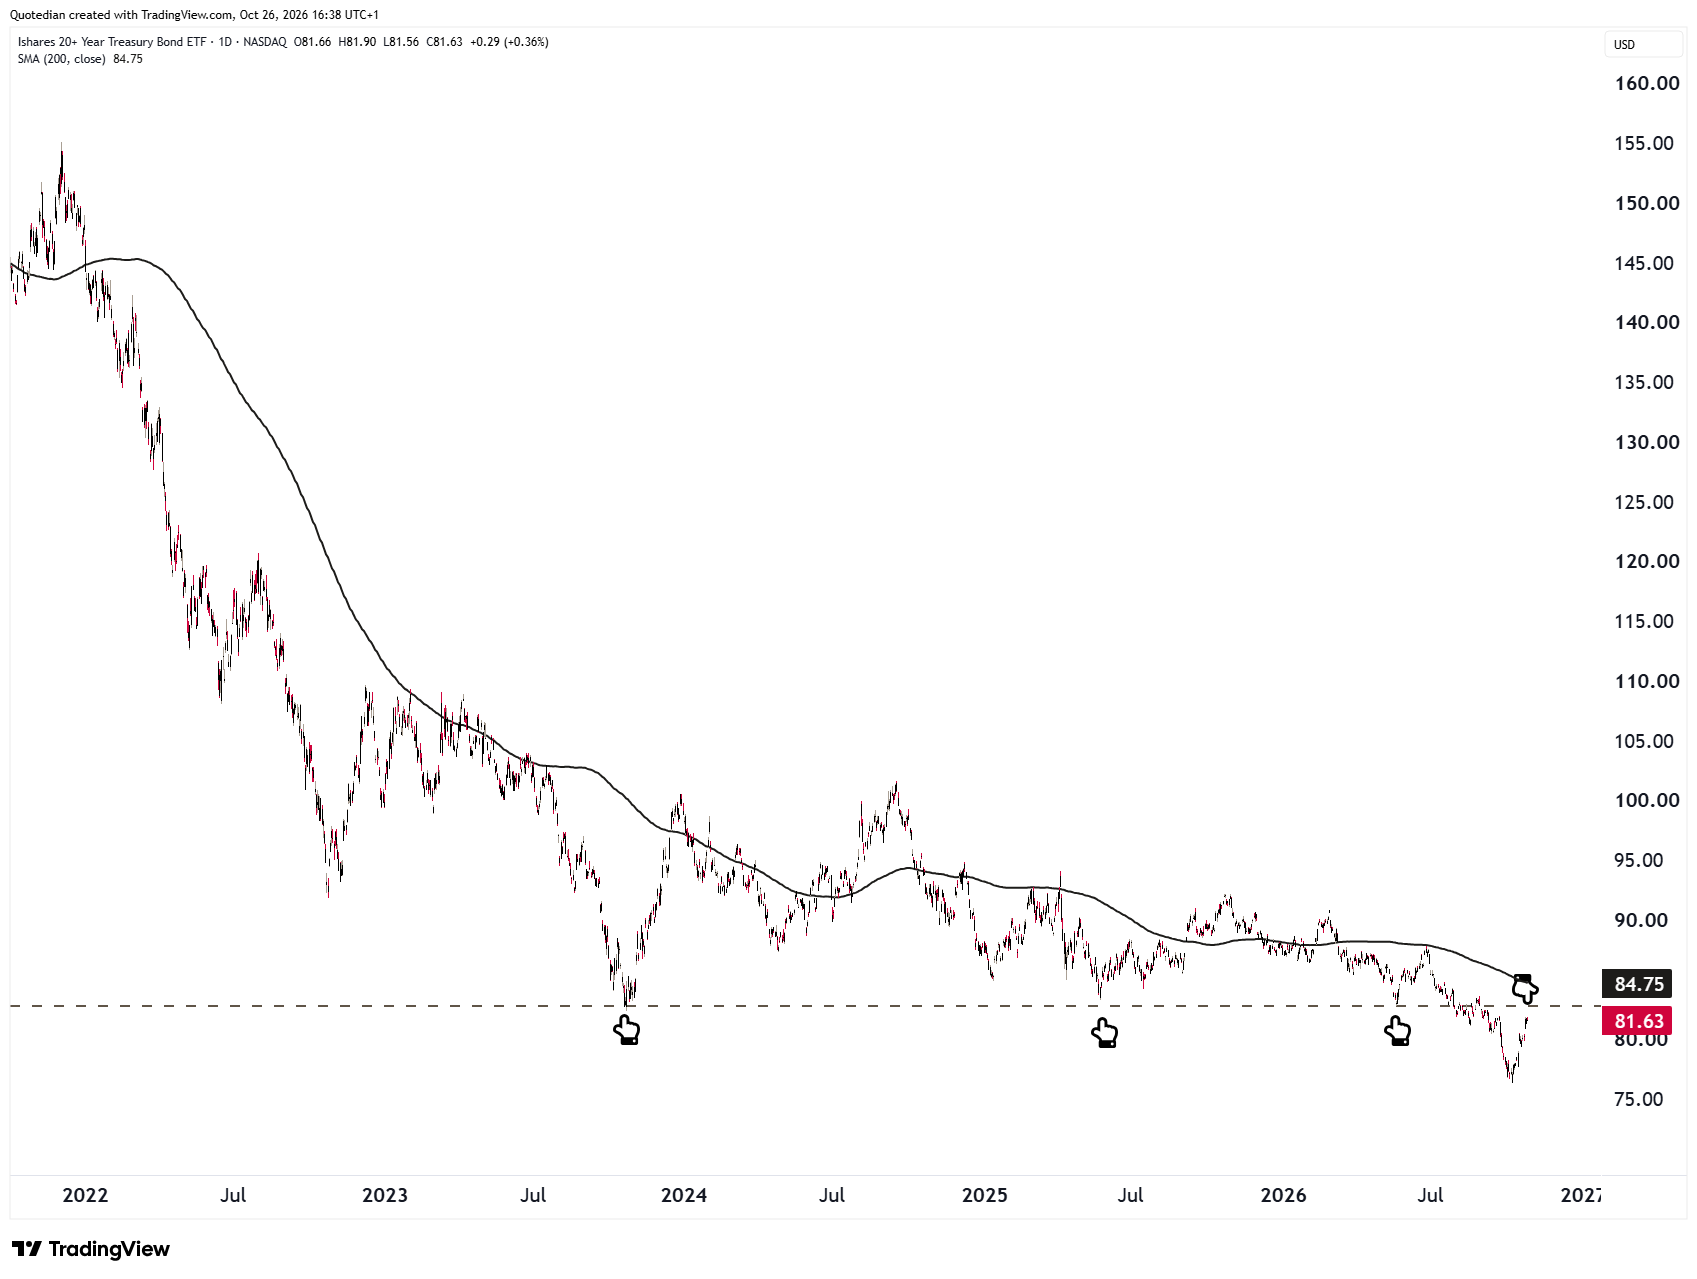
The bond market, taking the iShares 20+ Year Treasury Bond ETF (TLT) has a proxy, is continuing its recovery after the now famed The Economist “Will Bonds Blow Out” magazine cover bottom. Next stop is the previous support (dashed line) now turned resistance, thereafter the 200-day moving average (thick black line):
There are four central banks (Fed, BoE, BoJ, BoC) setting their interest policy this week, but the big one is of course the FOMC (Fed) decision on Wednesday evening:
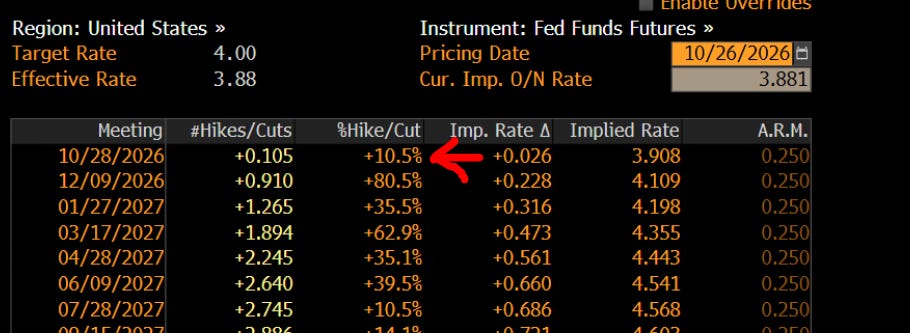
As we can read out of the table above, the market implied possibilities for a rate hike this week are only at 10%…
… but I say, what if … just assume, what if …
I would at least look to position myself for such an outlier chance with a tiny short on the stock market and or a long (in bonds) on the back end of the yield curve.
Even if Warsh indeed does not hike, his tone may be super-hawkish.
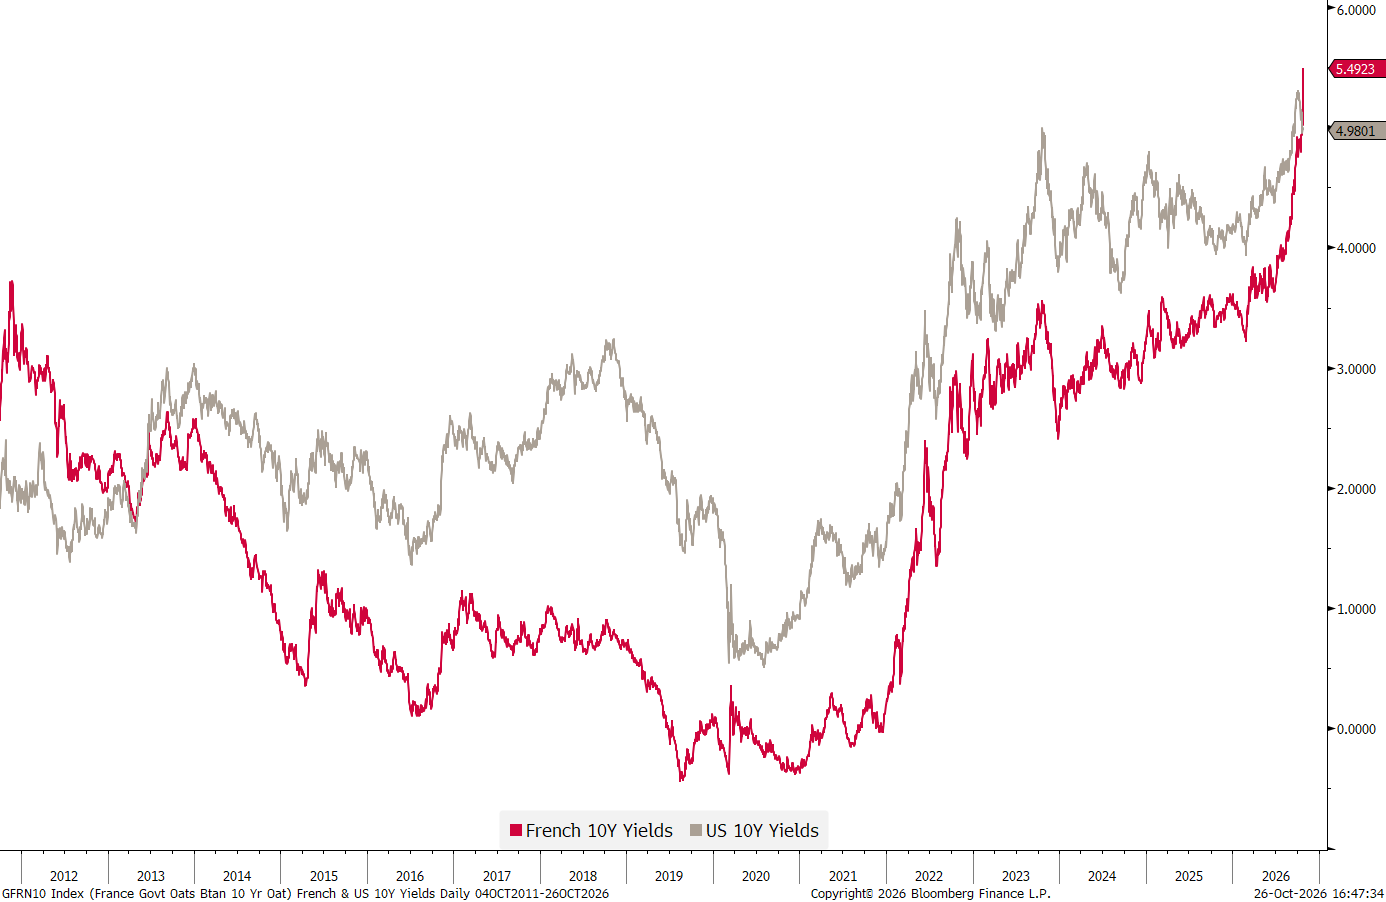
Meanwhile in France, the 10-year government bond yield traded briefly above its US counterpart last week - a first in 13 years:
Aren’t we lucky then, that at least Moody’s (a paid service, btw. … just saying…) is giving its full confidence vote in favour of France.

To me, and please look away now if you are faint at heart, the only question remaining is then:
Too big to fail?
OR
Too big to be saved?
Frexit, anyone?
Sorry, now you cannot unsee that …
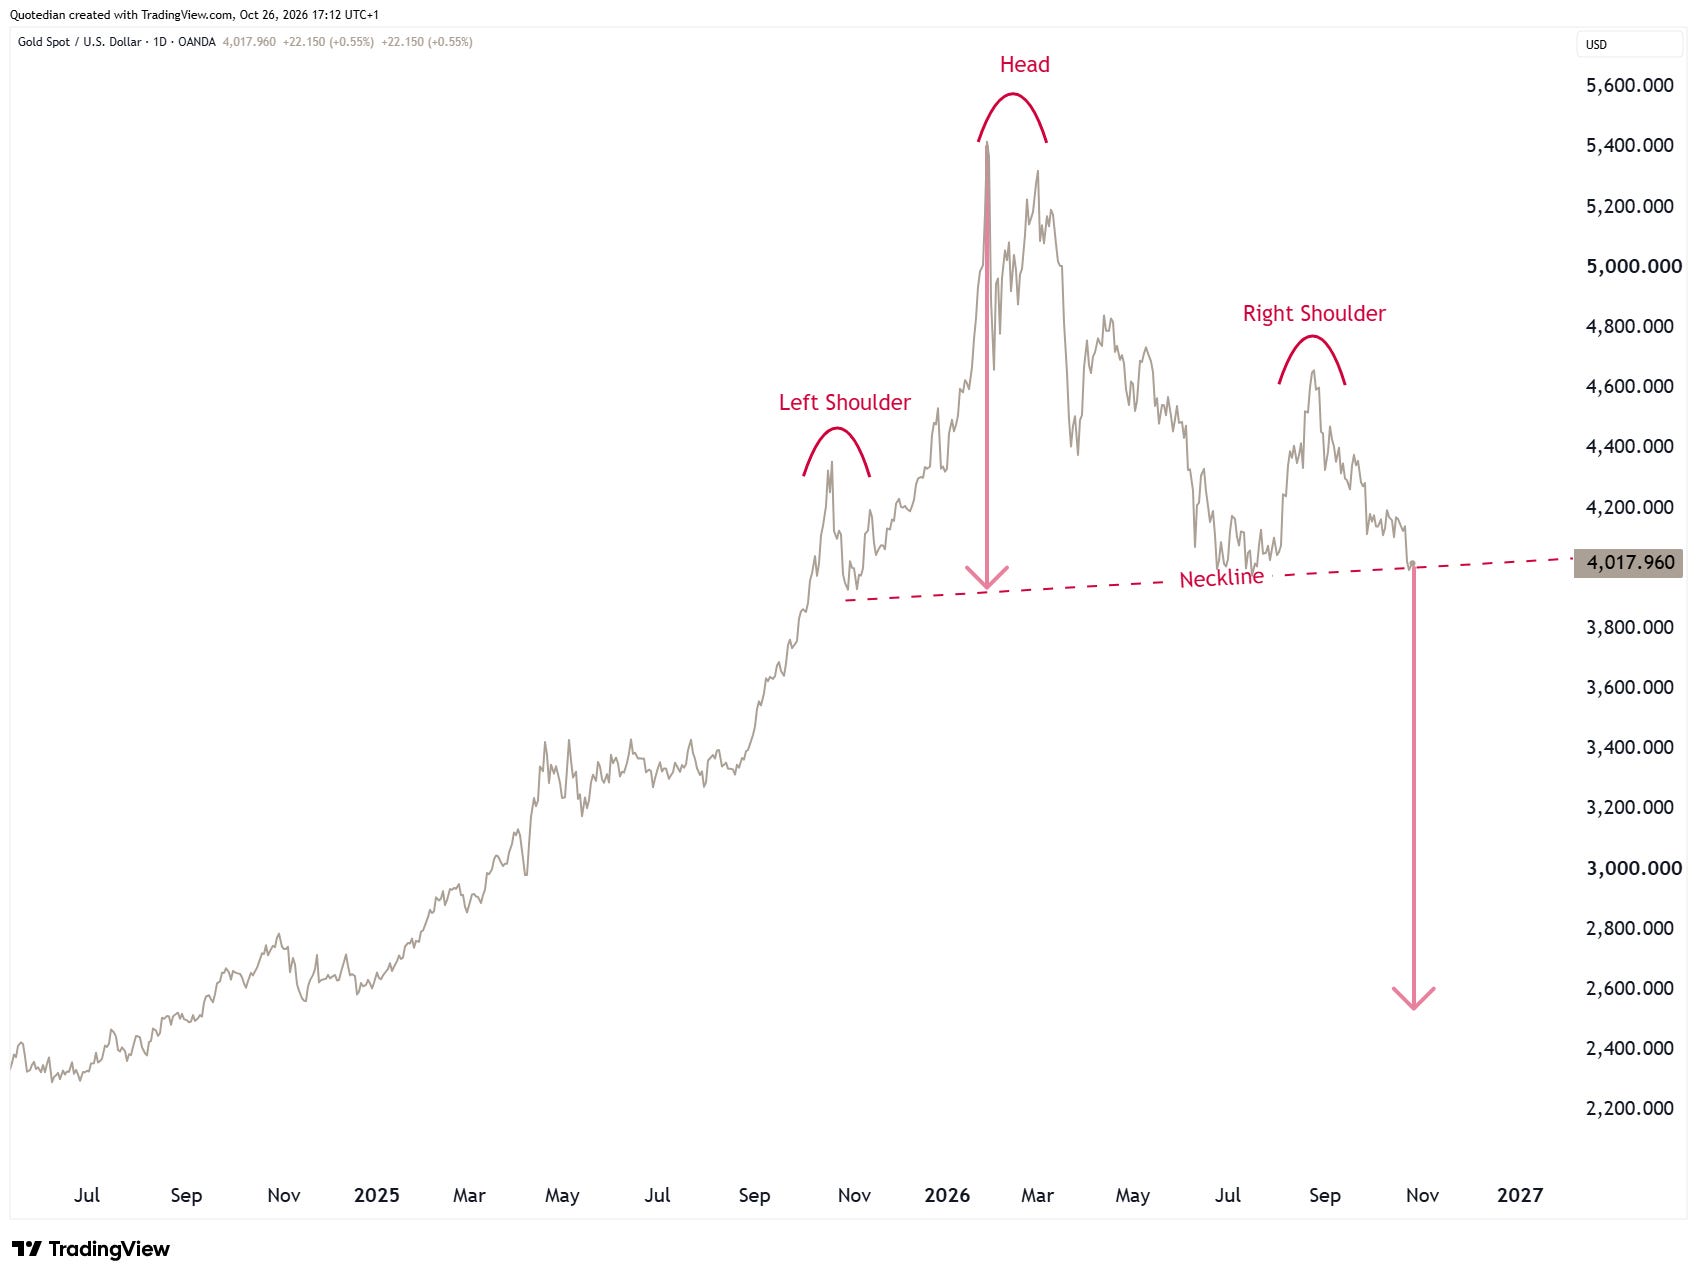
This is the Gold chart nobody wants to see (but which we showed anyone in one of last week’s Daily Qs):
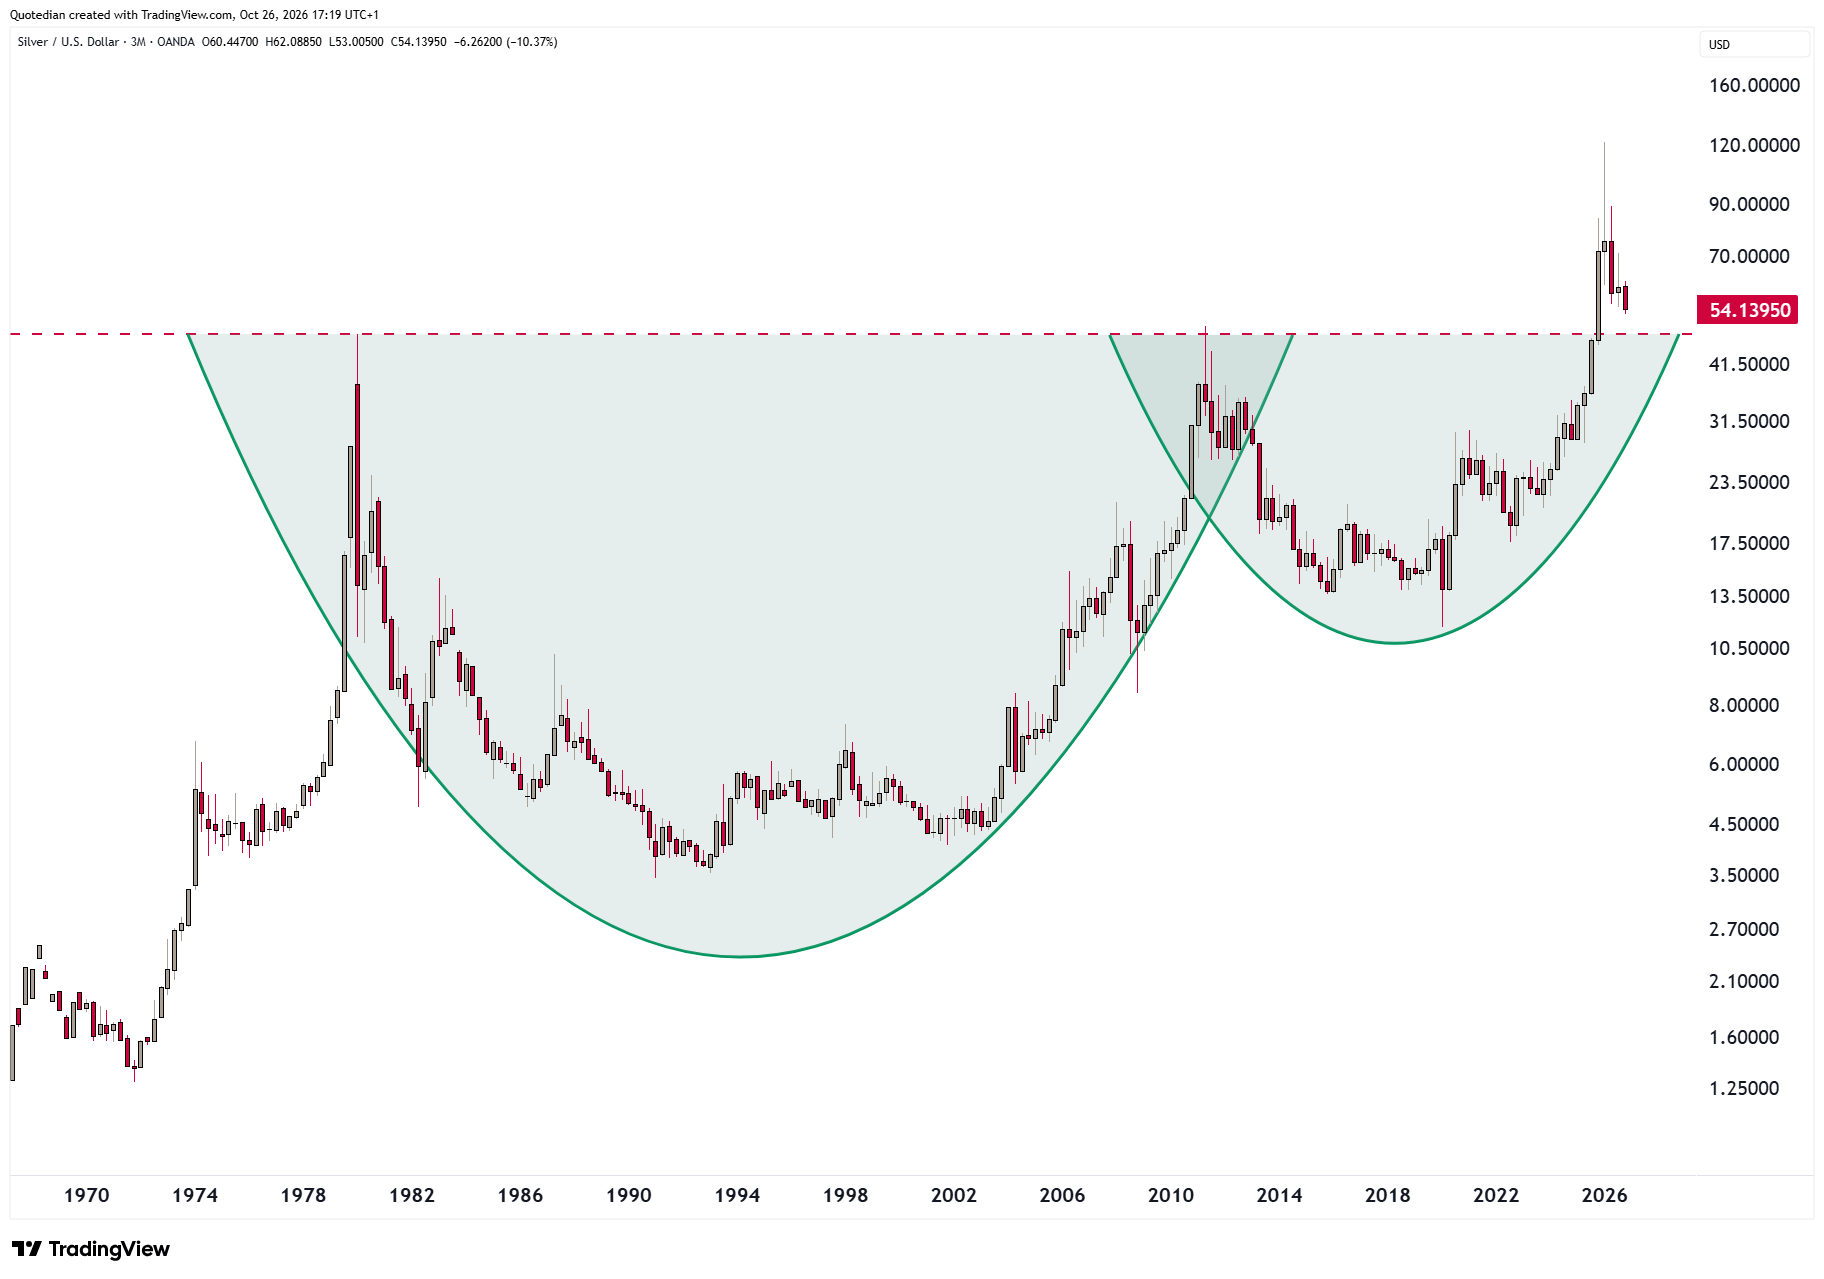
The following chart of Silver, with quarterly candles and on a log scale, suggesting a possible cup and handle pattern, would be much more agreeable to precious metal bulls then, as it would suggest a bottom around the $48-handle with substantially more upside thereafter:

At the end of the introduction I told you that we all know how this gamification of everything will end.
For those who, however, may still be in doubt, here’s how it will end:
In tears.

“It’s tough to find values when everybody is preferring gambling.”
— Warren Buffett, CNBC interview, 15 July 2026
But in the meantime, “May the Betting Odds be with you!”
André

The Important One:
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG
The Legal One: