

“As long as the music is playing, you've got to get up and dance.”
— Chuck Prince, CEO Citigroup, July 2007

Something changed last week.
And no, I don’t mean the US Government structure.
Albeit, the midterm election outcome may have been an accelerator to something happening already anyway.
For starters, the exodus out of AI stocks last week was massive. According to Goldman Sachs:
“Hedge Funds sold AI stocks at the fastest pace in over 5 years & on a trailing 20-day basis, Hedge Fund selling reached a 5-year extreme at -3.0 standard deviations"
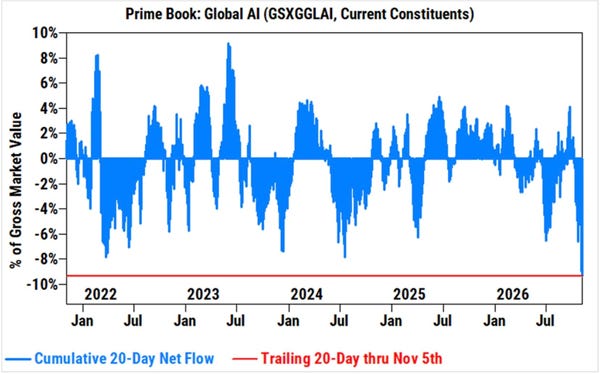
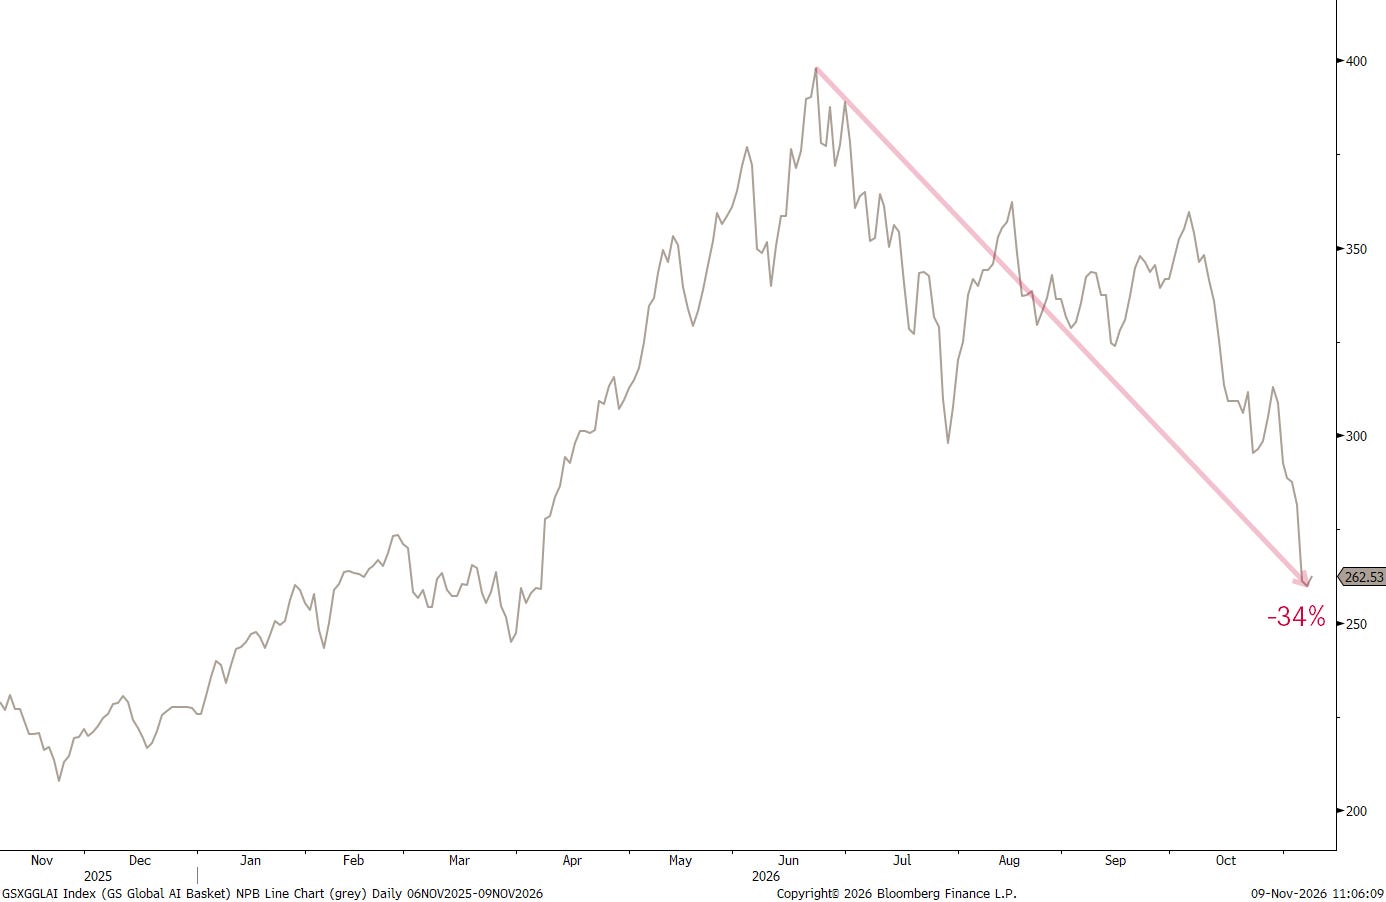
Whilst this Global AI basket shown above spans US, EMEA, and APAC listed companies deploying or enabling AI across software, semis, hardware, power/datacenter infrastructure, and IT services, was down over 11% last week, it actually topped out in June and is down 34% since its all-time high five months ago:
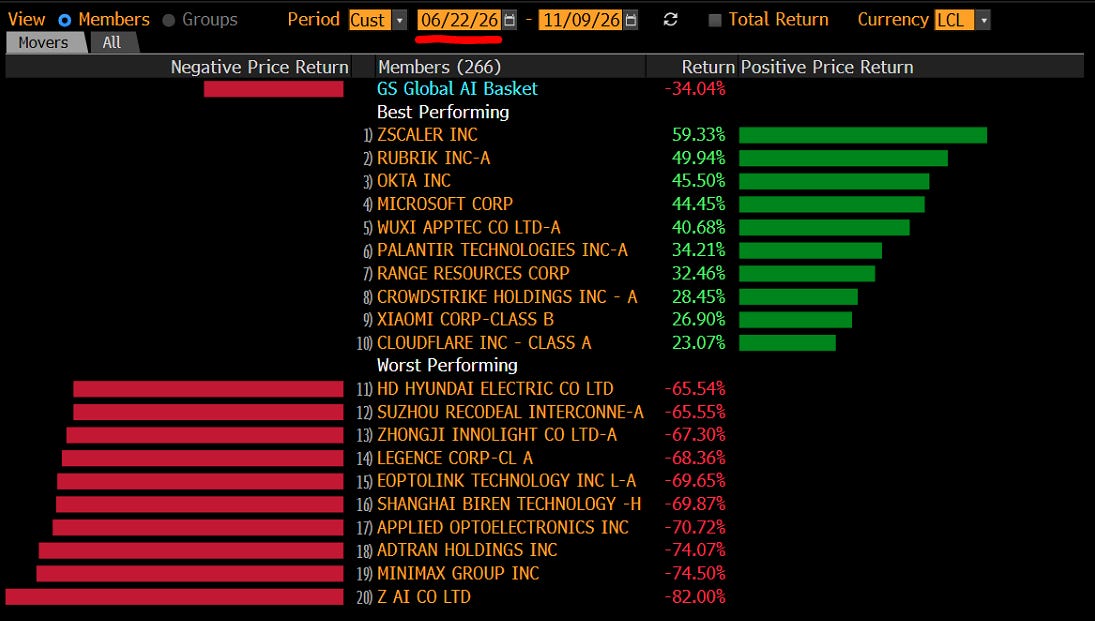
Whilst some of this index’s constituents are still up nicely since that June top, nearly 90% are down, and some of them massively:
‘Finally’, this has also started to impact the broader market, with the S&P 500 taking out two key supports with one big, fat, ugly red candle last Thursday:
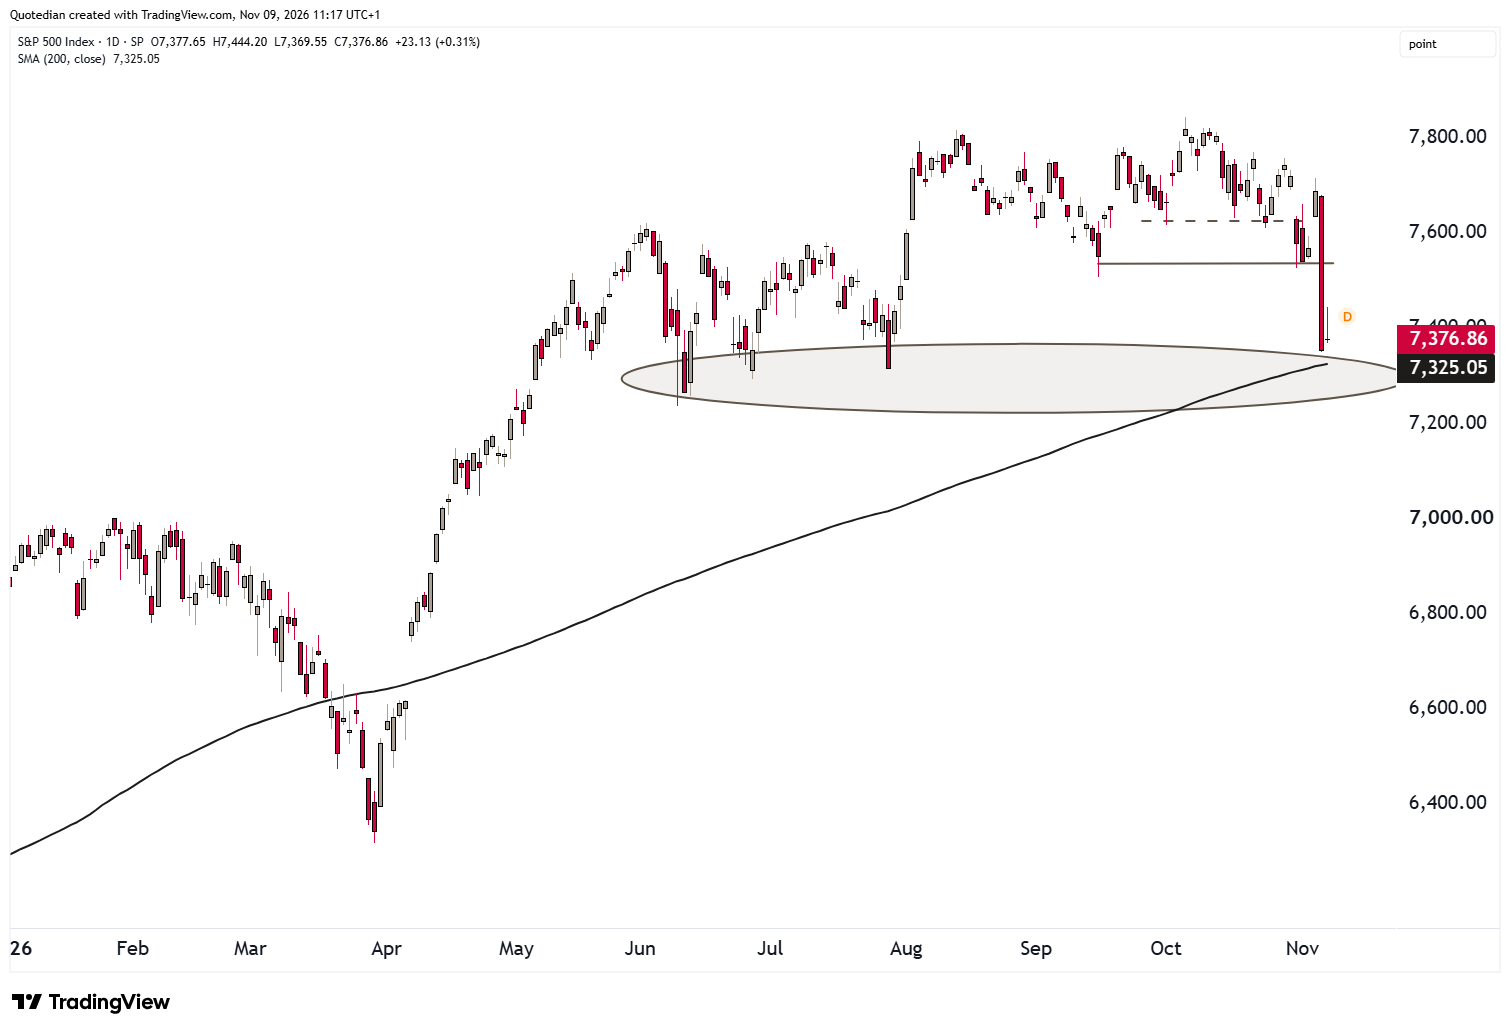
The index now stands at another, probably even more important key support zone, made up of the June and August lows, plus the 200-day moving average (MA).
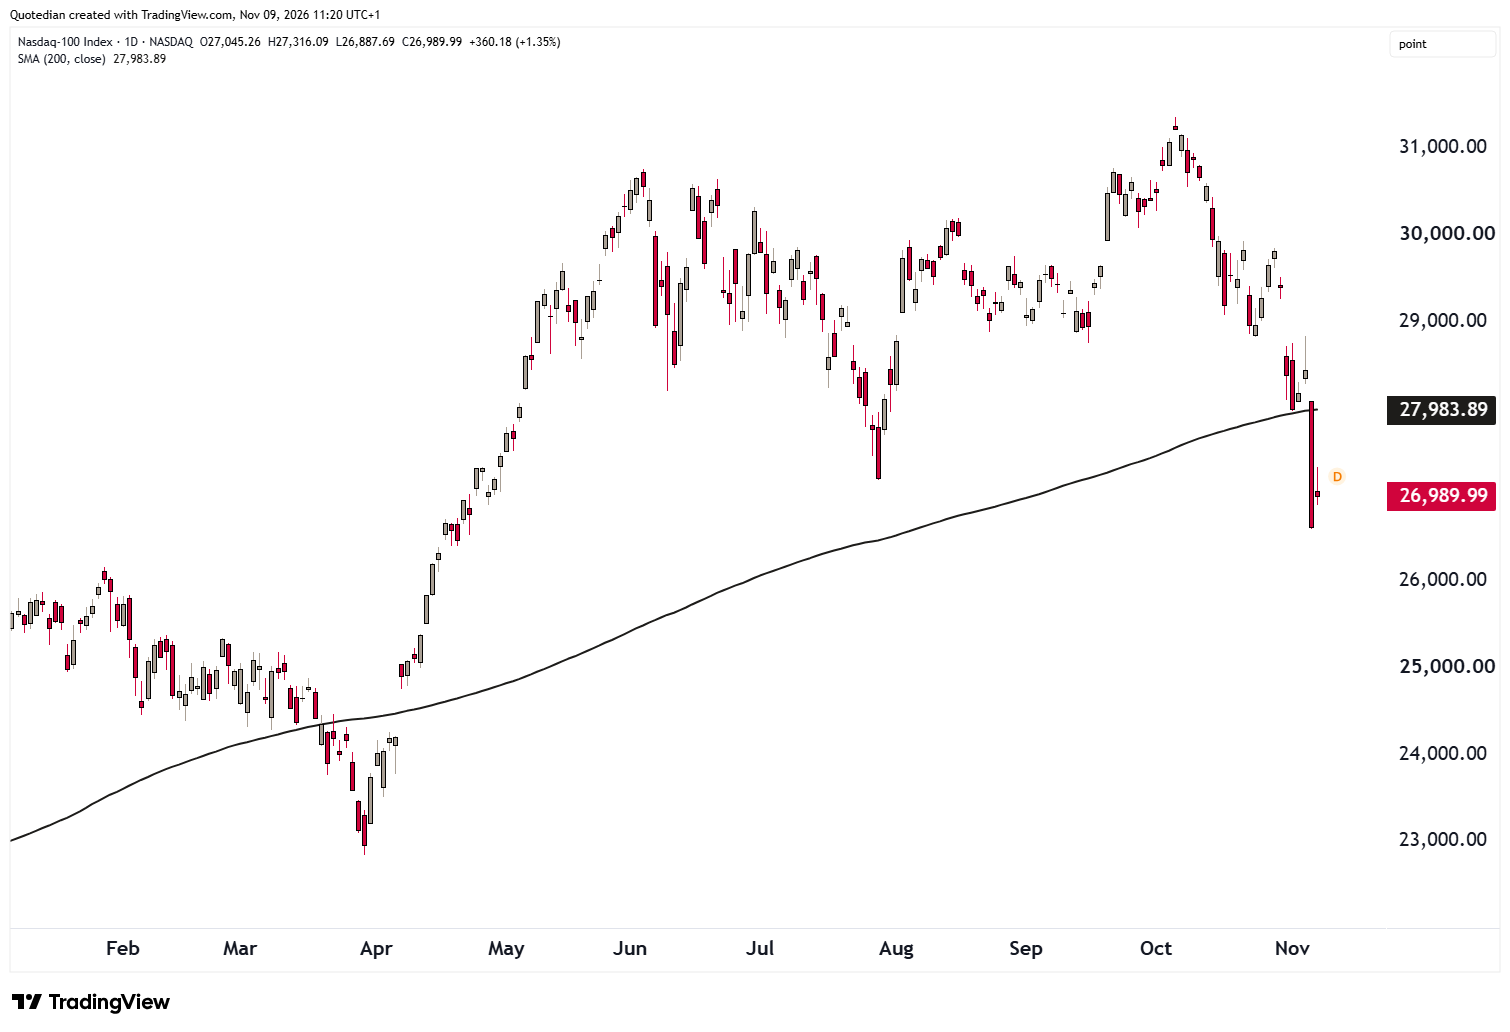
The more tech-stocks heavy Nasdaq-100 cut through that support like a hot knife through butter, and at -14% since its all-time high on October 6th is now in official correction territory:
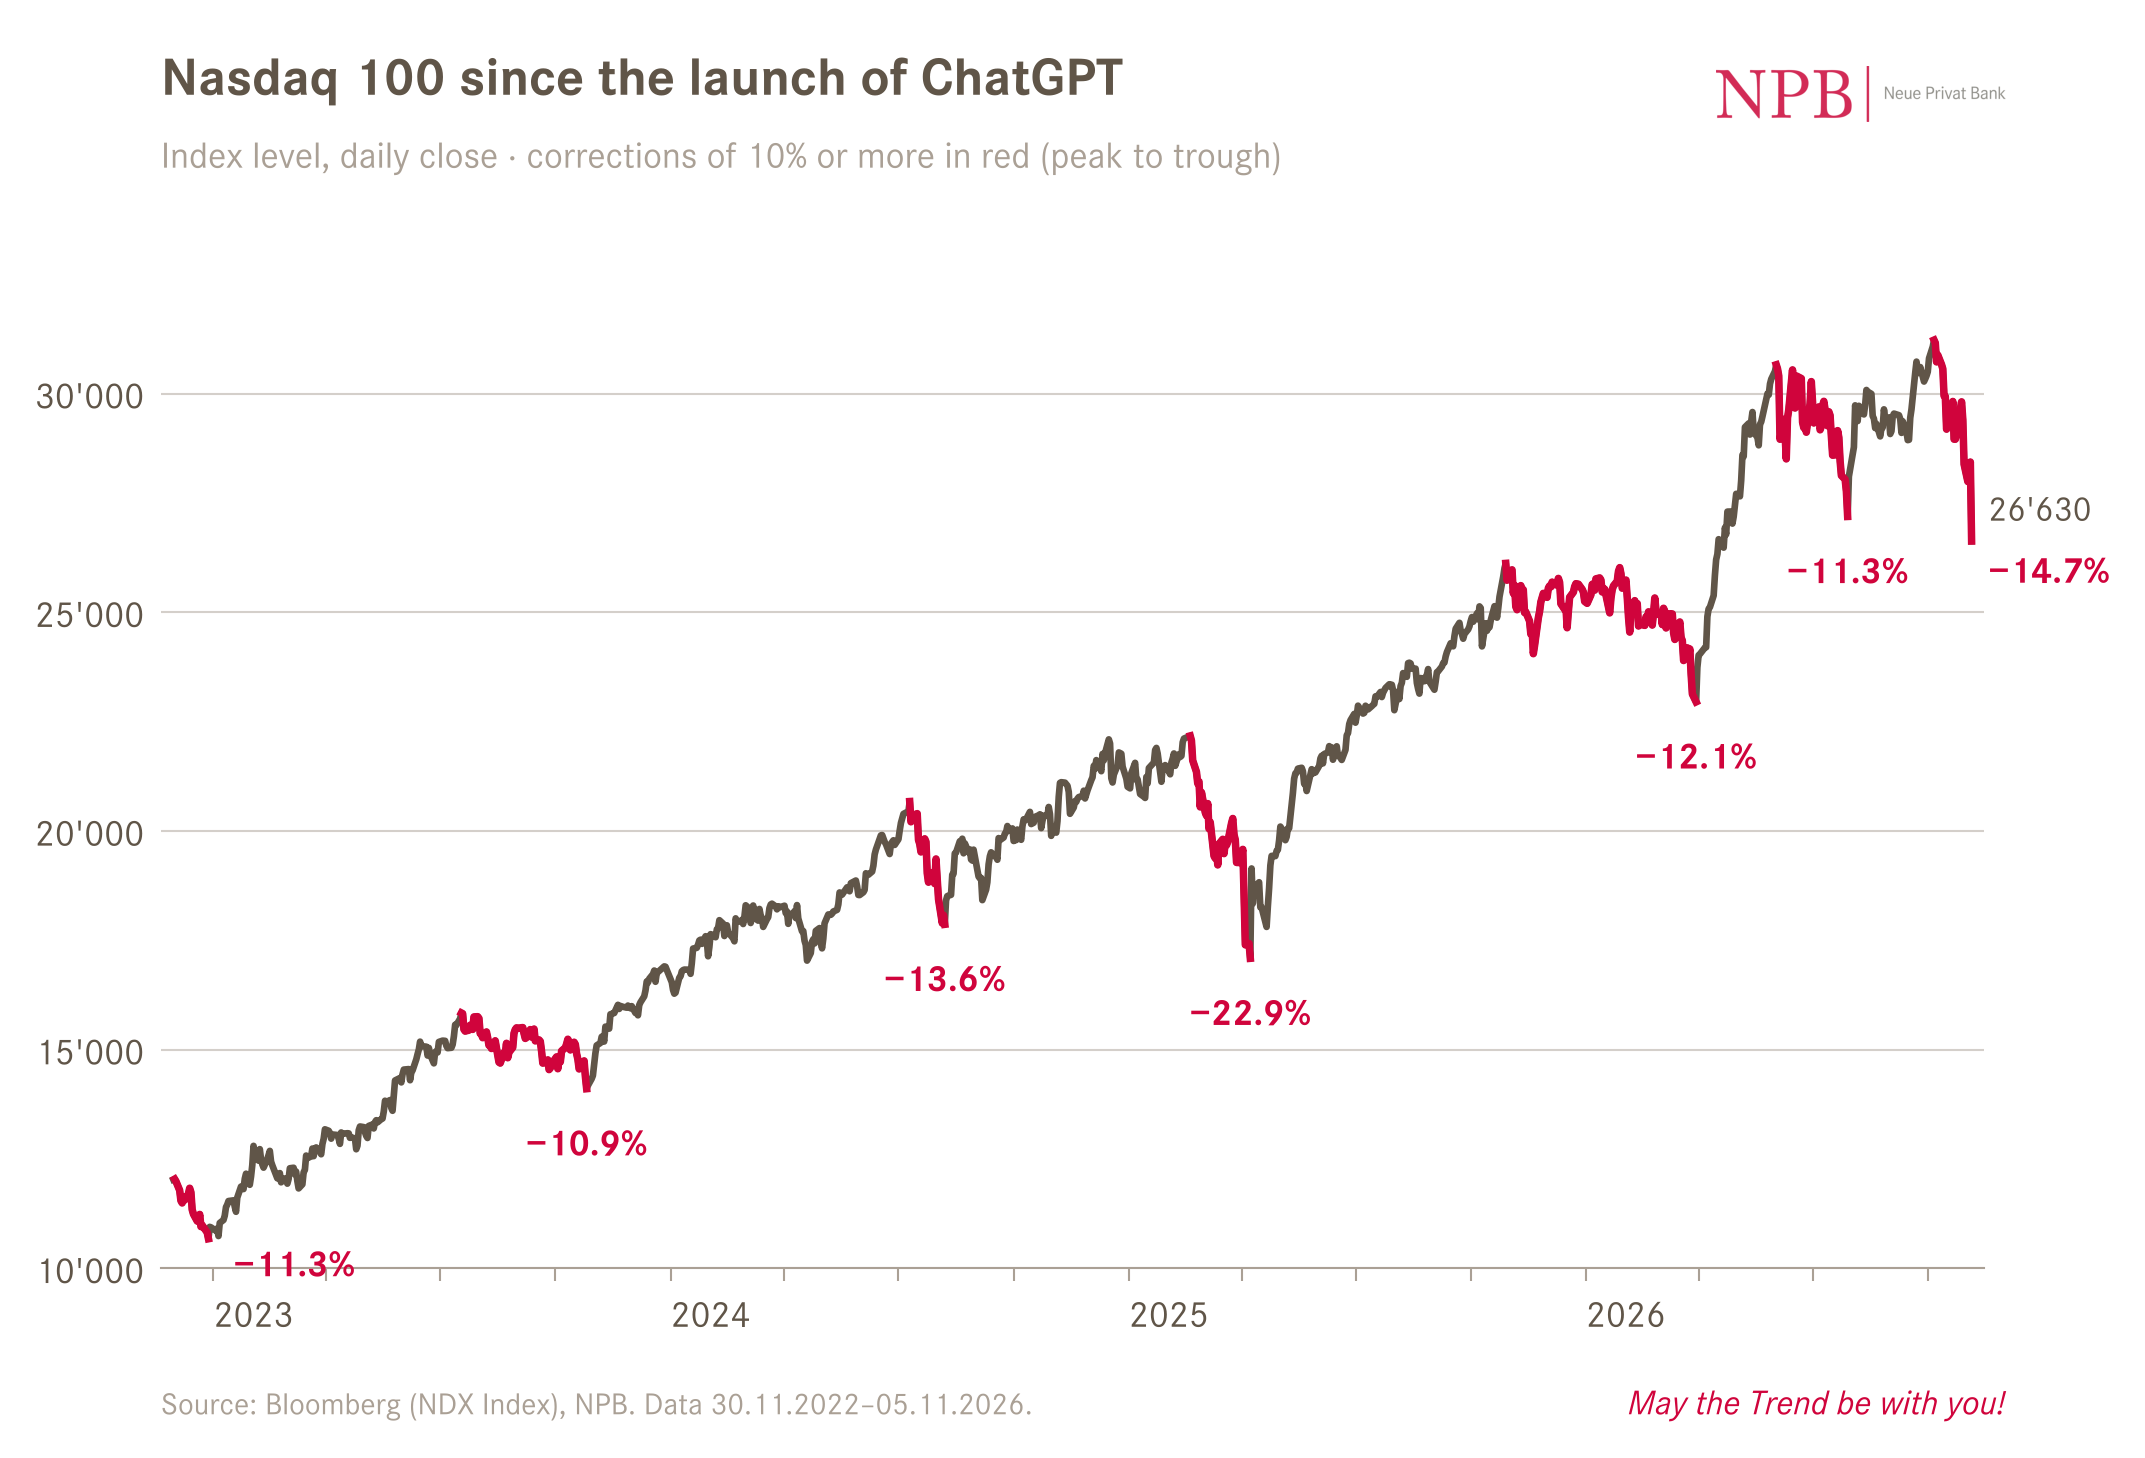
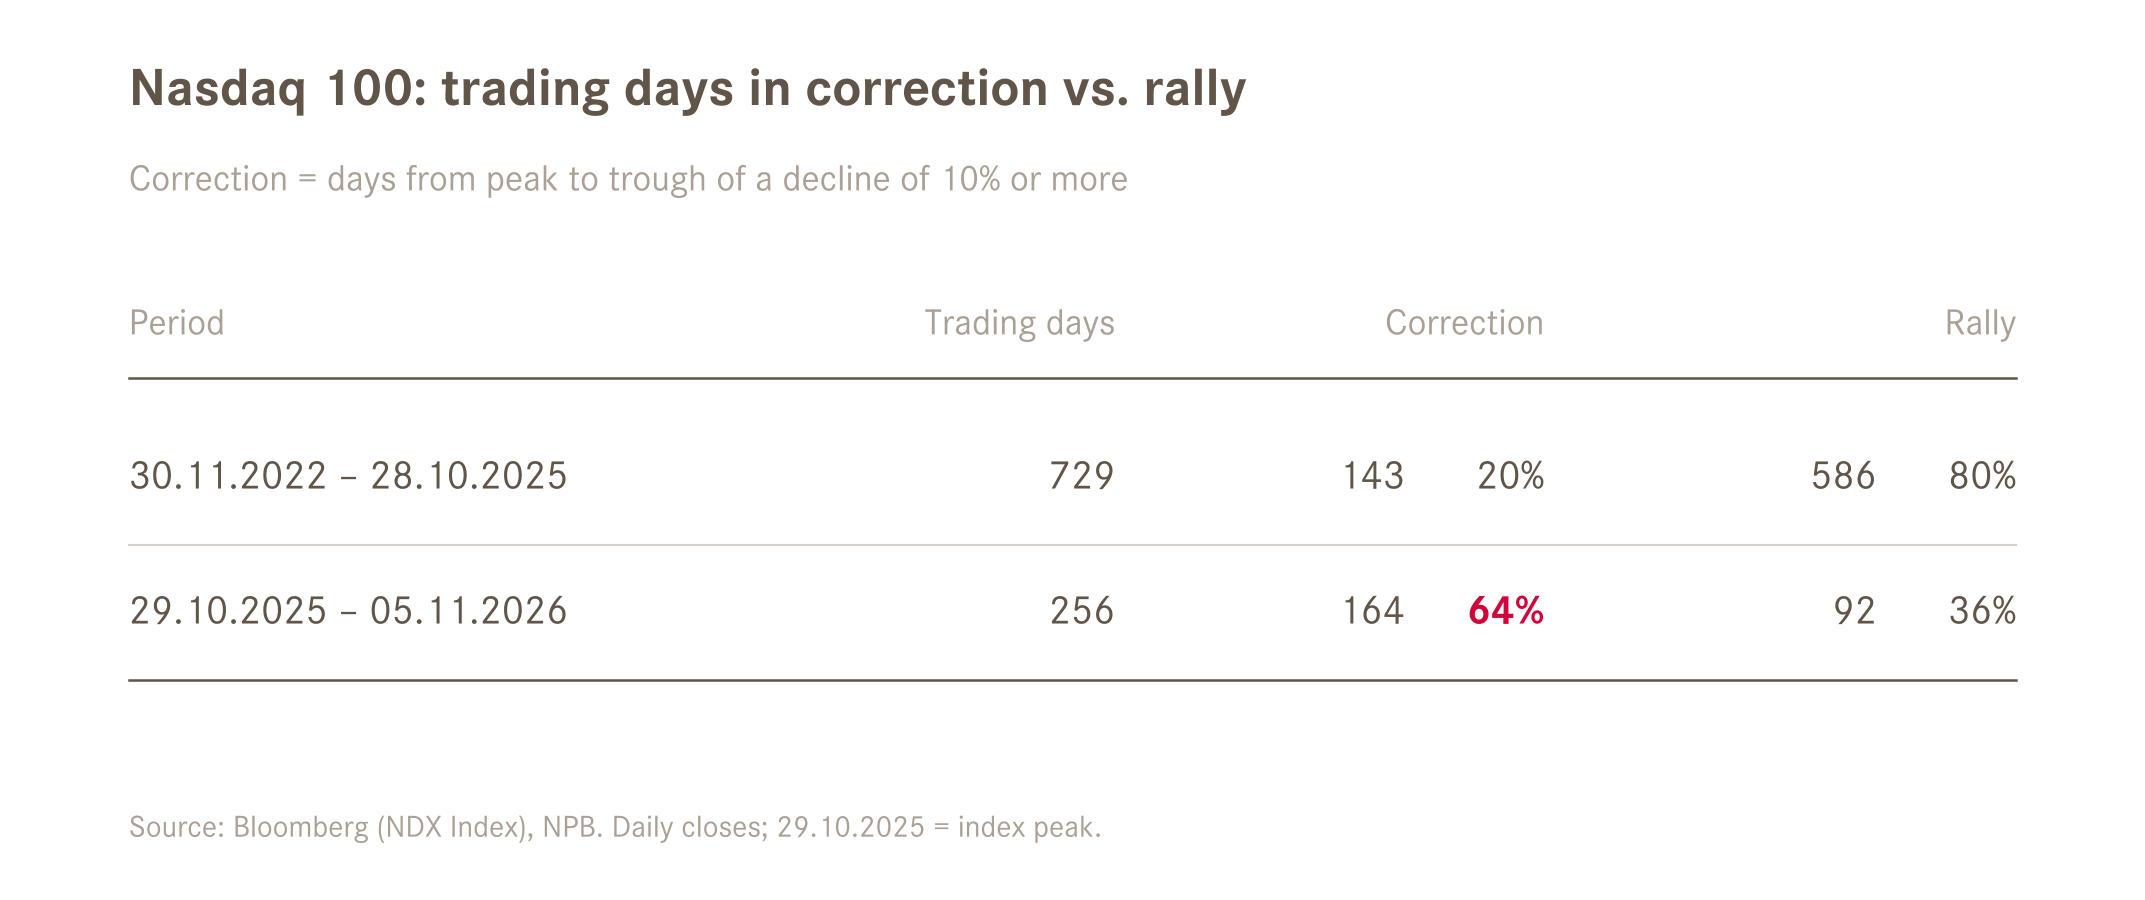
As a matter of fact, and as I showed in a LinkedIn post (click here) last Friday, the Nasdaq has spent more time in correction (red) than rally (grey) mode over the past 12 months:
The Philadelphia Semiconductor Index, better known as the SOX and below proxied via the iShares Semiconductor ETF (SOXX) , was down 12% on Thursday and is down nearly 40% from its June highs:
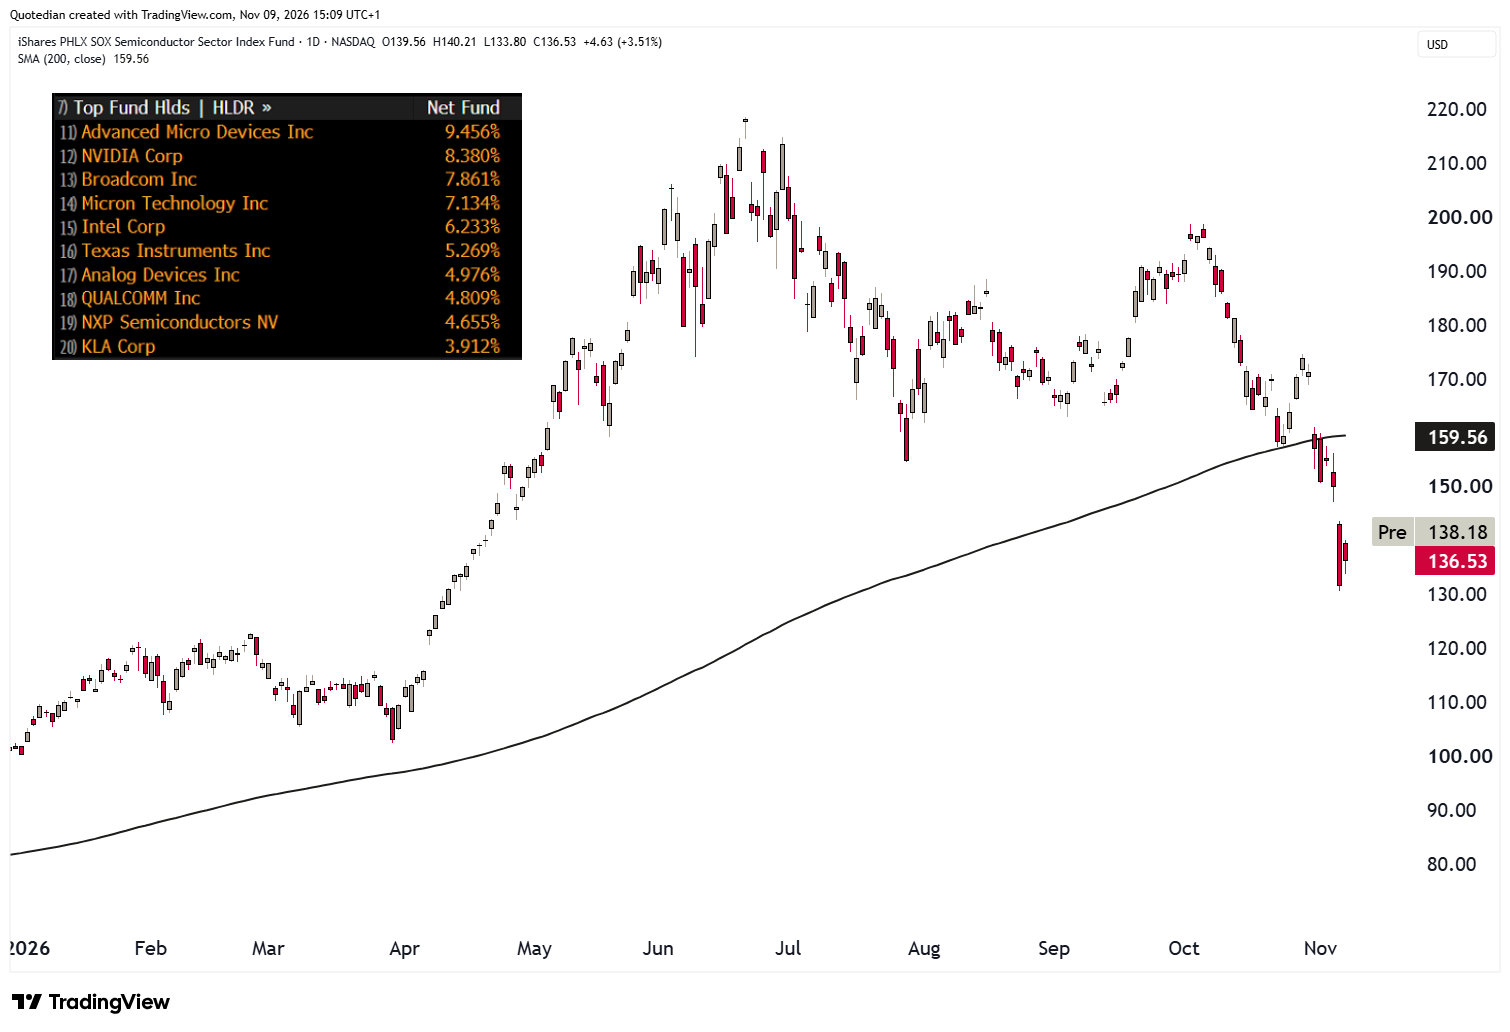
Despite being strongly oversold (RSI <30) I would be careful in trying to catch that falling knife, not least due some possible fall-out from the Chinese Spy story at Nvidia …



But back to our Grand Theft Algo title for a moment.
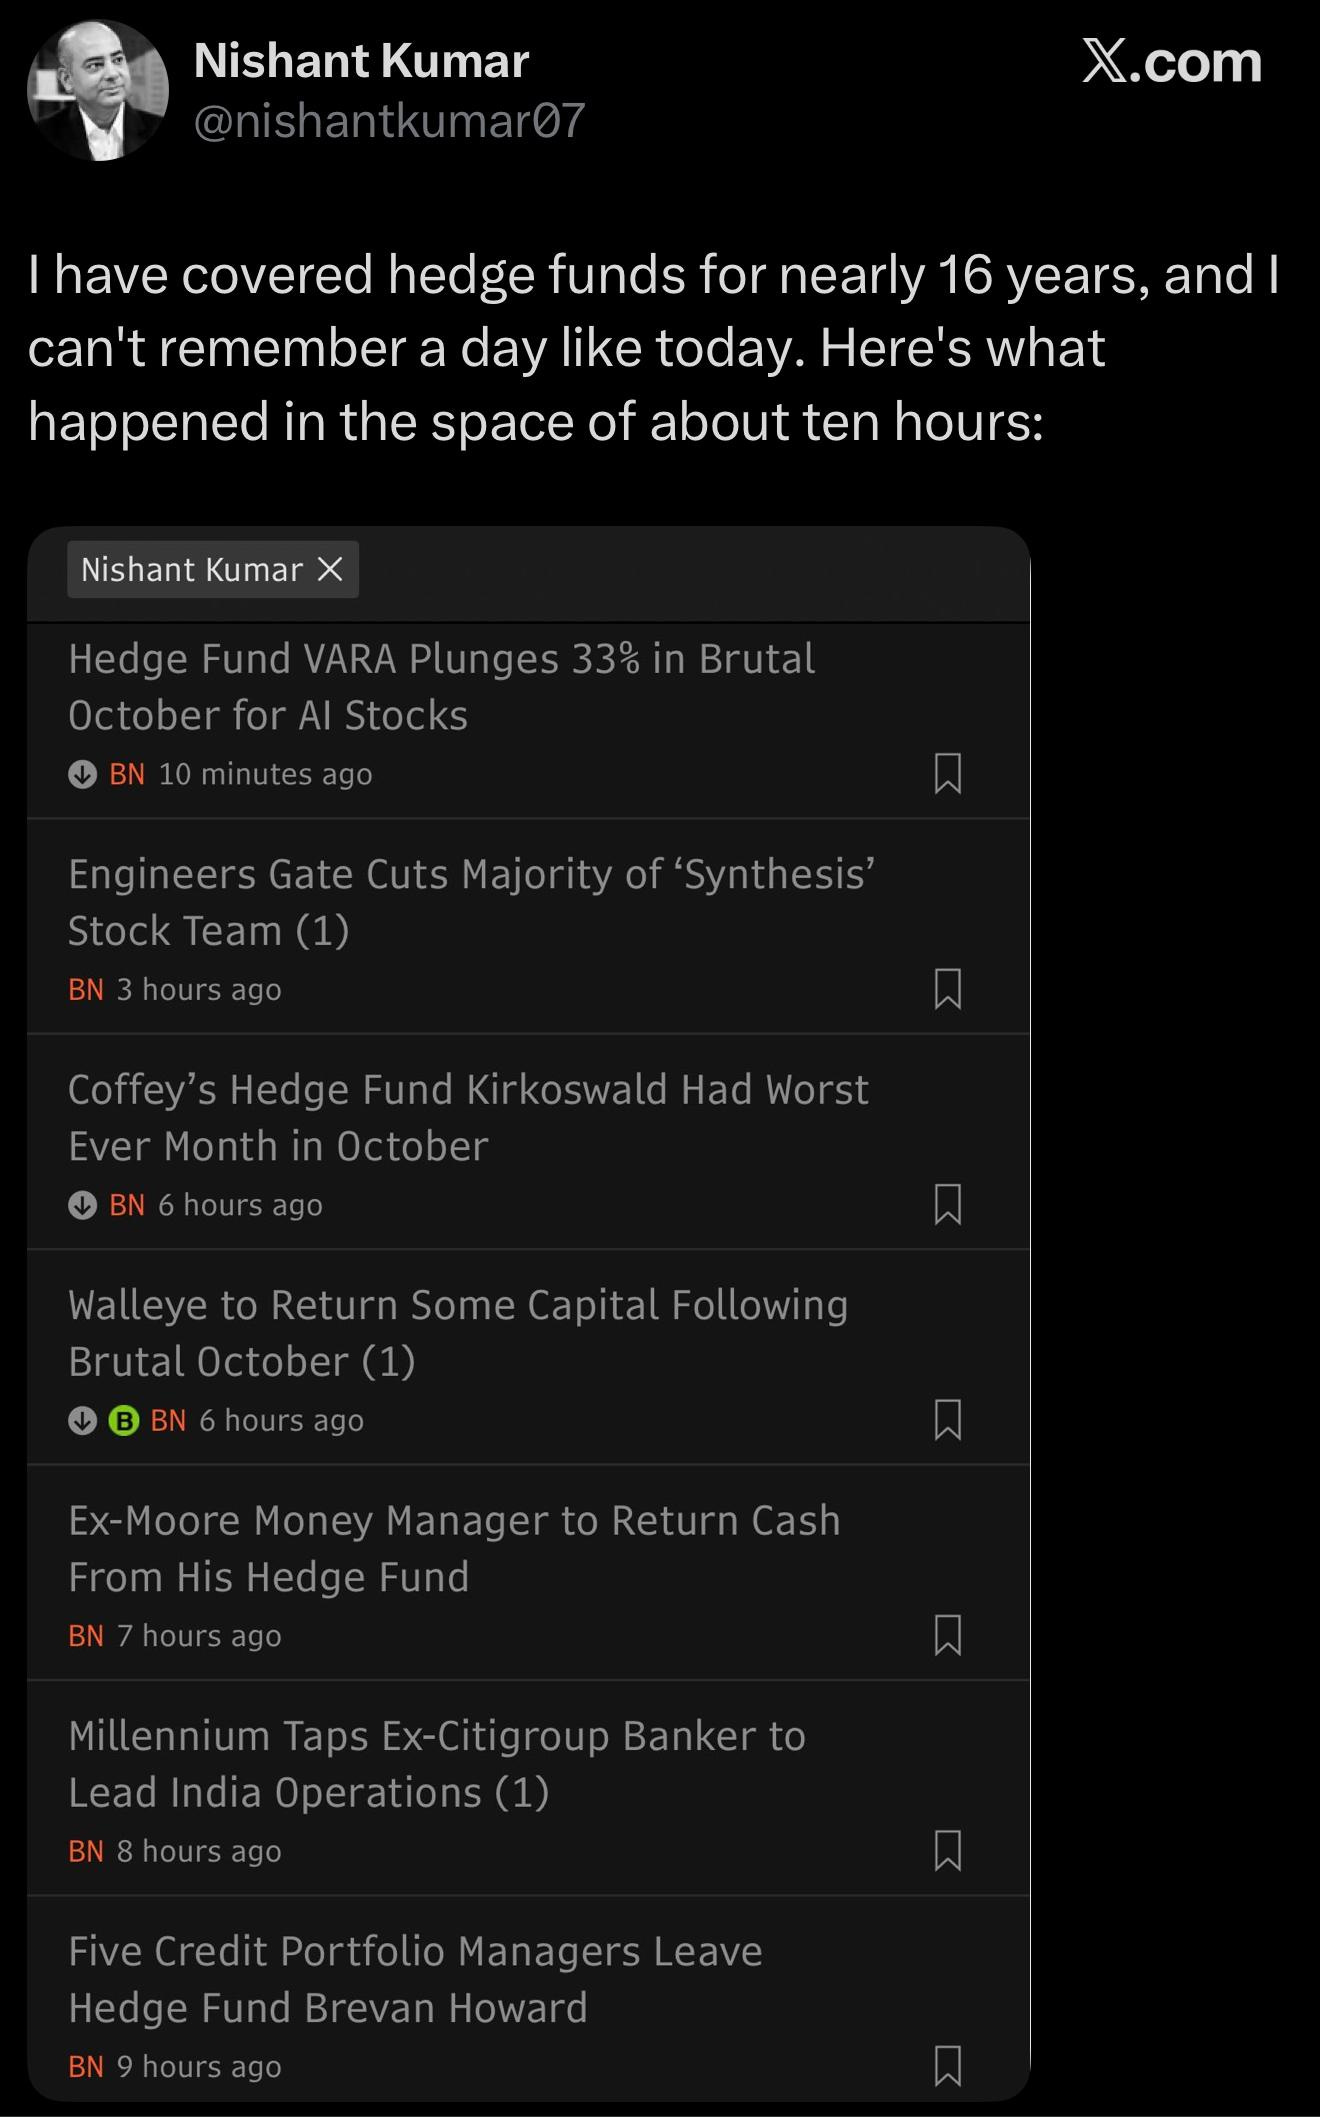
Here’s what Nishant Kumar, hedge fund specialists at Bloomberg posted on X last Friday:
And here’s what Elliot Investment Management, an USD80 billion hedge fund, wrote to investors:

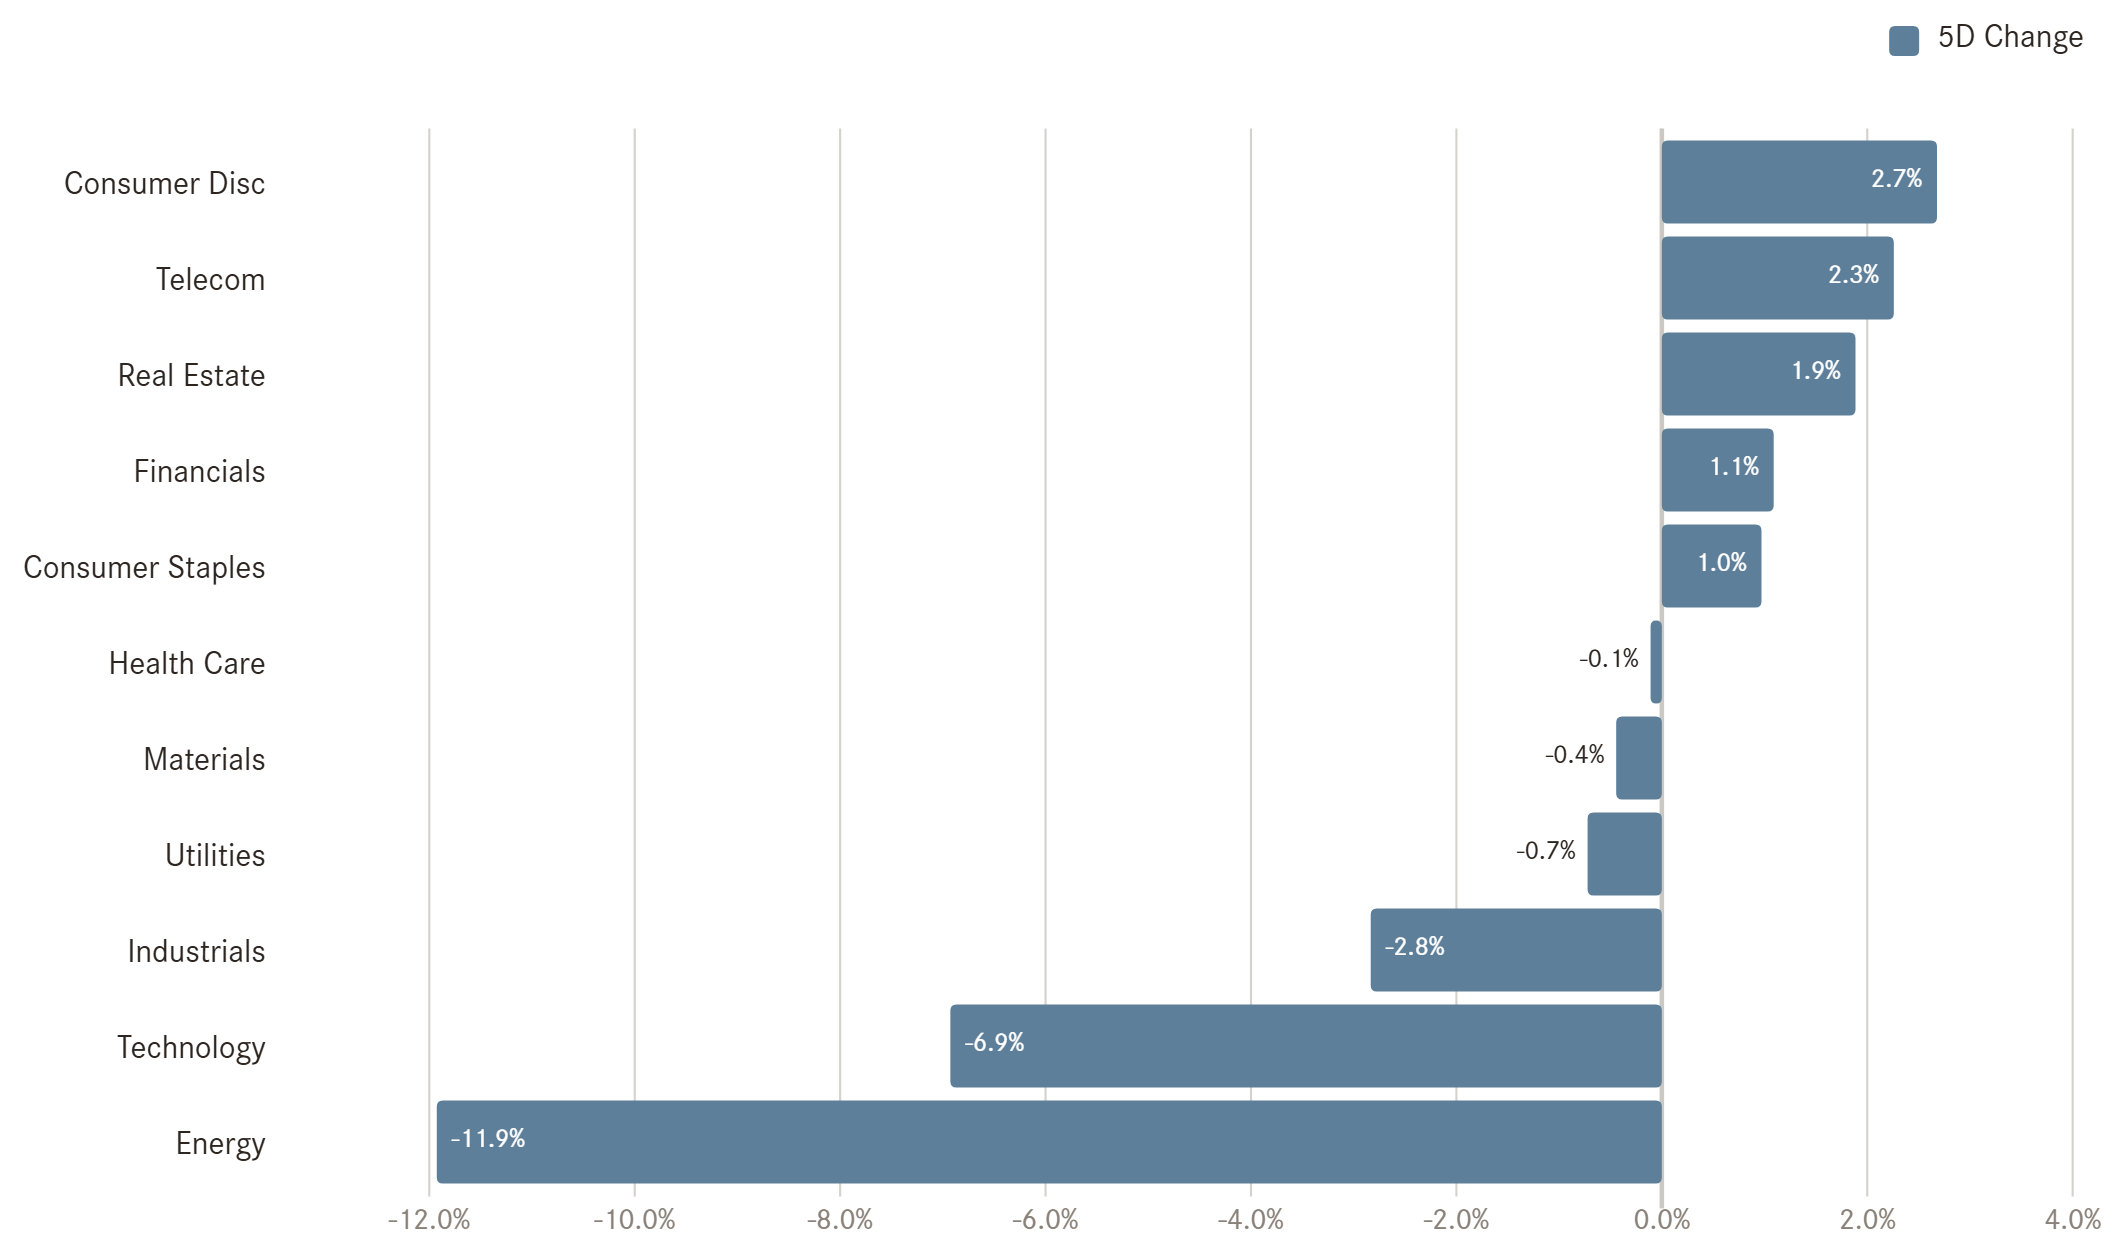
But luckily, and interestingly enough, investors have not been selling completely indiscriminately, but actually some green was to be had last week too:
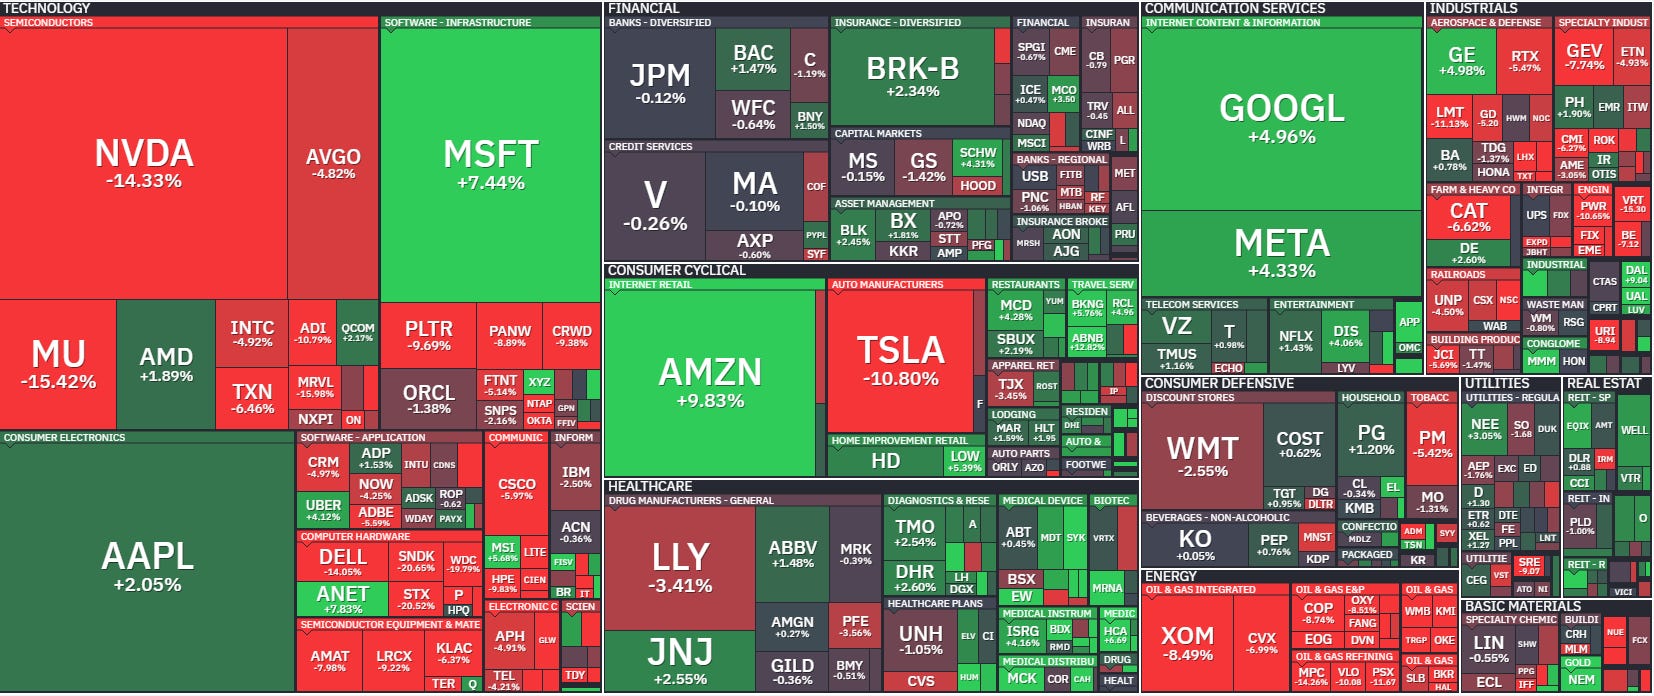
As a matter of fact, five sectors printed green (blue, you know what I mean) last week, and technology was NOT the worst sector:
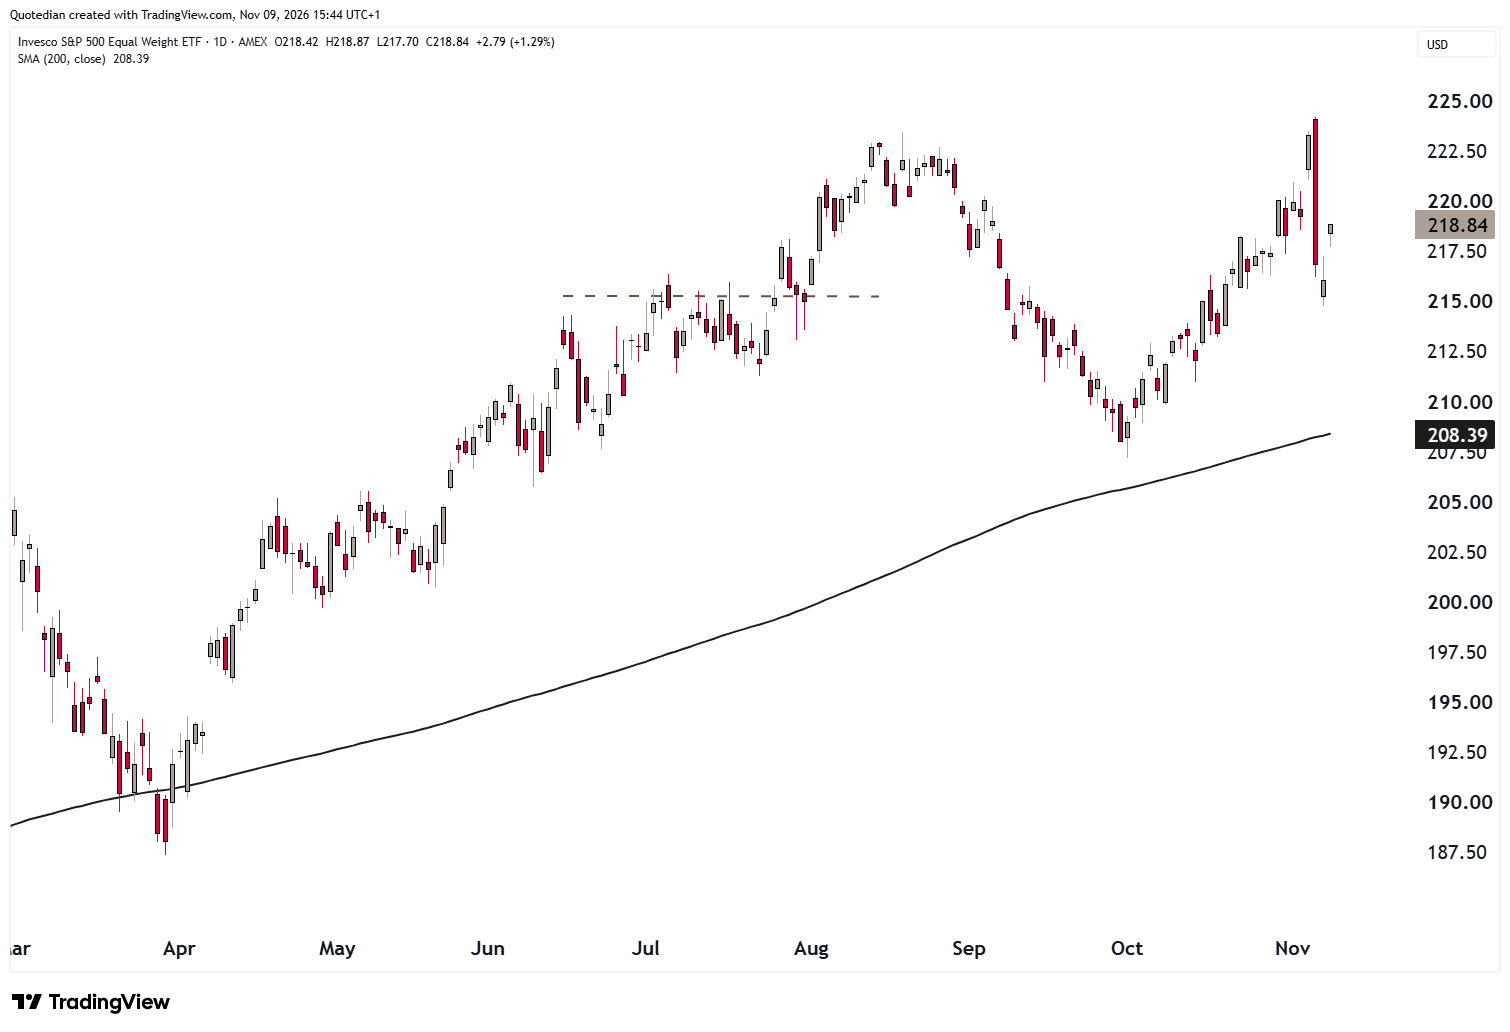
The equal-weight version of the S&P 500 (RSP) held up well until Thursday:
European stocks (SXXP) even managed to squeeze out a small gain last week:
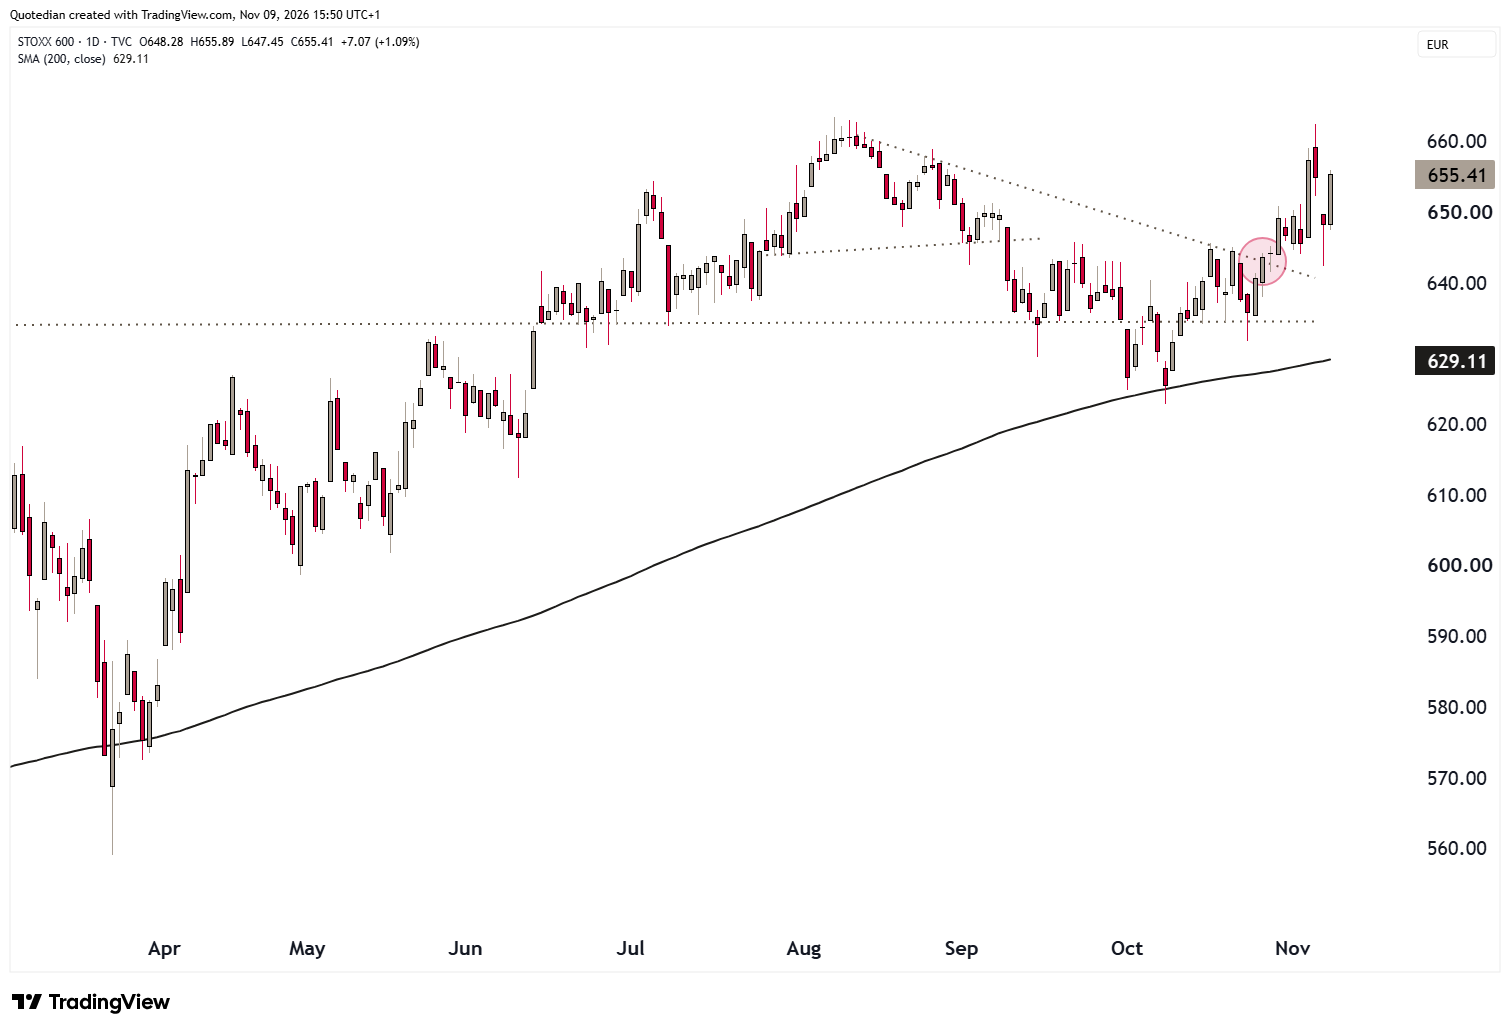
As of the time of typing this (Monday afternoon), the SXXP is up over 1% and less than one percent away from a new ATH!
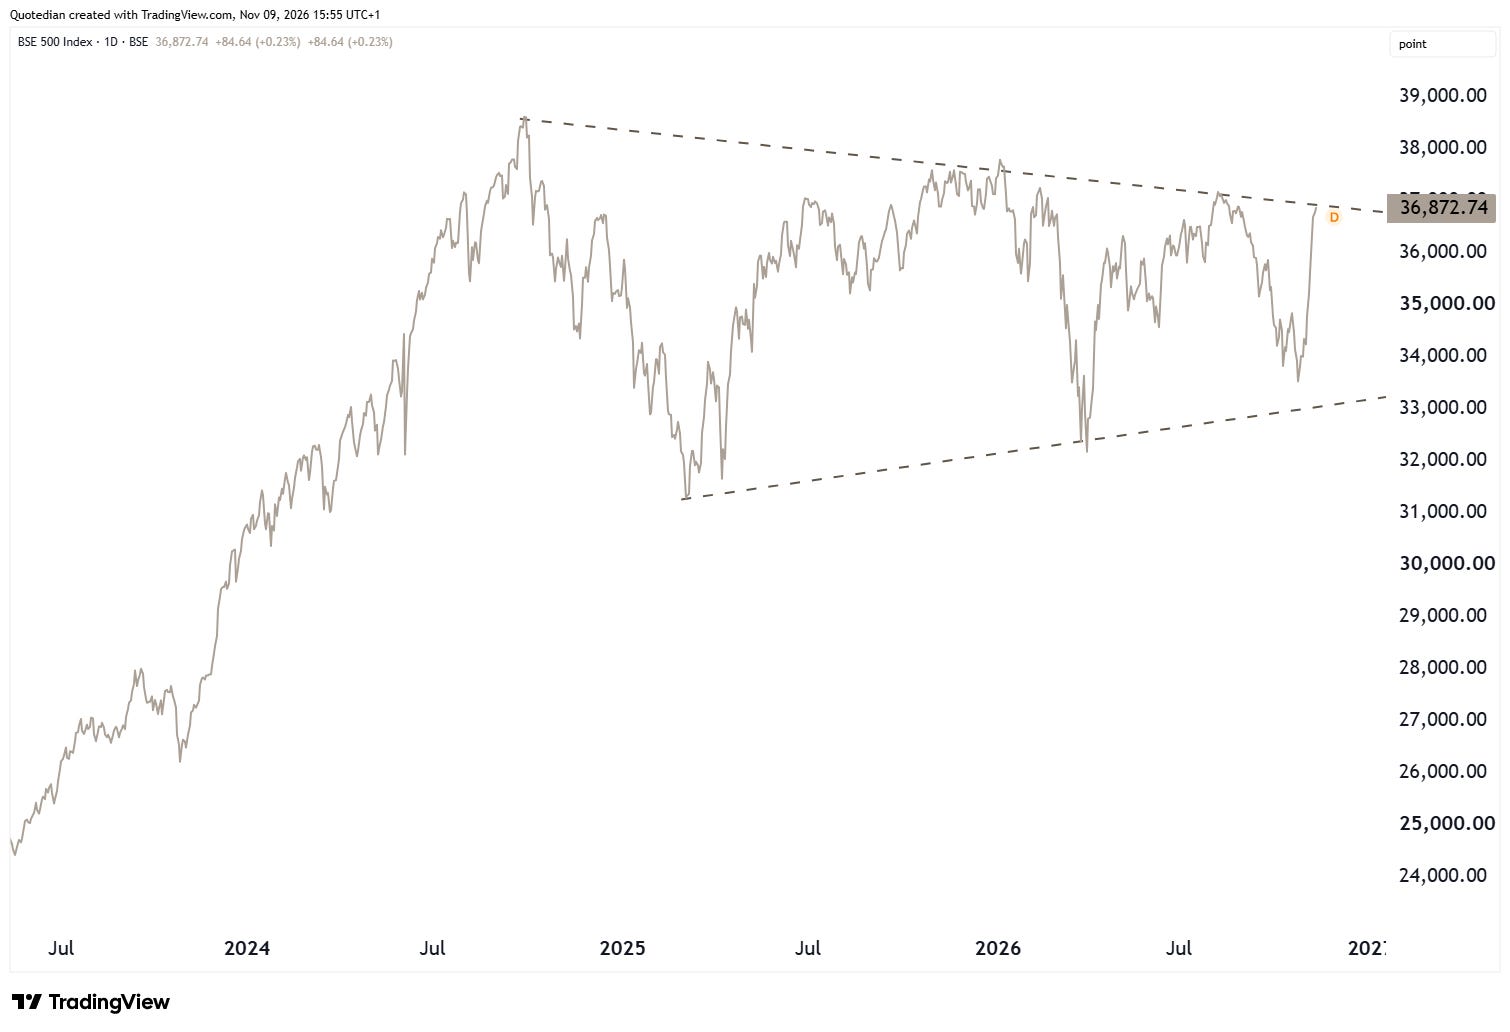
Interestingly enough, the Indian stock market (Nifty Index - grey below) seems to have become somewhat of the anti-AI trade (Roundhill AI ETF - red below):
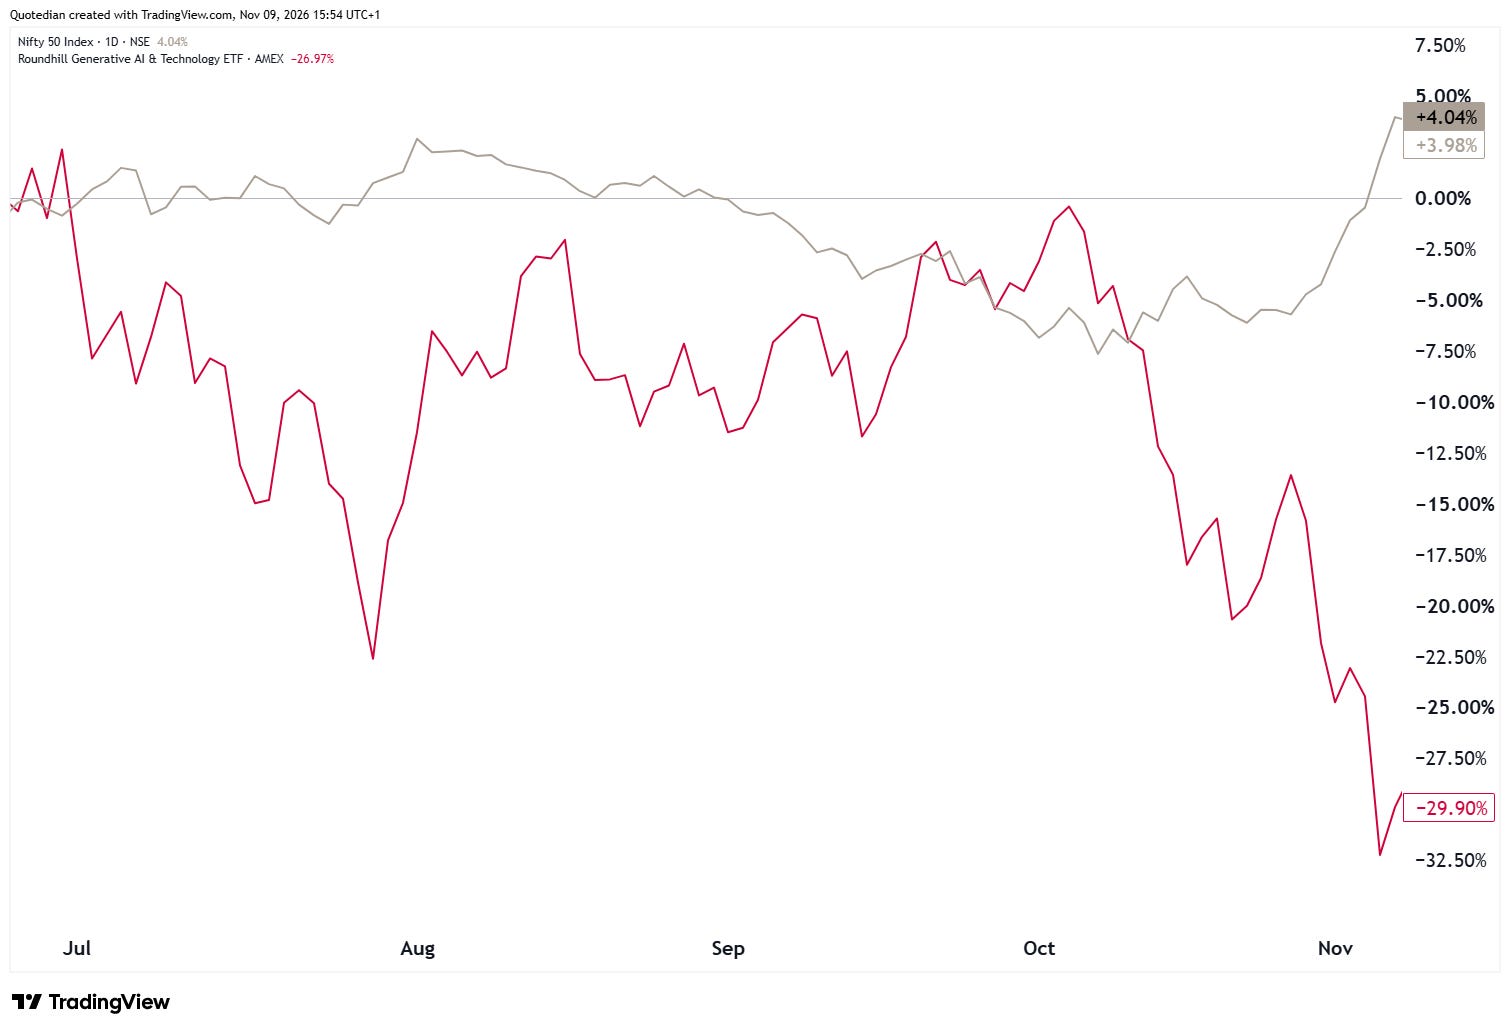
Hence, the last few days have been chick soup for the soul for India long investors, though some overhead resistance may lie ahead now:
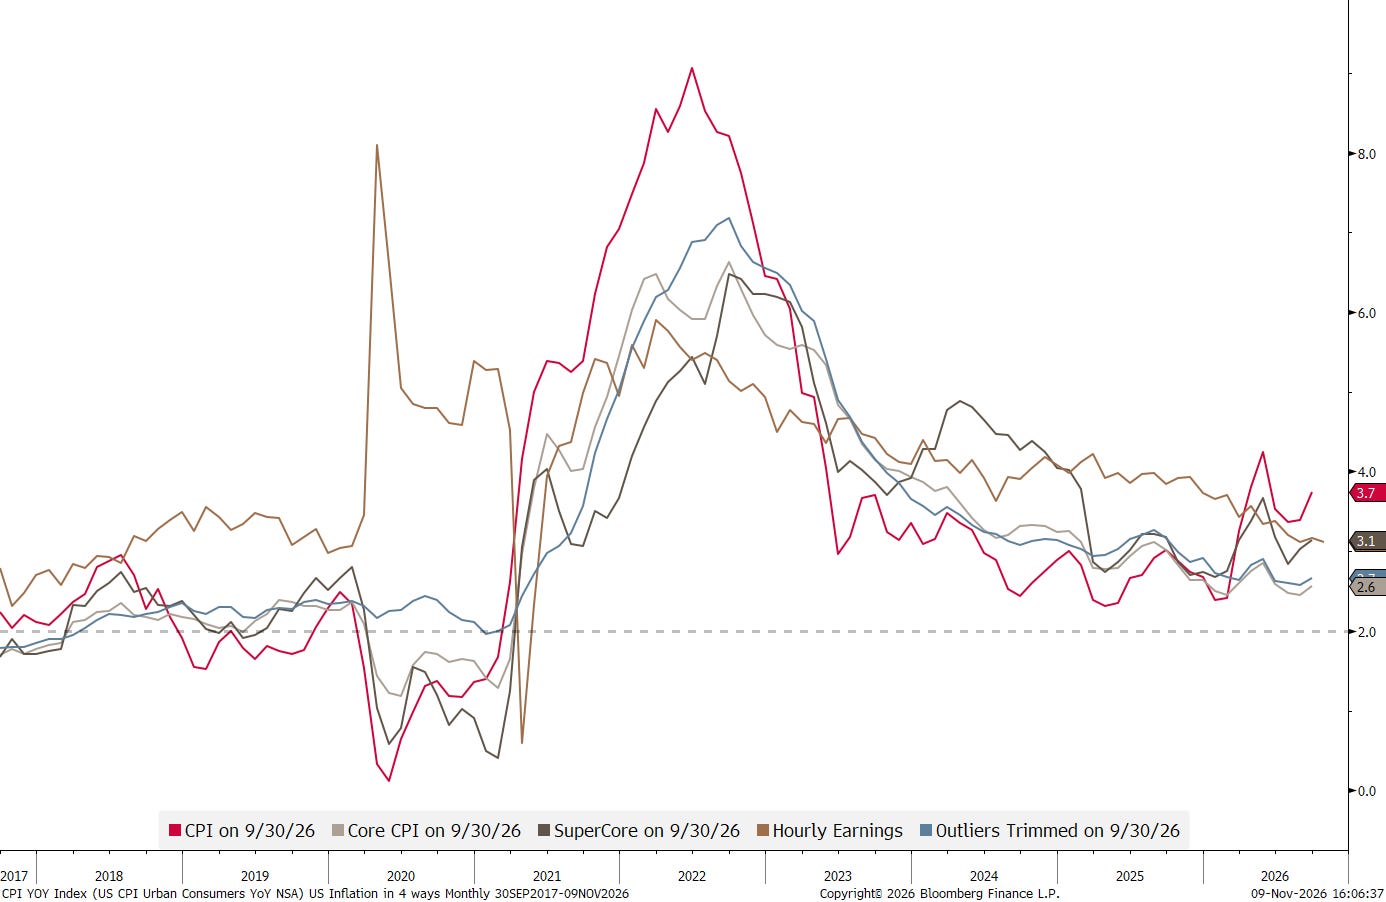
With all the excitement going on in tech stocks last week, one may be forgiven for having missed another very strong non-farm payroll report on Friday:

That was another clear beat and with inflation still way above the 2% target any way you slice it,
pressure on the Fed to hike again should be mounting:
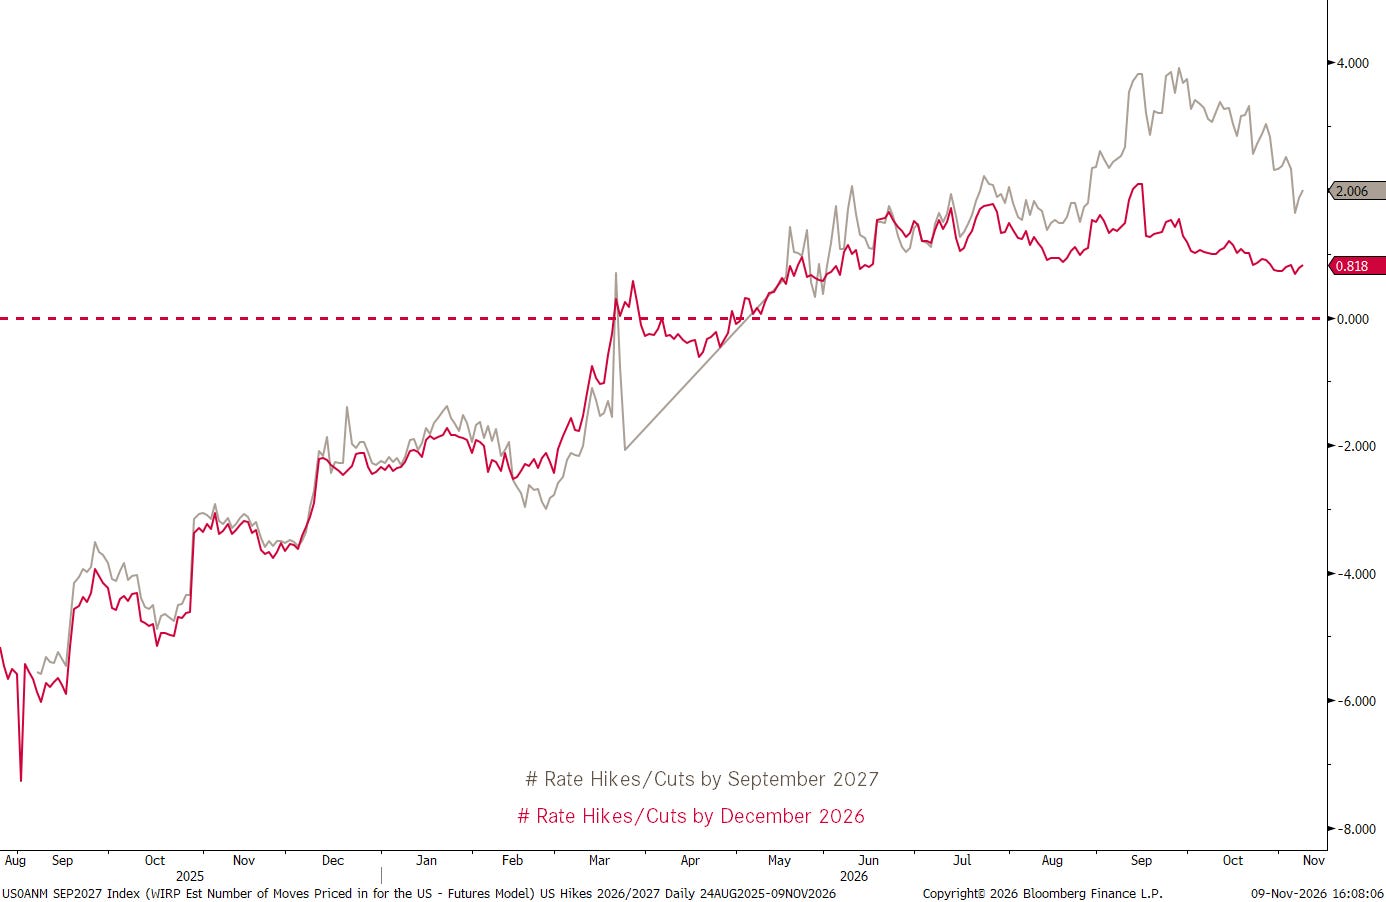
But it’s not.
Or at least it did not change to more on Friday.
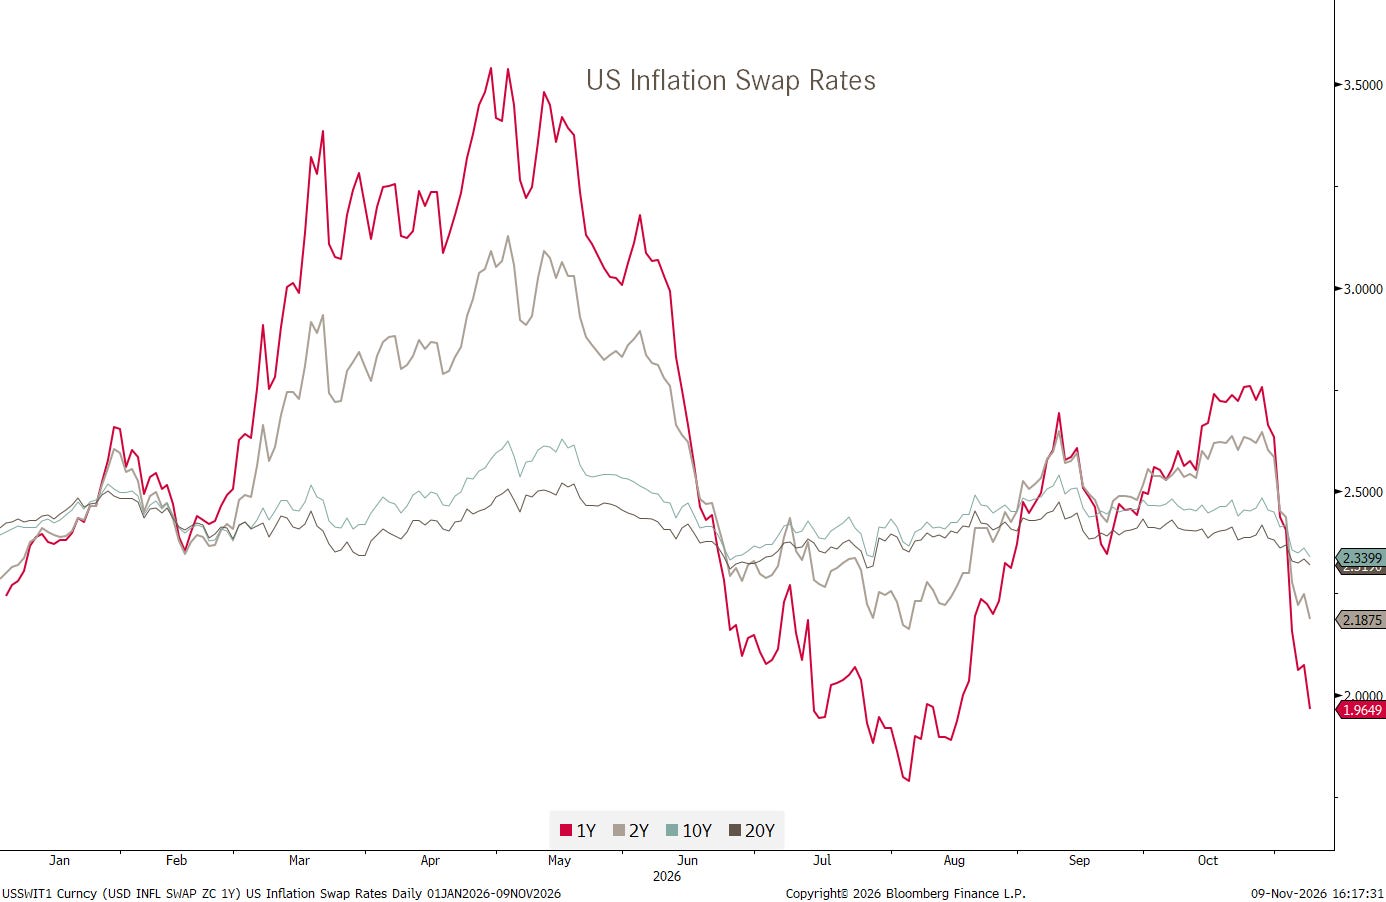
Maybe this is because the economy is going to tank now that all AI data centre projects will be immediatly stopped (sarcasm, yes).
Or … DC will now start fighting inflation given the election results (even more sarcasm, yes). But at least that is what swap rates started projecting shortly after the election:
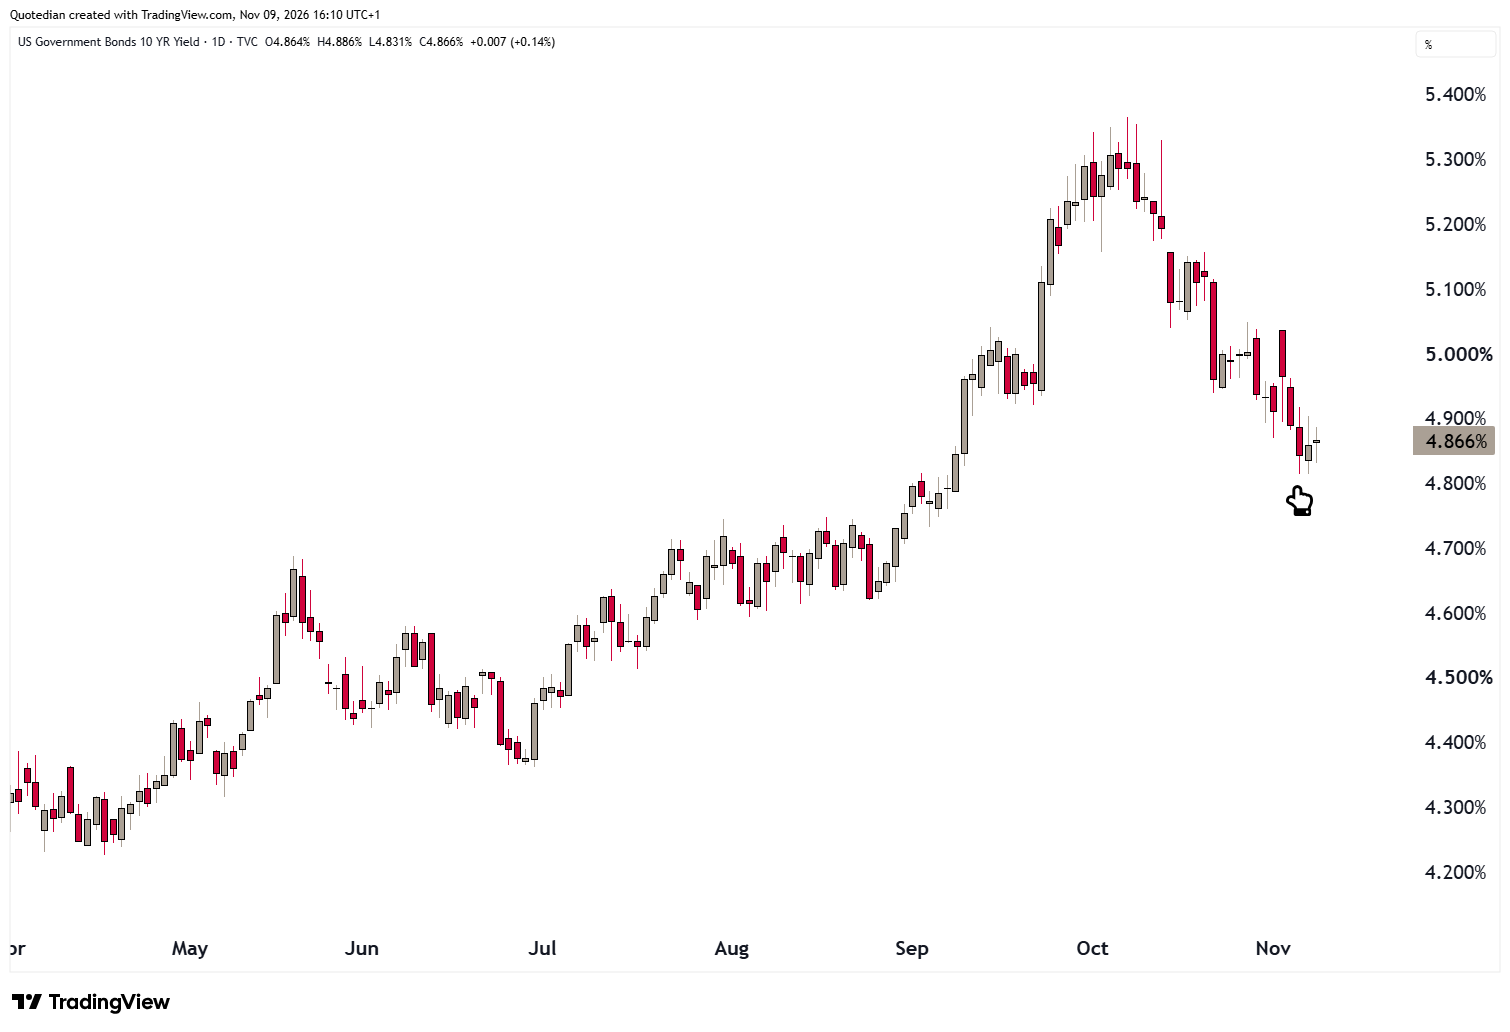
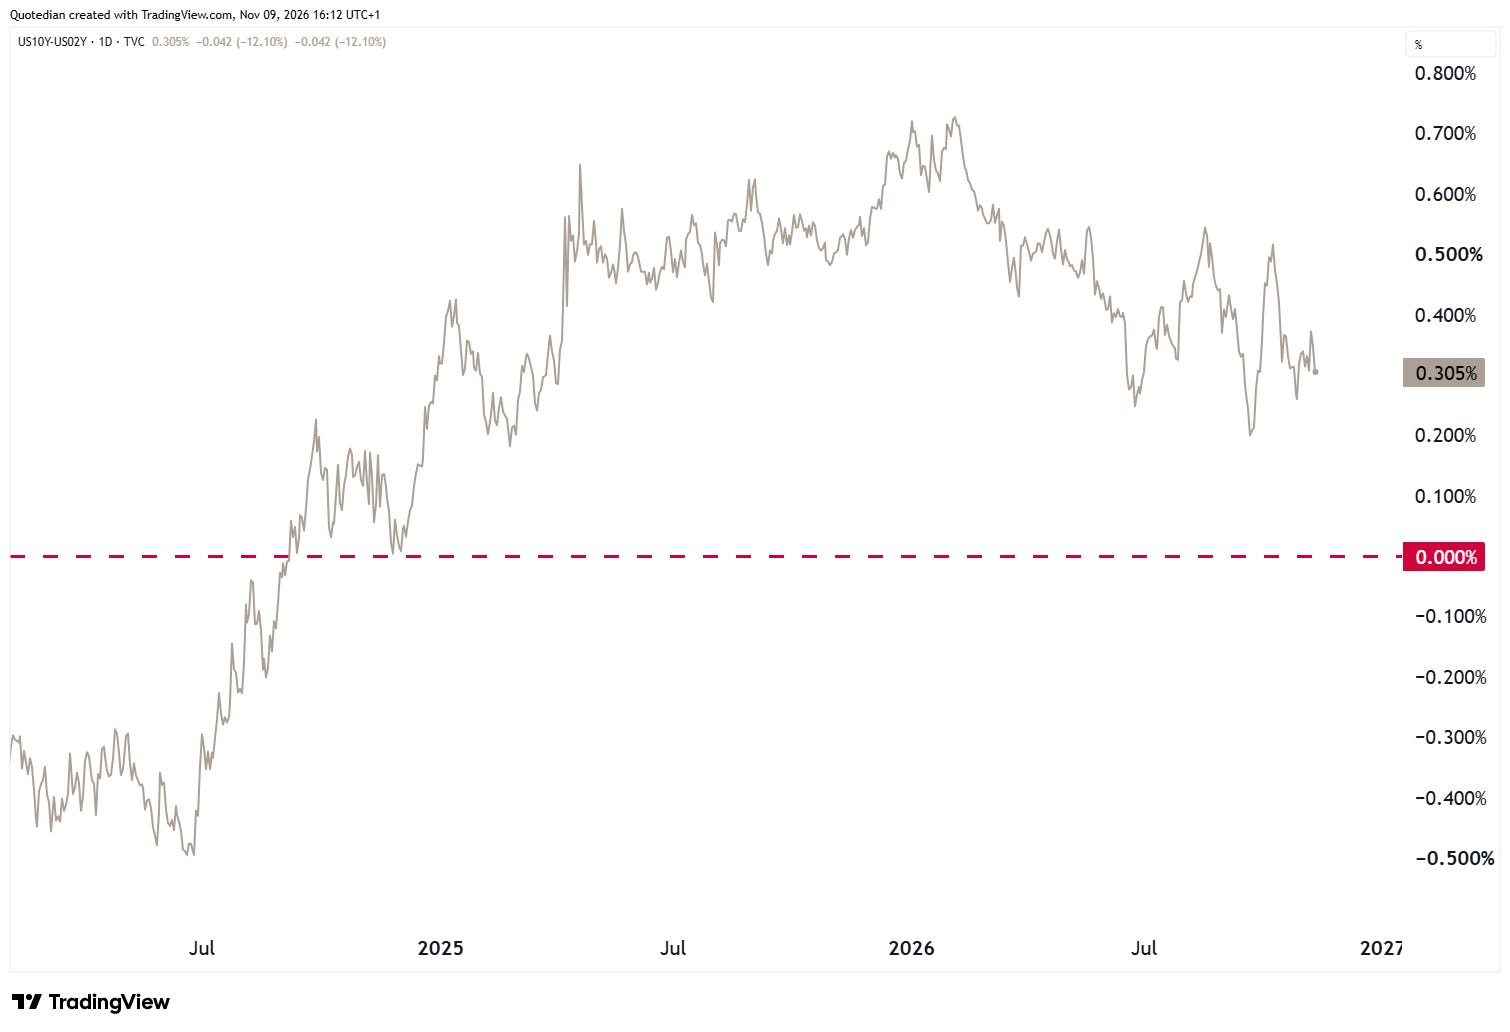
Treasury bonds rallied (yields sold off) somewhat during Tuesday’s equity sell-off, which is the normal “safe haven” knee-jerk trade one could expect,
the shape of the curve (10y-2y) did not change significantly:
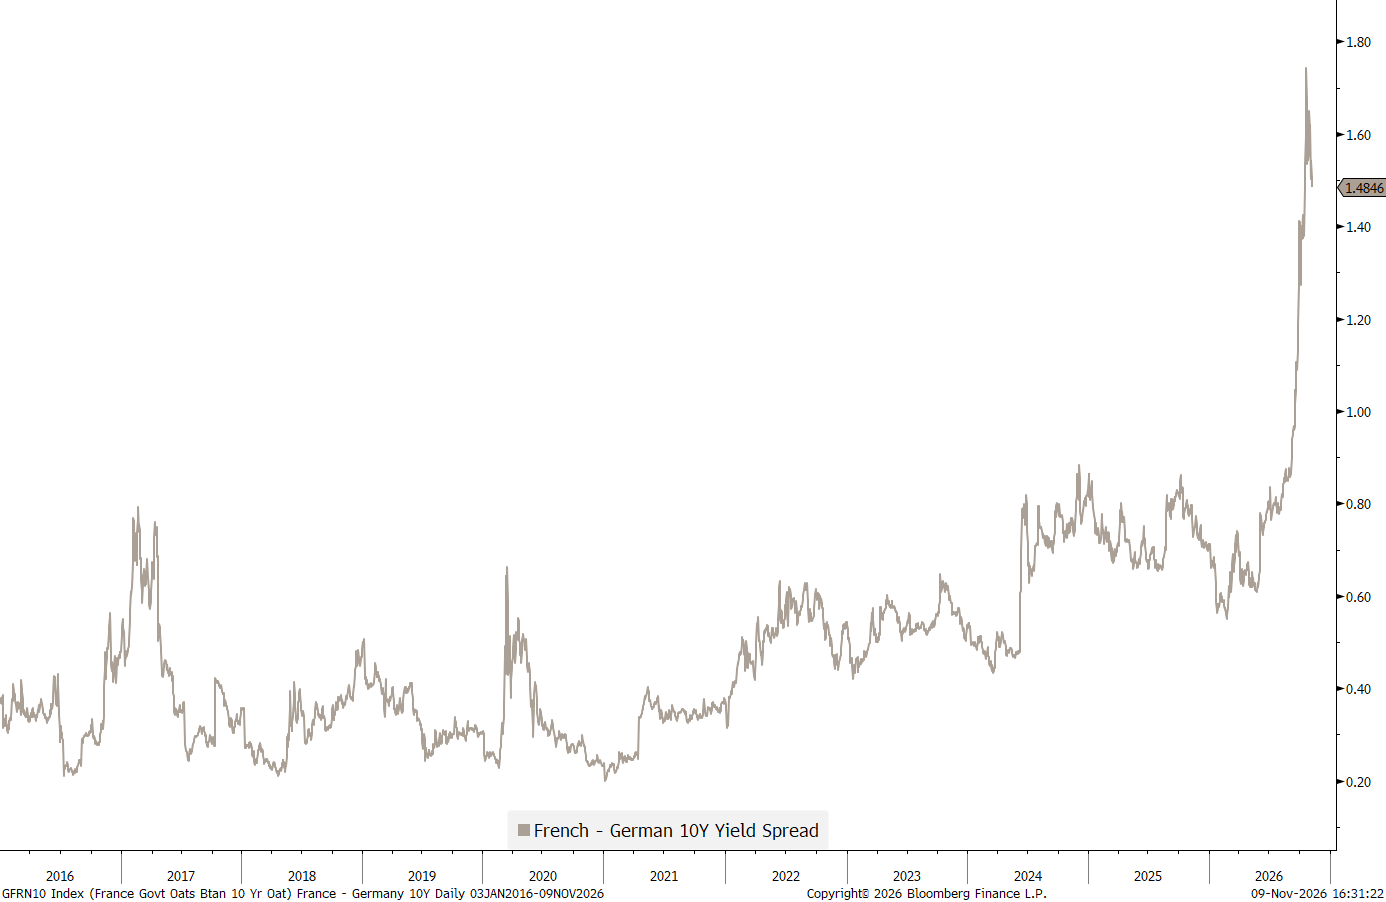
And again, you may be pardoned for having been distracted, but the French ‘issue’ is not quite off the table yet:
Is the worst already over for credit spreads?
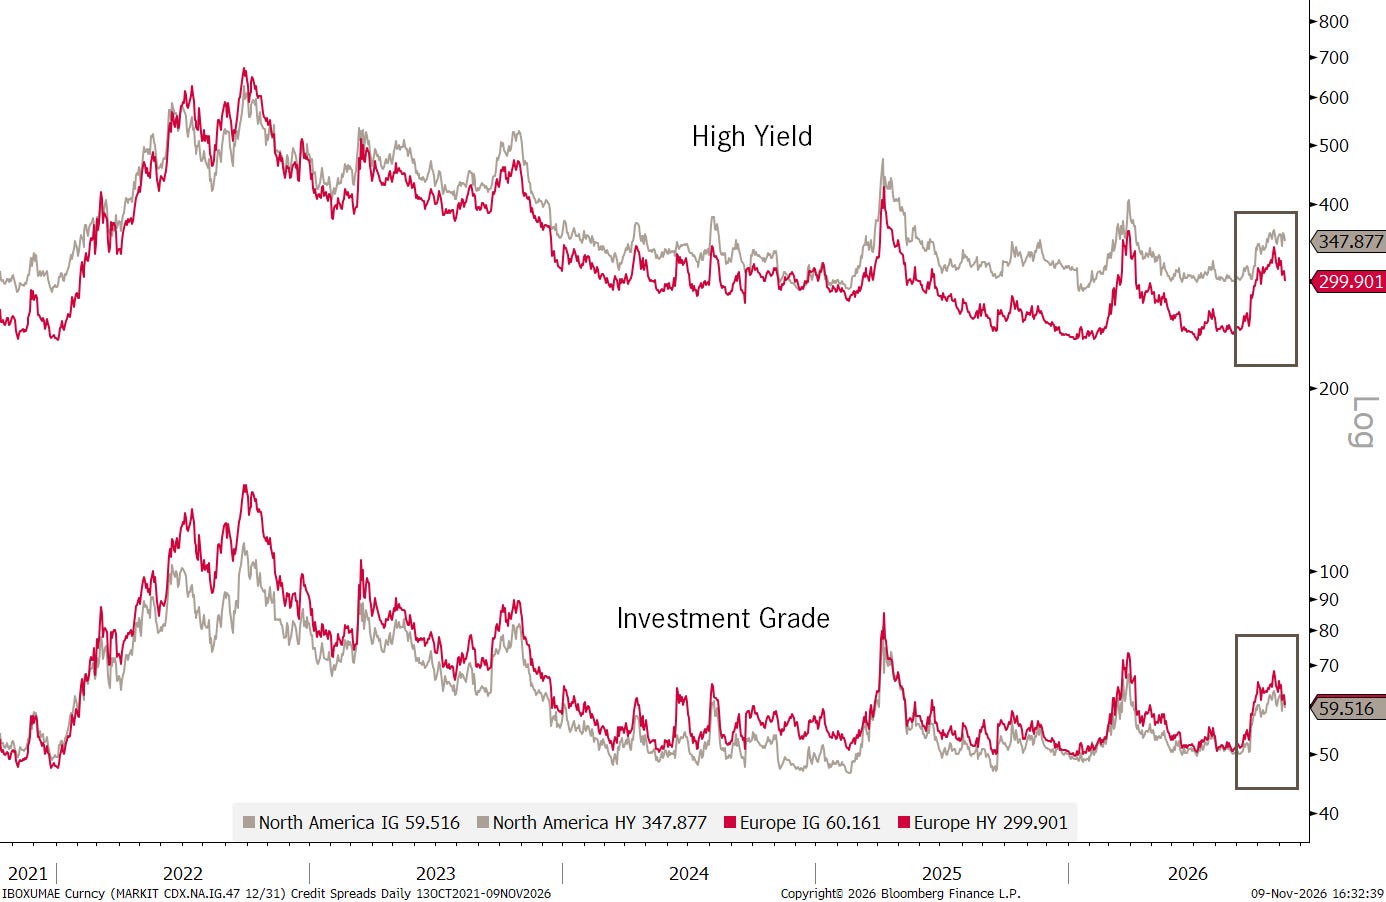
Perhaps.
For now at least. But watch this space next year.
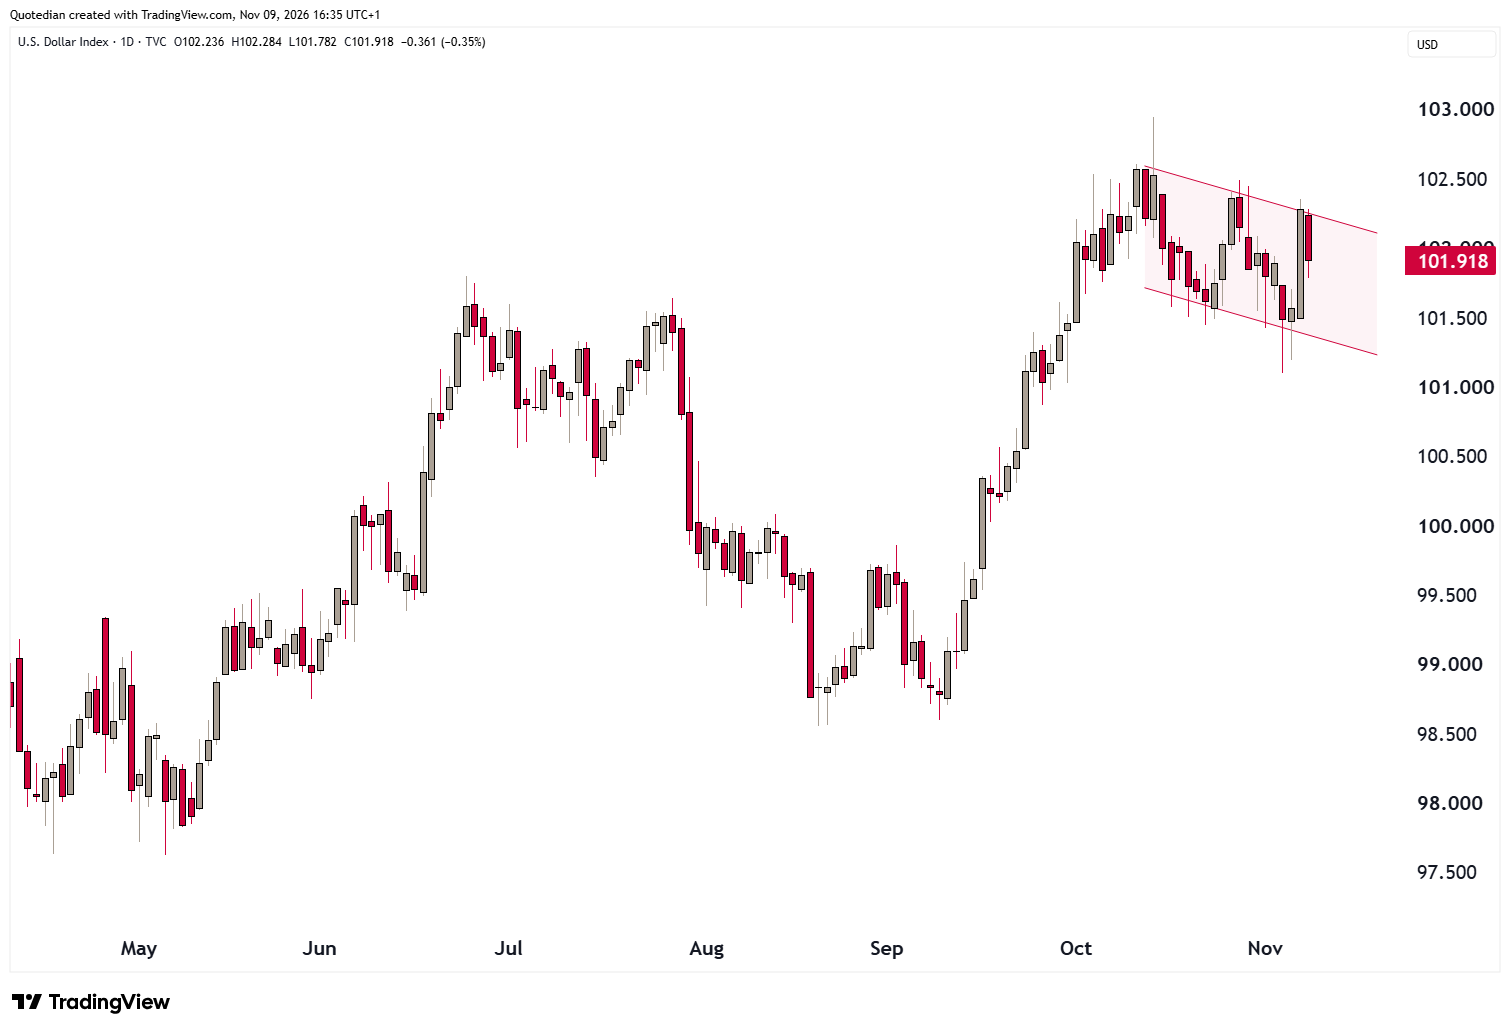
In currency markets, the US Dollar (DXY) had a big up day on Friday, but today is giving back about half of those gains:
The EUR/USD is rebounding from key support at around 1.11-ish, but continues to look weak:
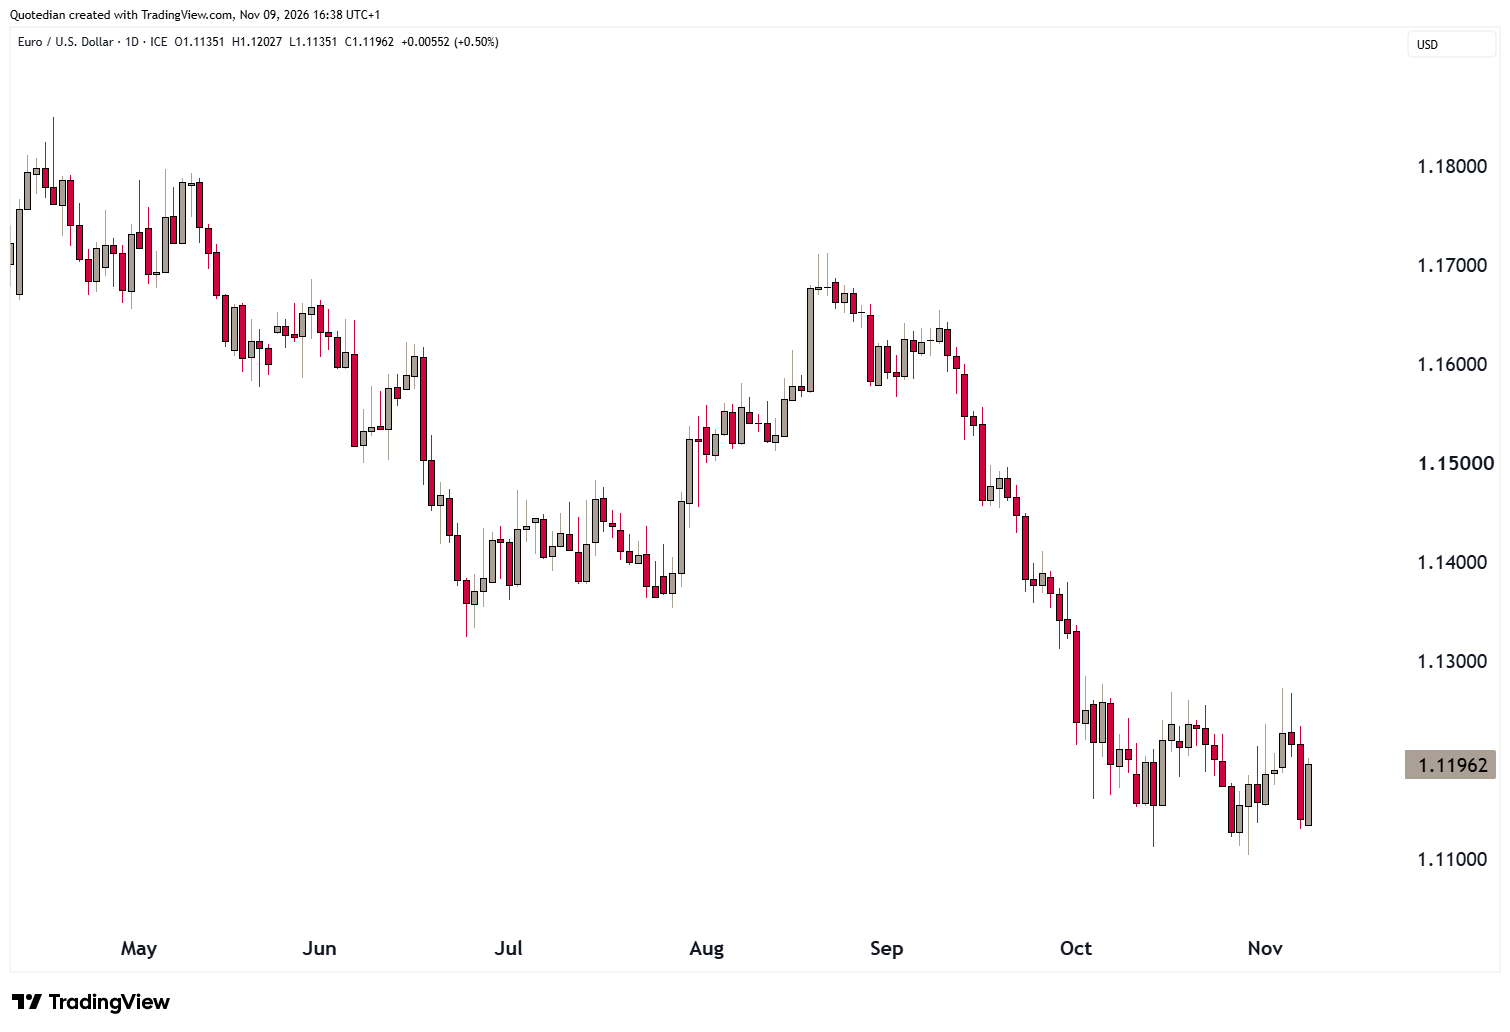
A break above 1.1275 would substantially improve the chart.
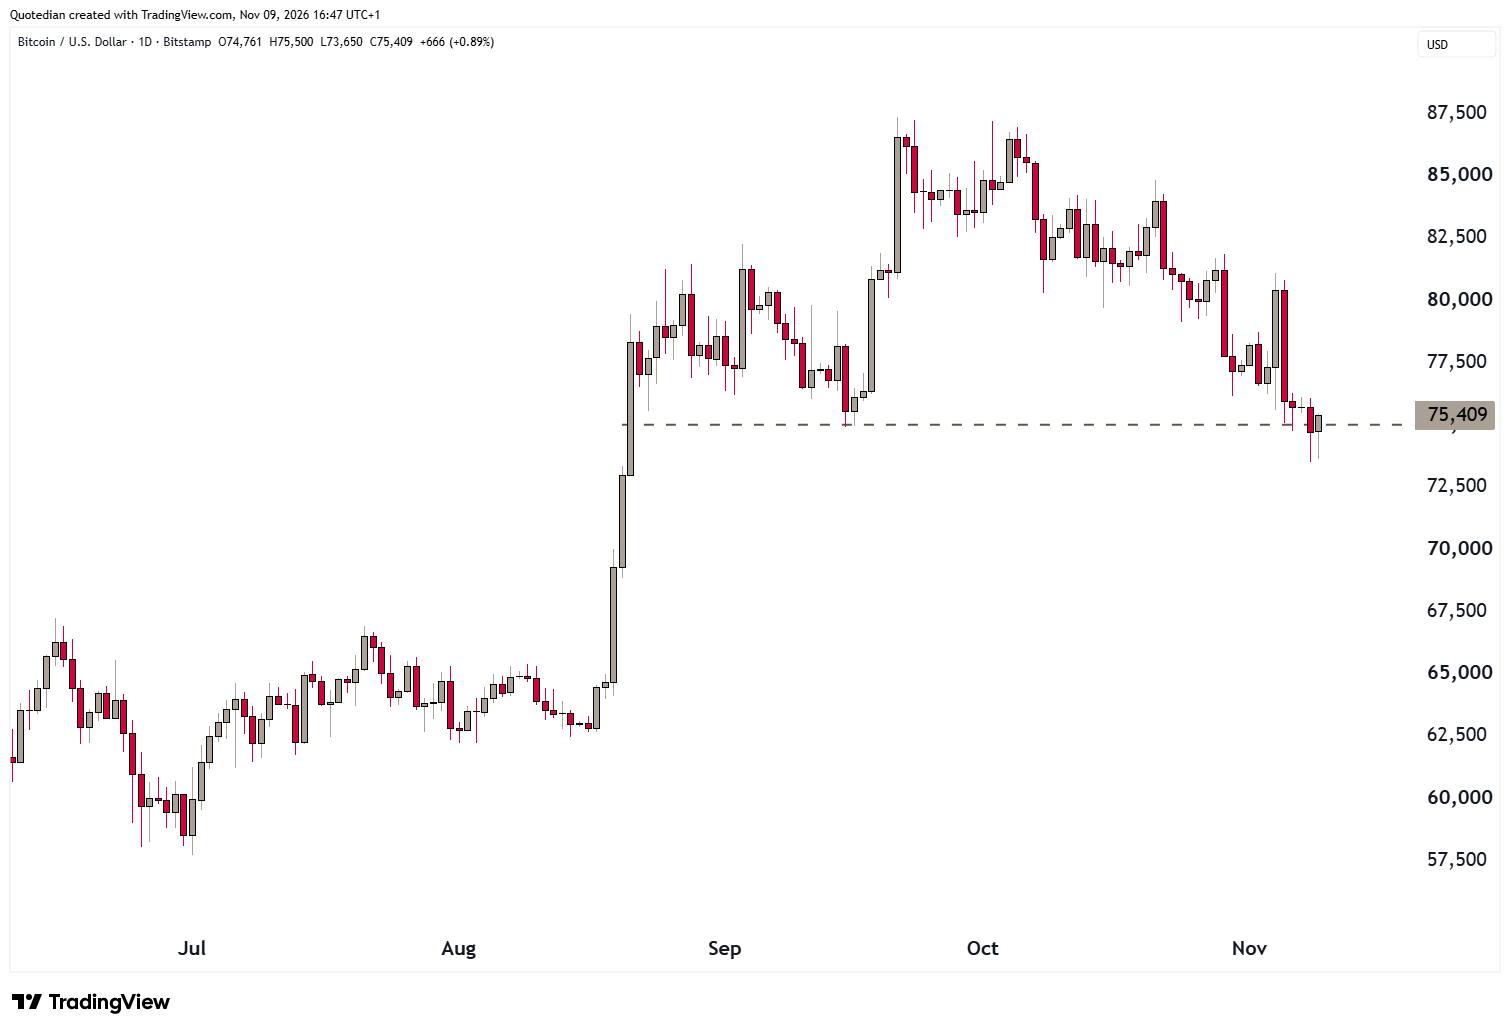
Bitcoin was another election “victim”, as a Democratic Congress is expected to be less crypto-friendly than the Republicans:
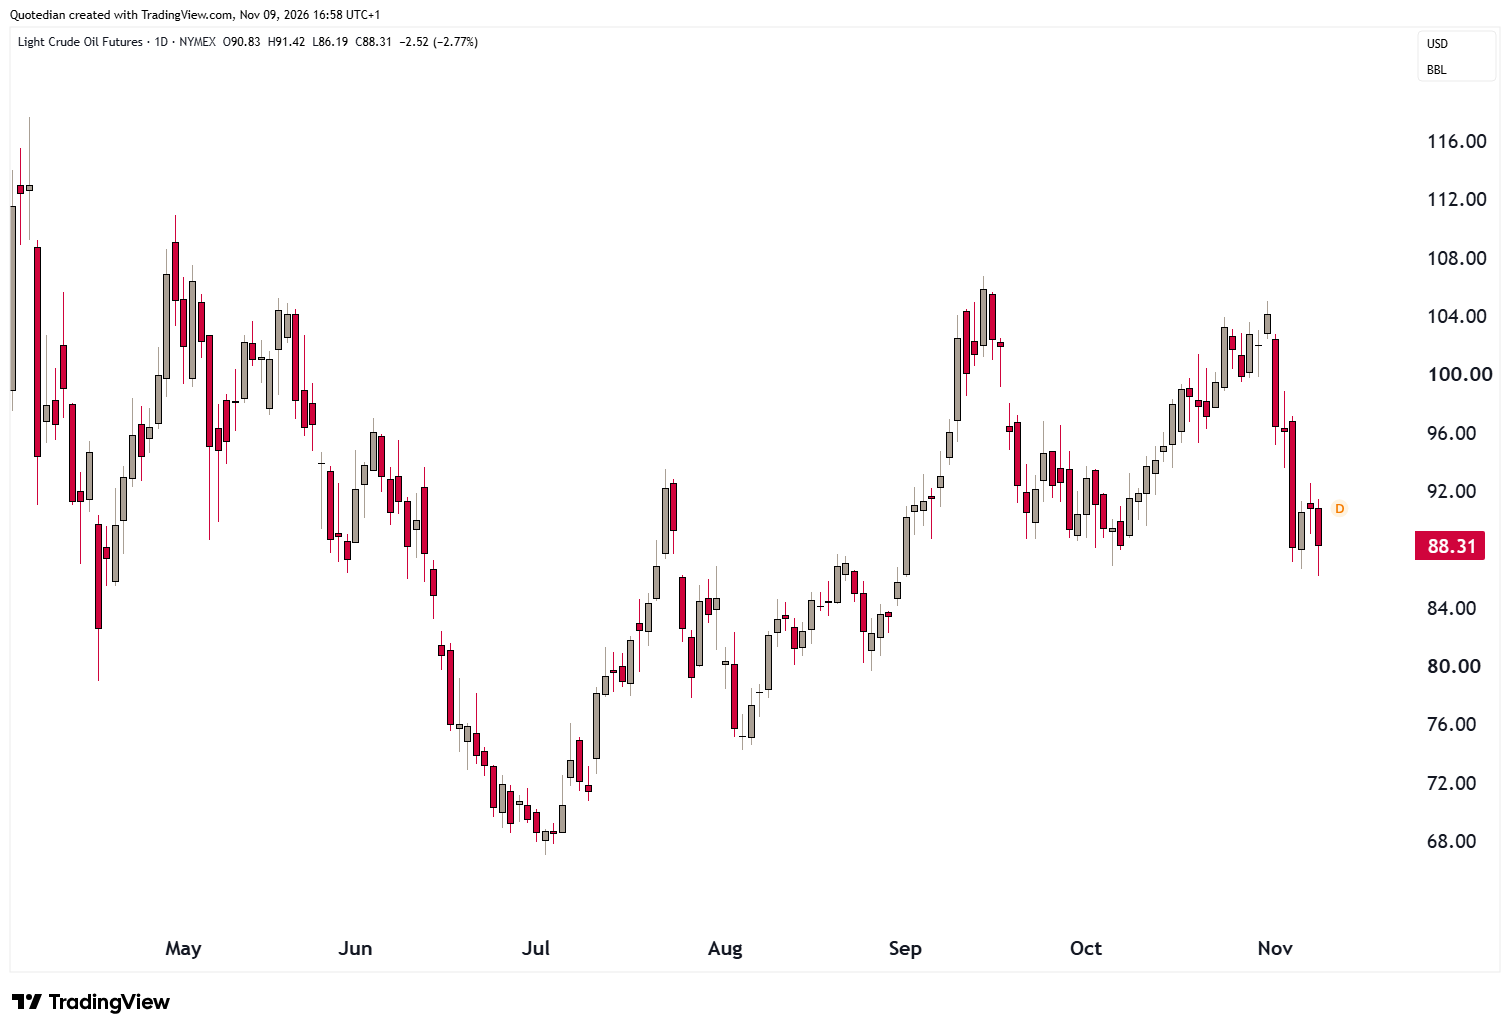
In the commodity space, crude oil futures (WTI) are down 15% so far this month, as the US midterm election outcome further accelerated the repricing which was already underway on hopes over peace talks:
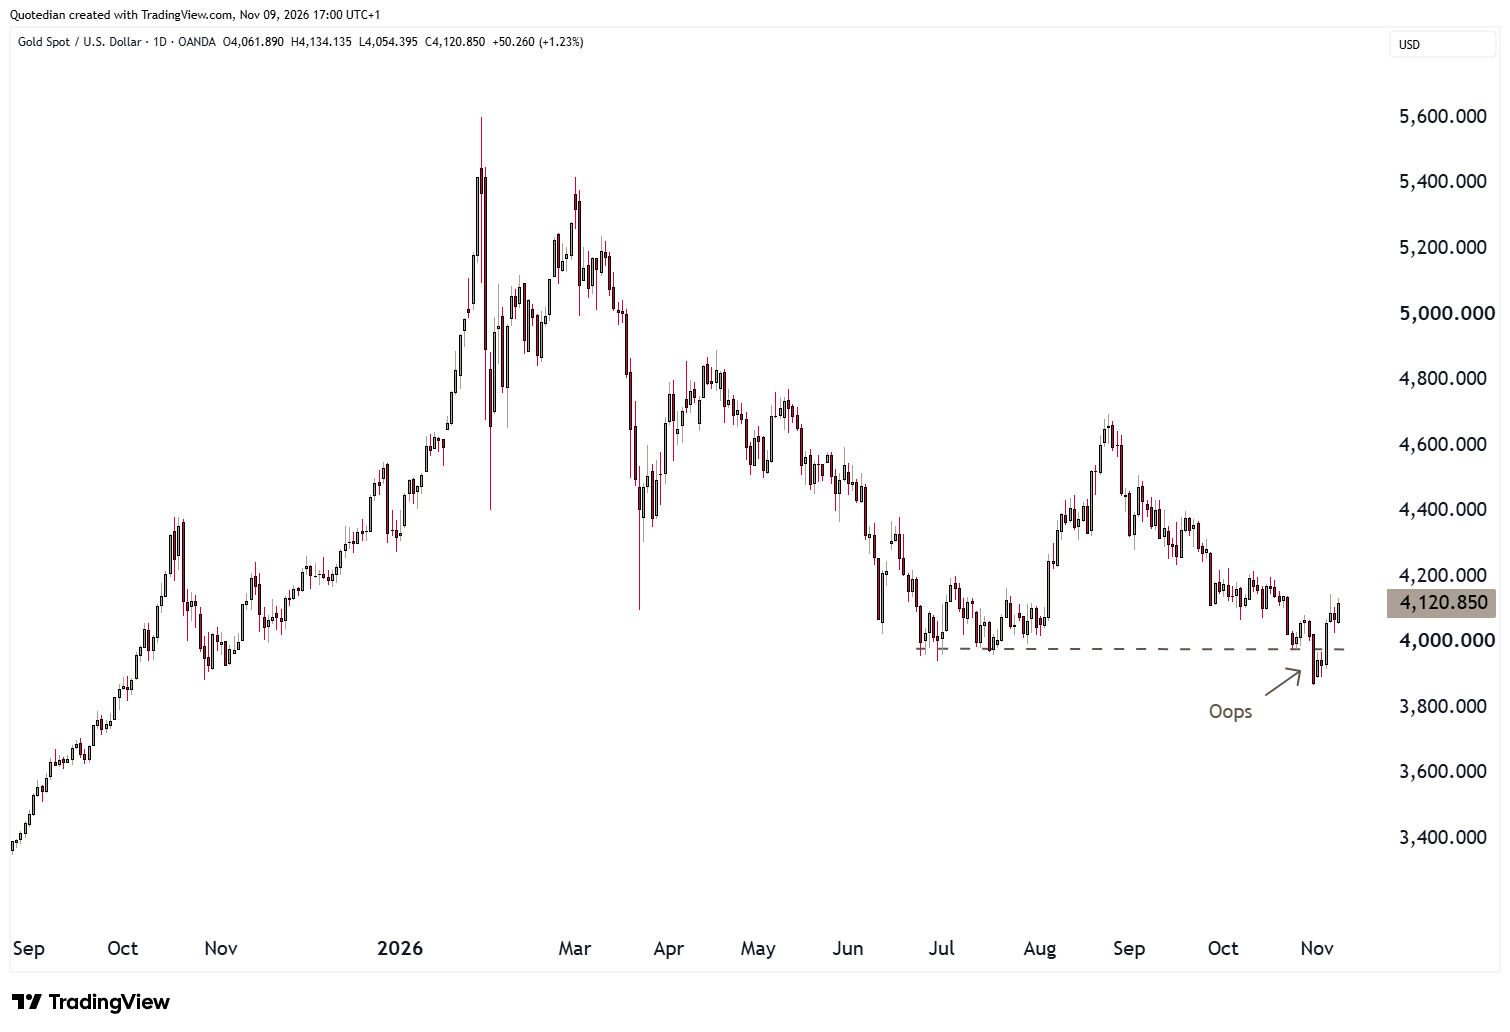
One important winner last week was the price of Gold, which recorded a much-needed lift above previously broken support:
And finally, right out of the curiosity corner, this X.com post:
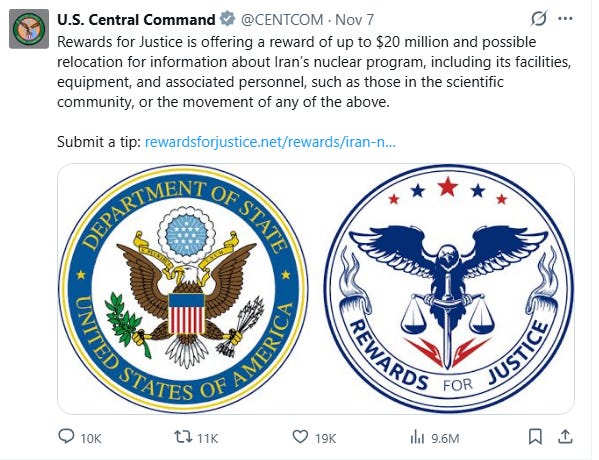
Just when you thought you had seen it all …

Last week seemed to have been some clearing event post the mid-term election. At least a clearing event for some portfolio which seemed to have been ‘enjoying’ forced selling at US market open on Thursday.
Whilst Friday’s rebound was weak and therefore made us feel a bit uncomfortable, today’s (Monday) follow-through has improved the outlook for further gains.
Tomorrow we will see the release of consumer price inflation (CPI) data in the US, followed on Friday (the 13th!) by PPI.
That’s all for this week - May the Trend be with You!
André

The Important One:
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG
The Legal One: