

"Le roi est mort, vive le roi!"
— Traditional Proclamation


[Admin note: This Quotedian was written mostly on Sunday and Monday, so most charts will be updated through Friday afternoon. In a fast moving world, it can make a difference. Caveat Emptor!]
No worries, we are not going to discuss the happenings around NVDA and its ex-CEO Jensen Huang here, as a) we have been reading about twists in the plot ad nauseam, b) it seems the final chapter has not been written … disclosed … snitched yet and c) I have definitely no value-add other than a few silly dad jokes:
The AI bubble got “pricked”
Something’s Huang at NVDA
Two Huangs don’t make a right
Enough!!
What is definitely worth a more serious discussion are the wider implications of what has been in happening over the past few days in terms of:
The State versus Tech
andThe US versus China
But let’s leave this conversation for another day, and maybe we’ll have to discuss this incognito… you never know who is listening!
What is not a silly joke is that since its top on October 10th, NVDA market cap has dropped by nearly two trillion bucks:
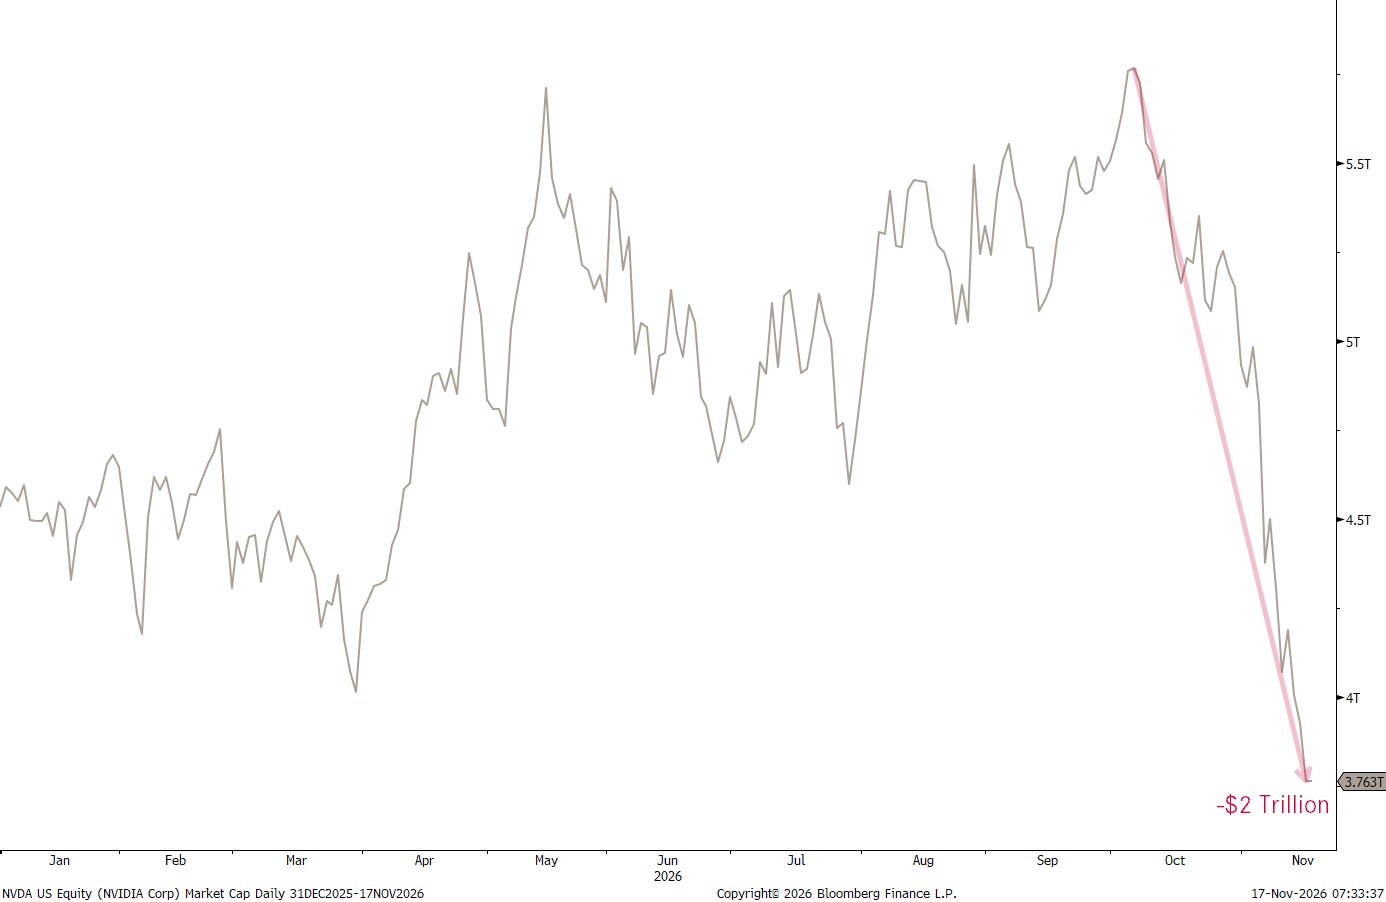
That is more than the market cap of the entire Spanish ($1.4T), Dutch ($1.7T) or Hong Kong ($1.7T) stock market!
The company will be reporting its quarterly earnings number for the first time after 33 years without Jensen Huang tomorrow after the market close … that should be fun!
Onwards…
This is NOT how last week felt:
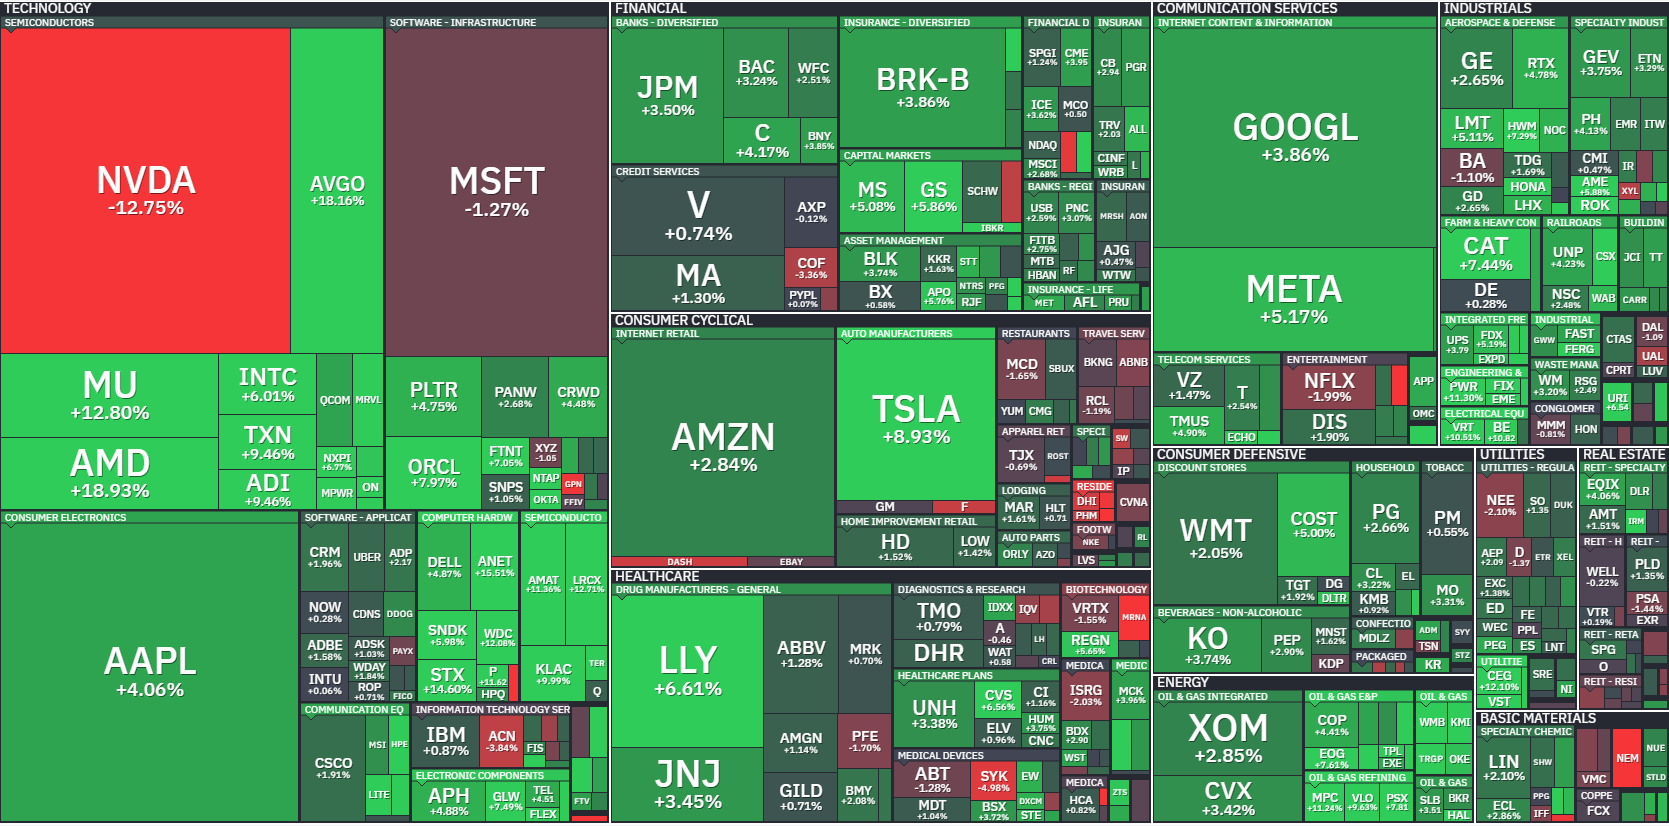
But amazingly, it has been a pretty good week for global stock markets, despite Jensen, CPI, Outlook, Waller et al.:
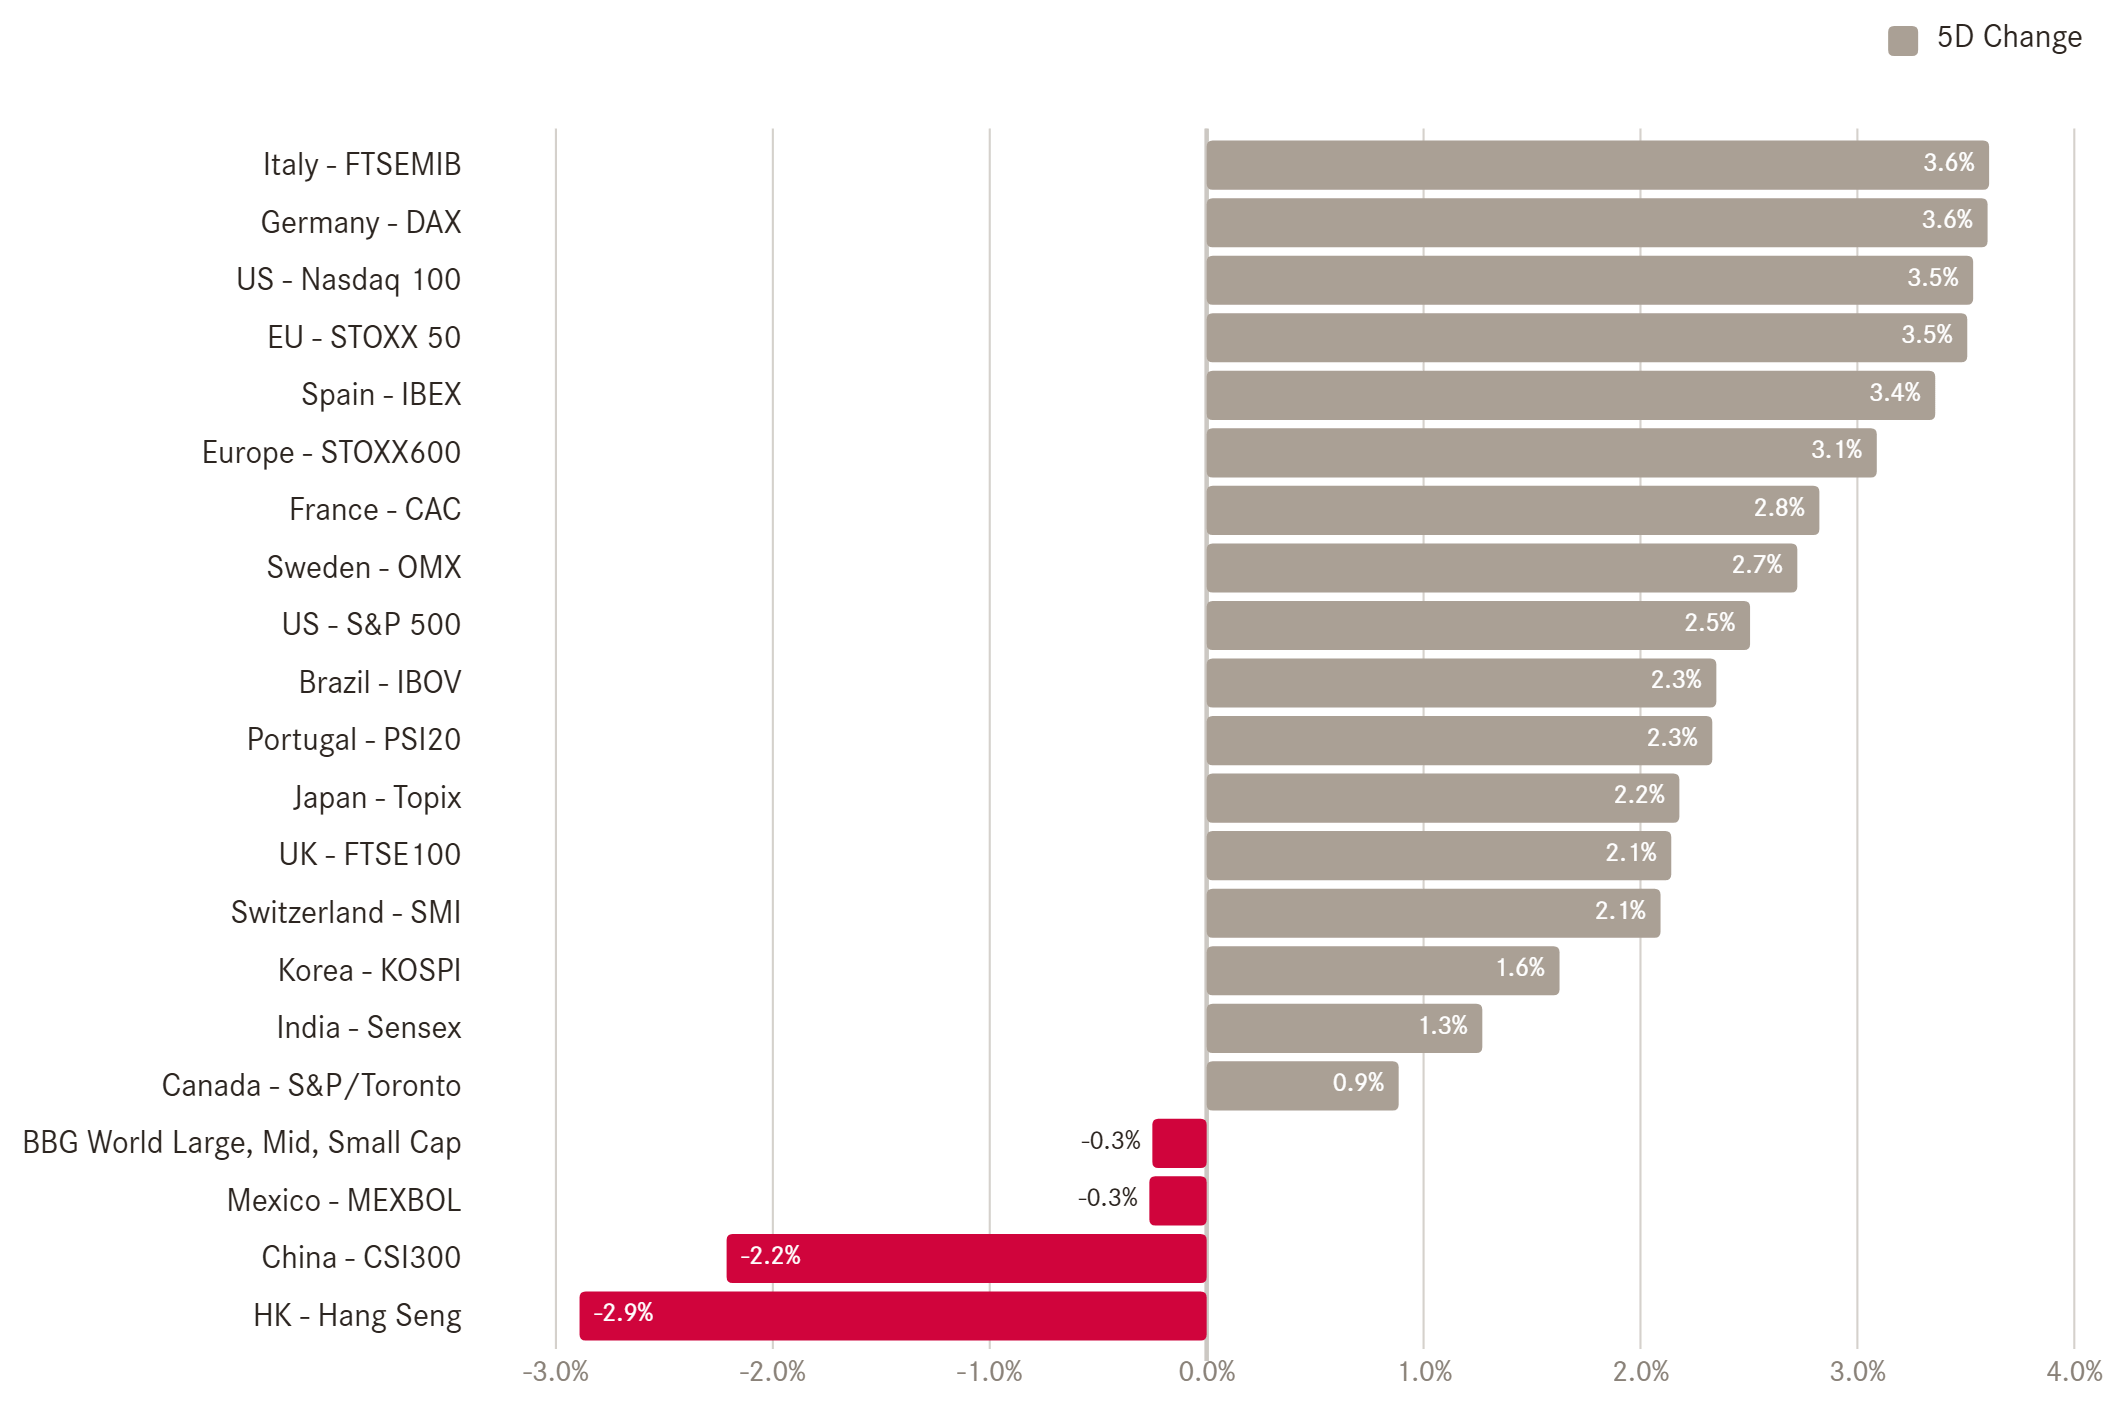
Given the following headlines, all from last week, that positive performance is all the more surprising:
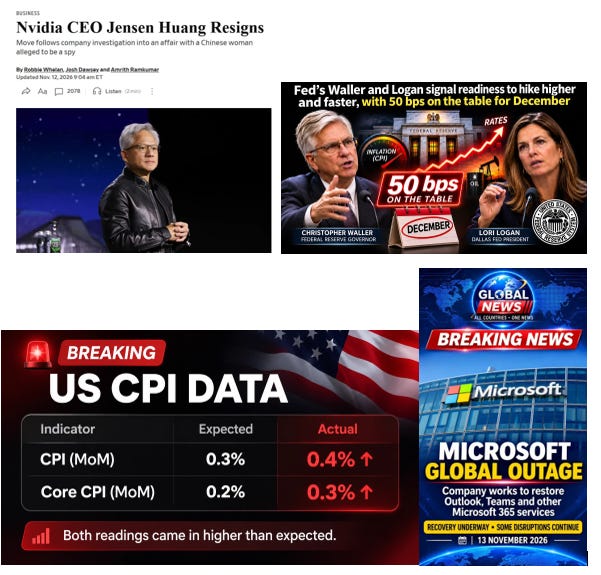
The S&P 500 (mini-futures) had a picture-perfect bounce on the 200-day moving average (pointed hand) but is now struggling to move above the 21-day MA:
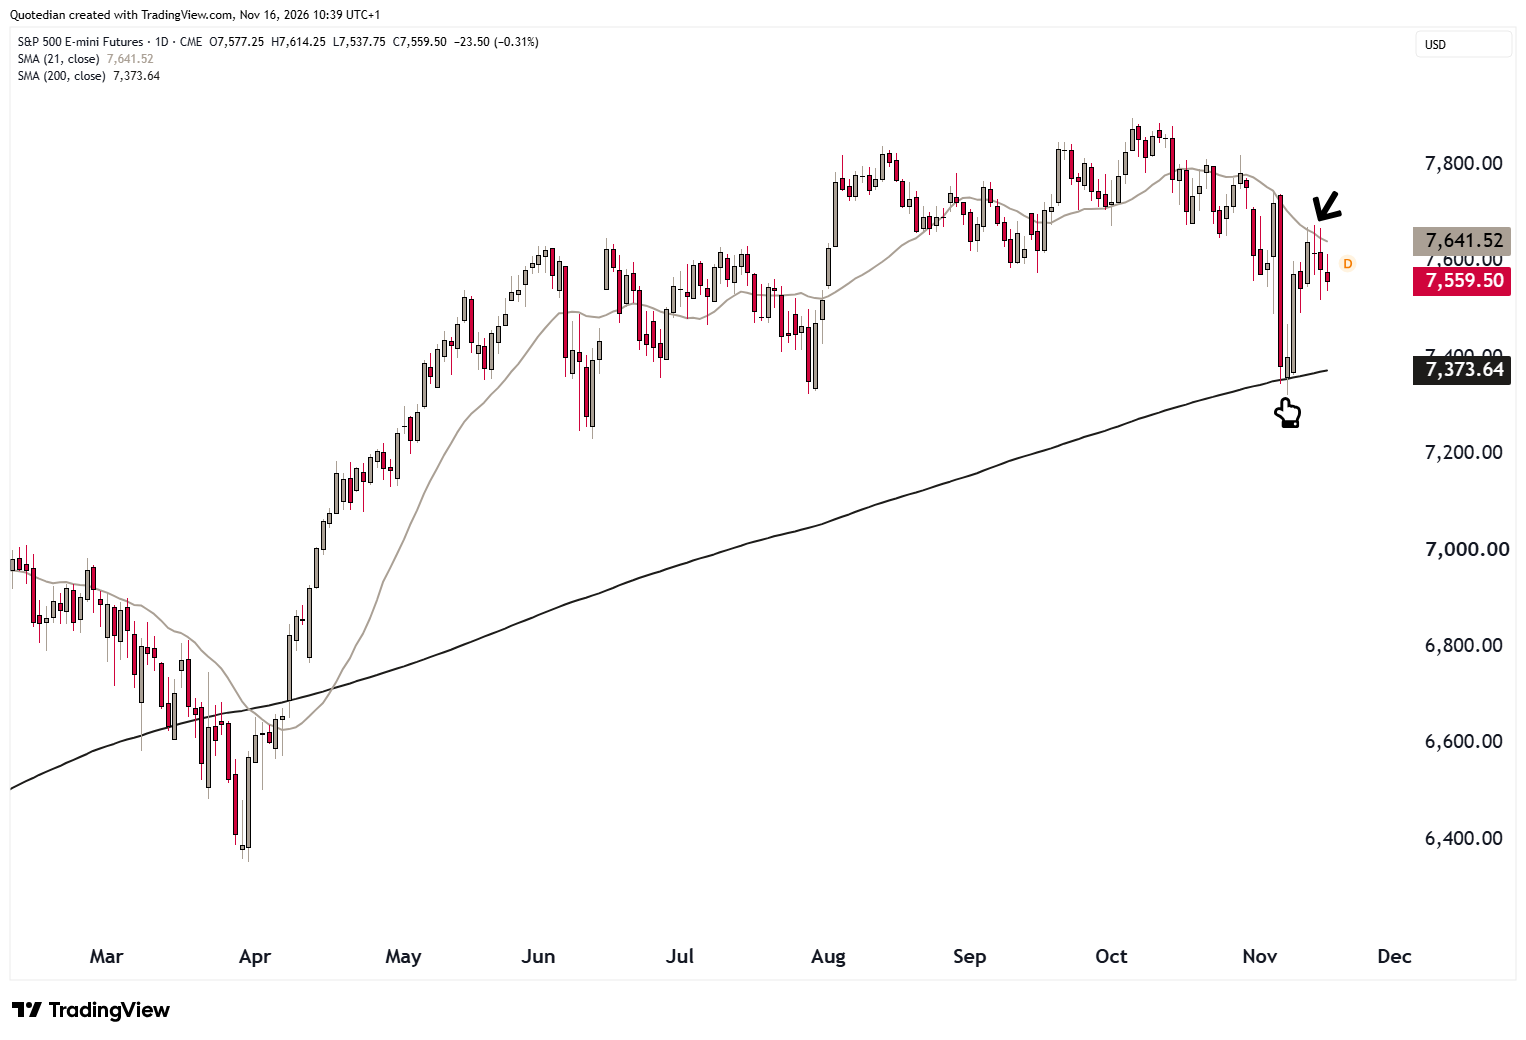
The performance difference between the S&P 500 equal-weight index (RSP - red) and the normal, cap-weight version (SPY - grey) since beginning of Q4 continues to grow:
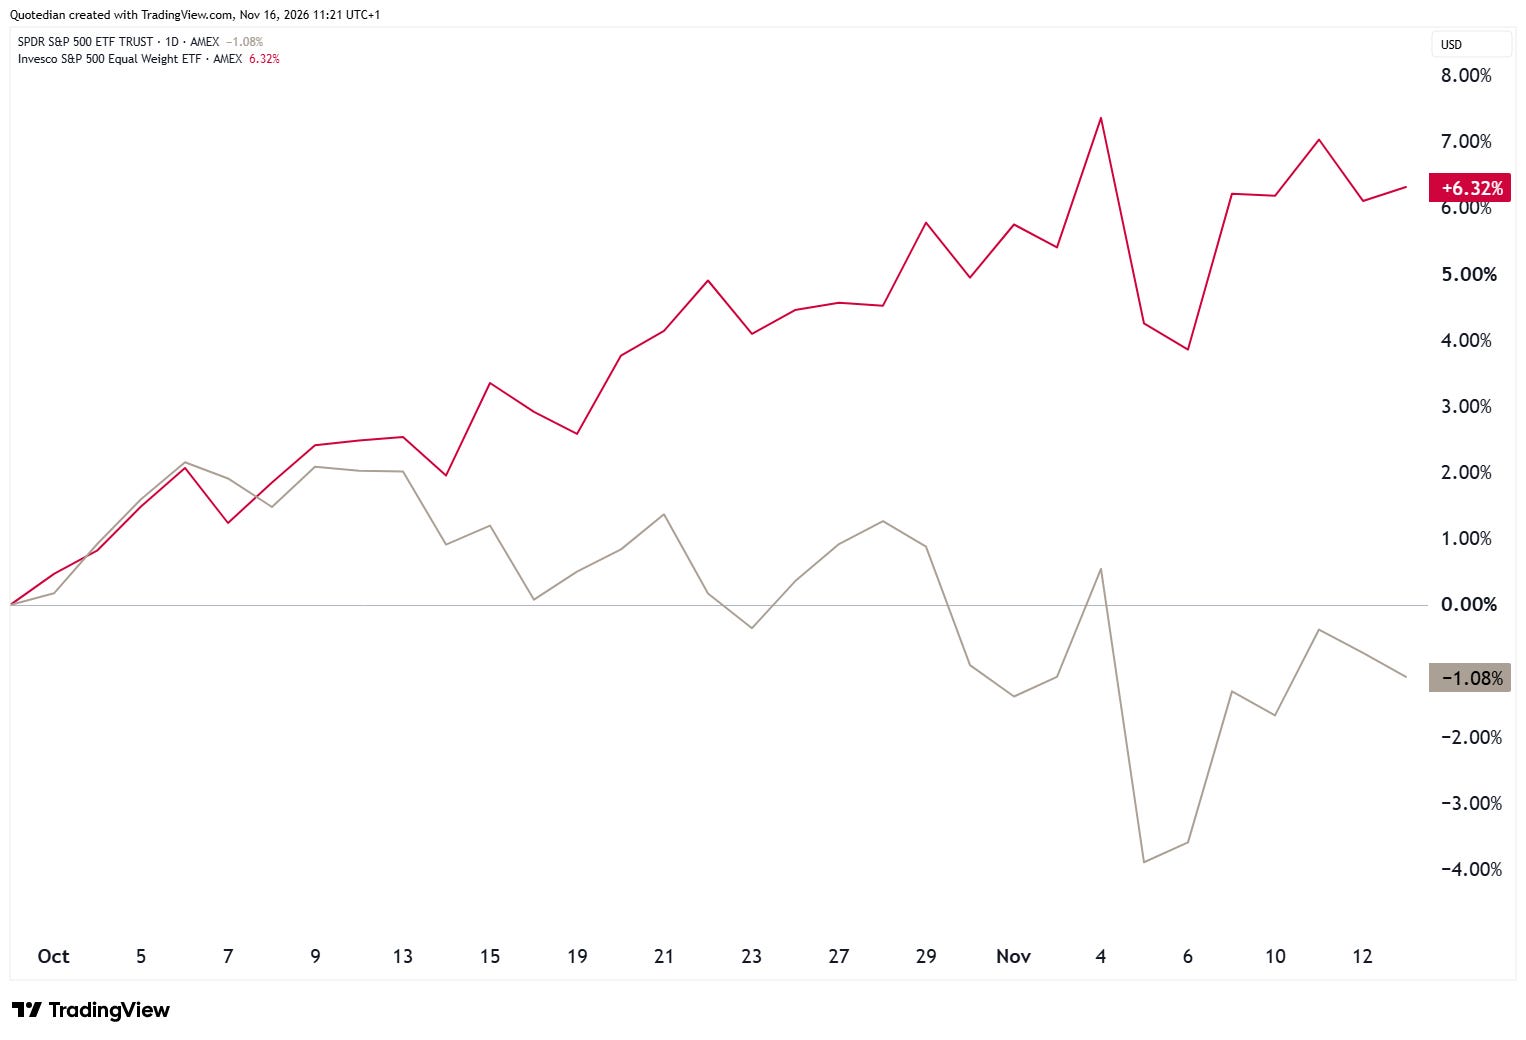
Despite having the larger bounce last week, the Nasdaq 100 continues to struggle to decisively move above its 200-day MA:
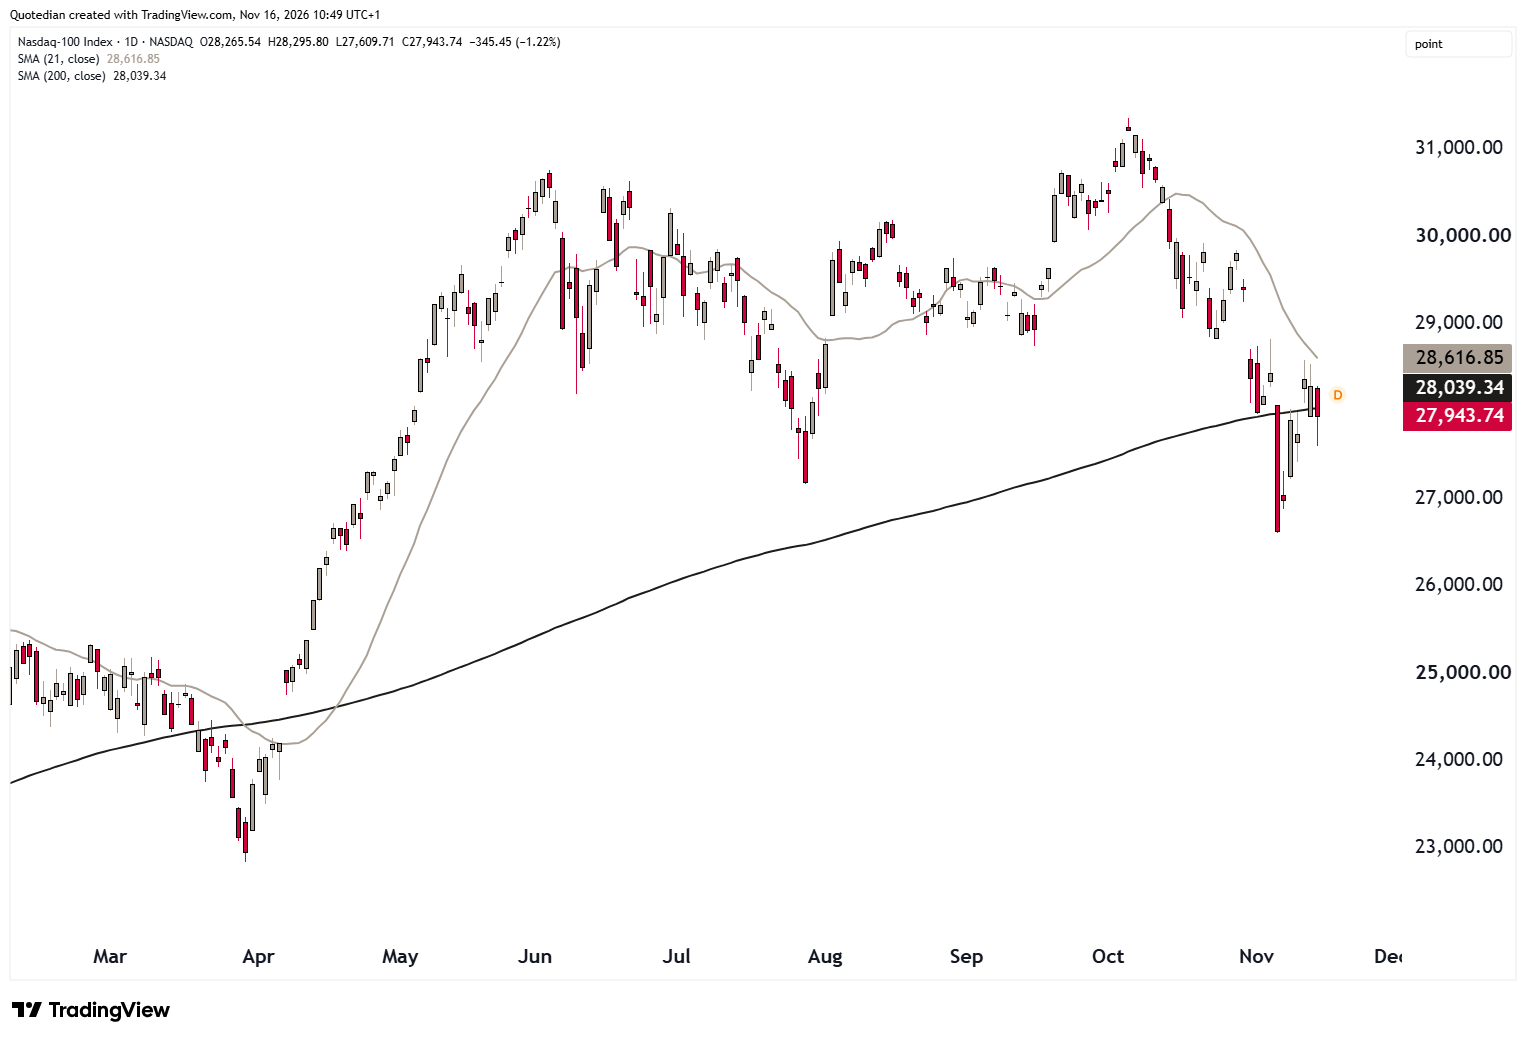
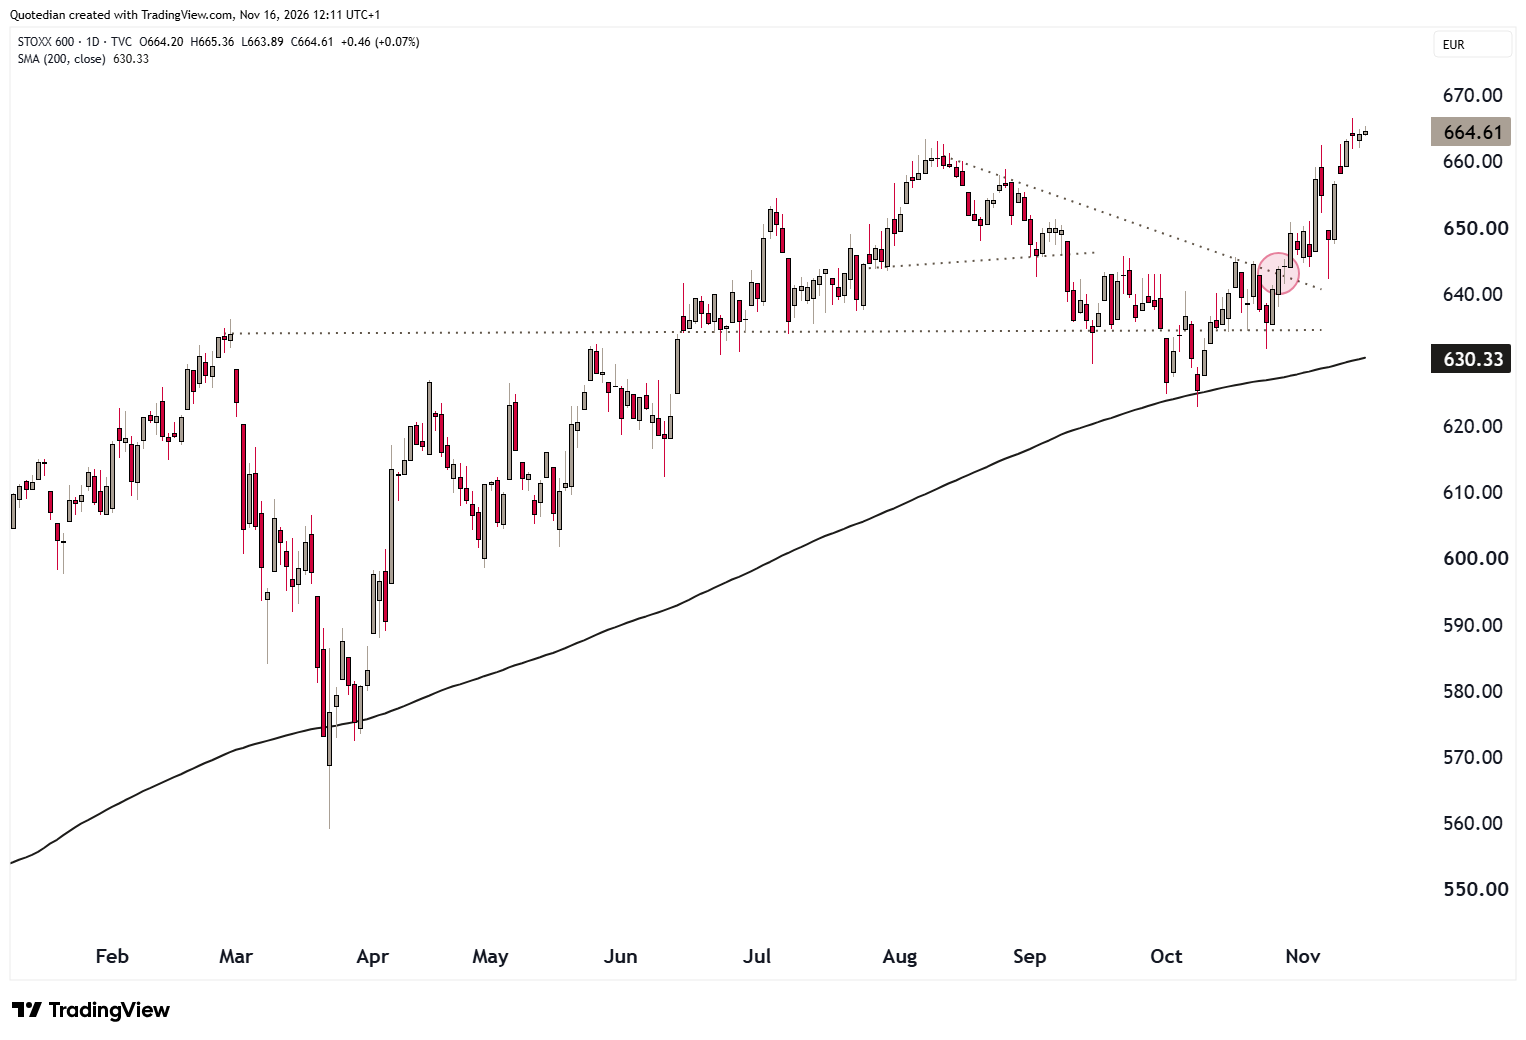
European stocks (SXXP), and don’t look now, have made a new all-time on Friday:
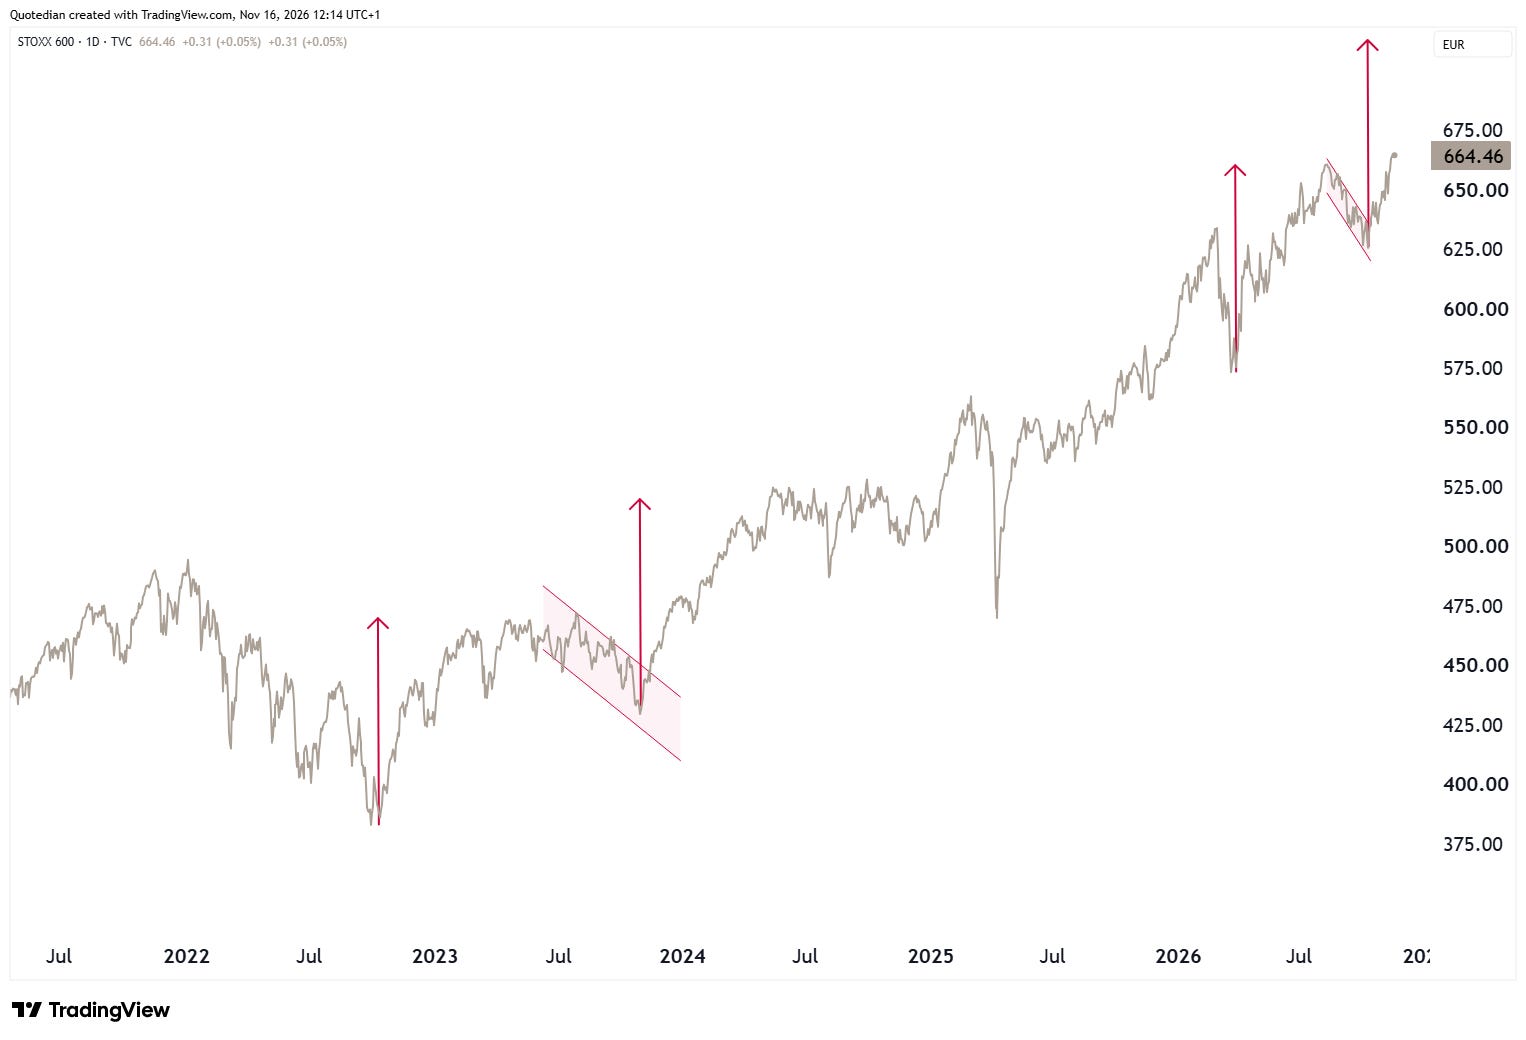
If the pole-flag-pole pattern of late 2023 repeats, the upside target could be at around 710 (+7%):
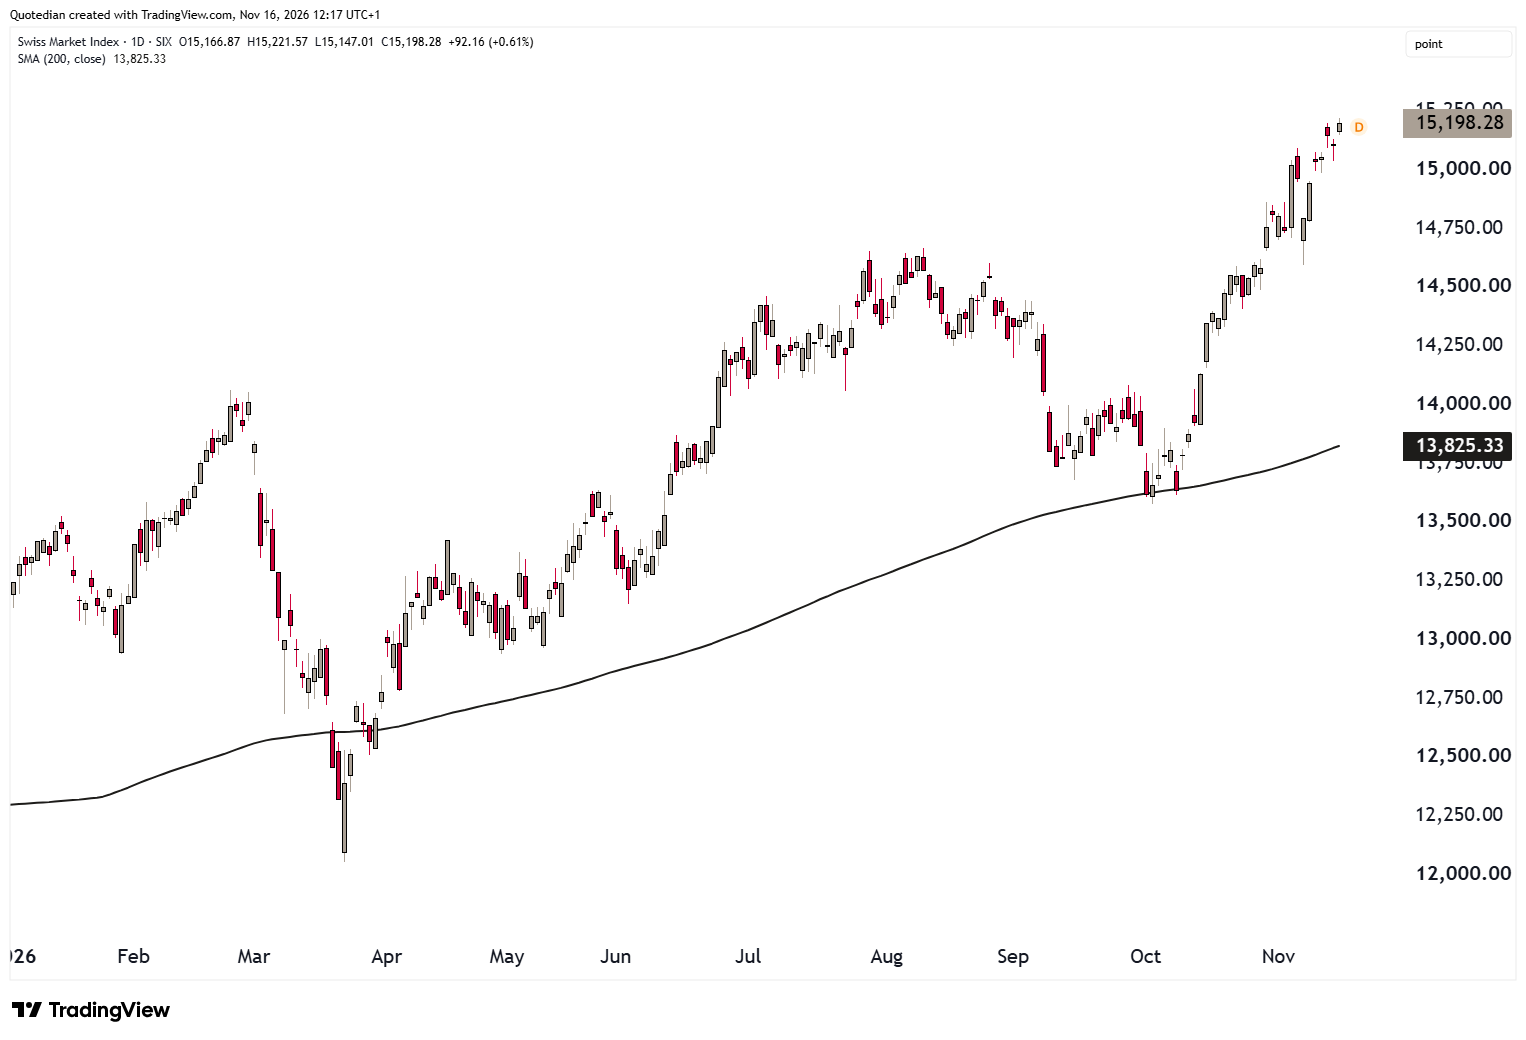
Switzerland’s SMI has been performing strong,
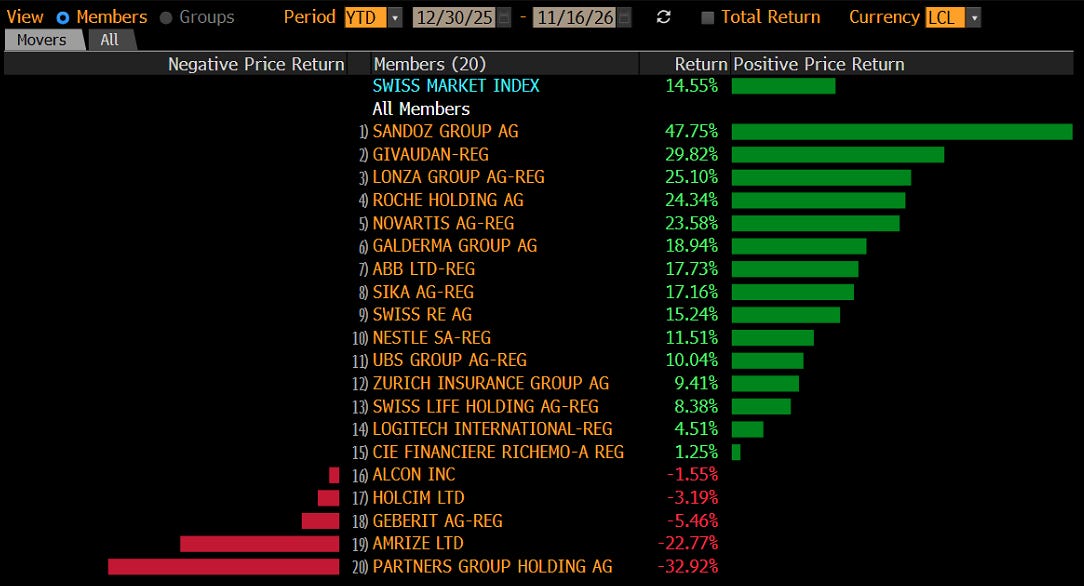
with the healthcare-related index members clearly being the pull:
Today (16.11.), as I am typing around lunchtime, the FTSE 100 is printing a new all-time high too:
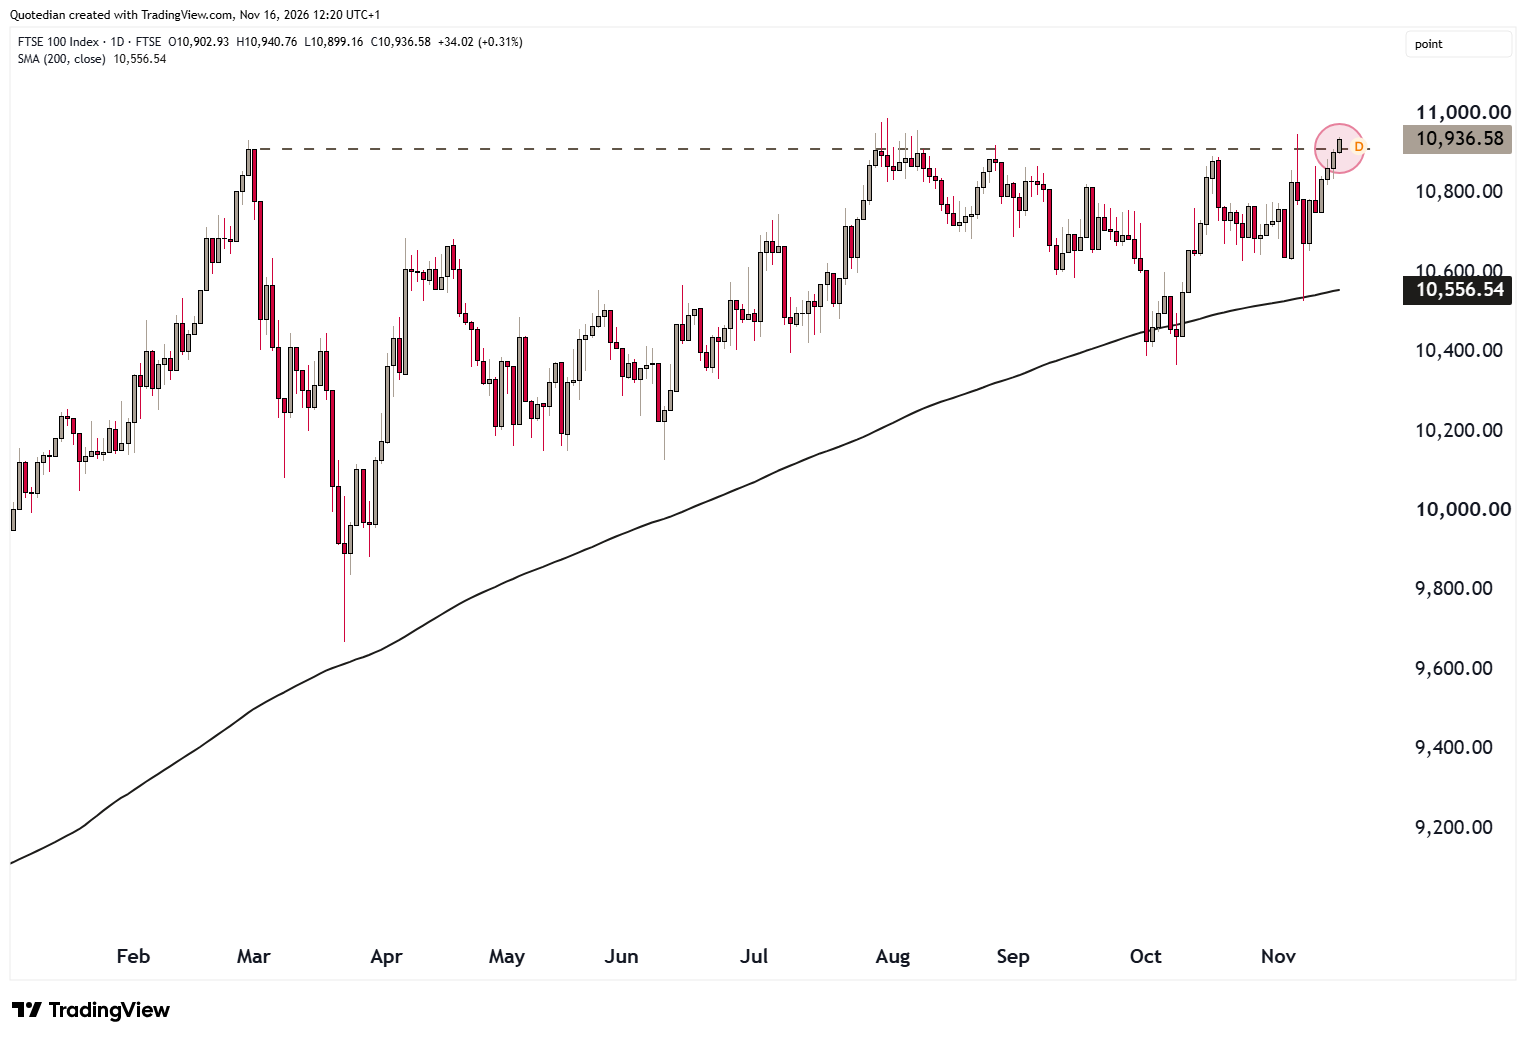
Will it hold into the close?
In Asian markets, Japan’s Nikkei has broken its 200-day MA two weeks ago and then was rejected by the same last week:
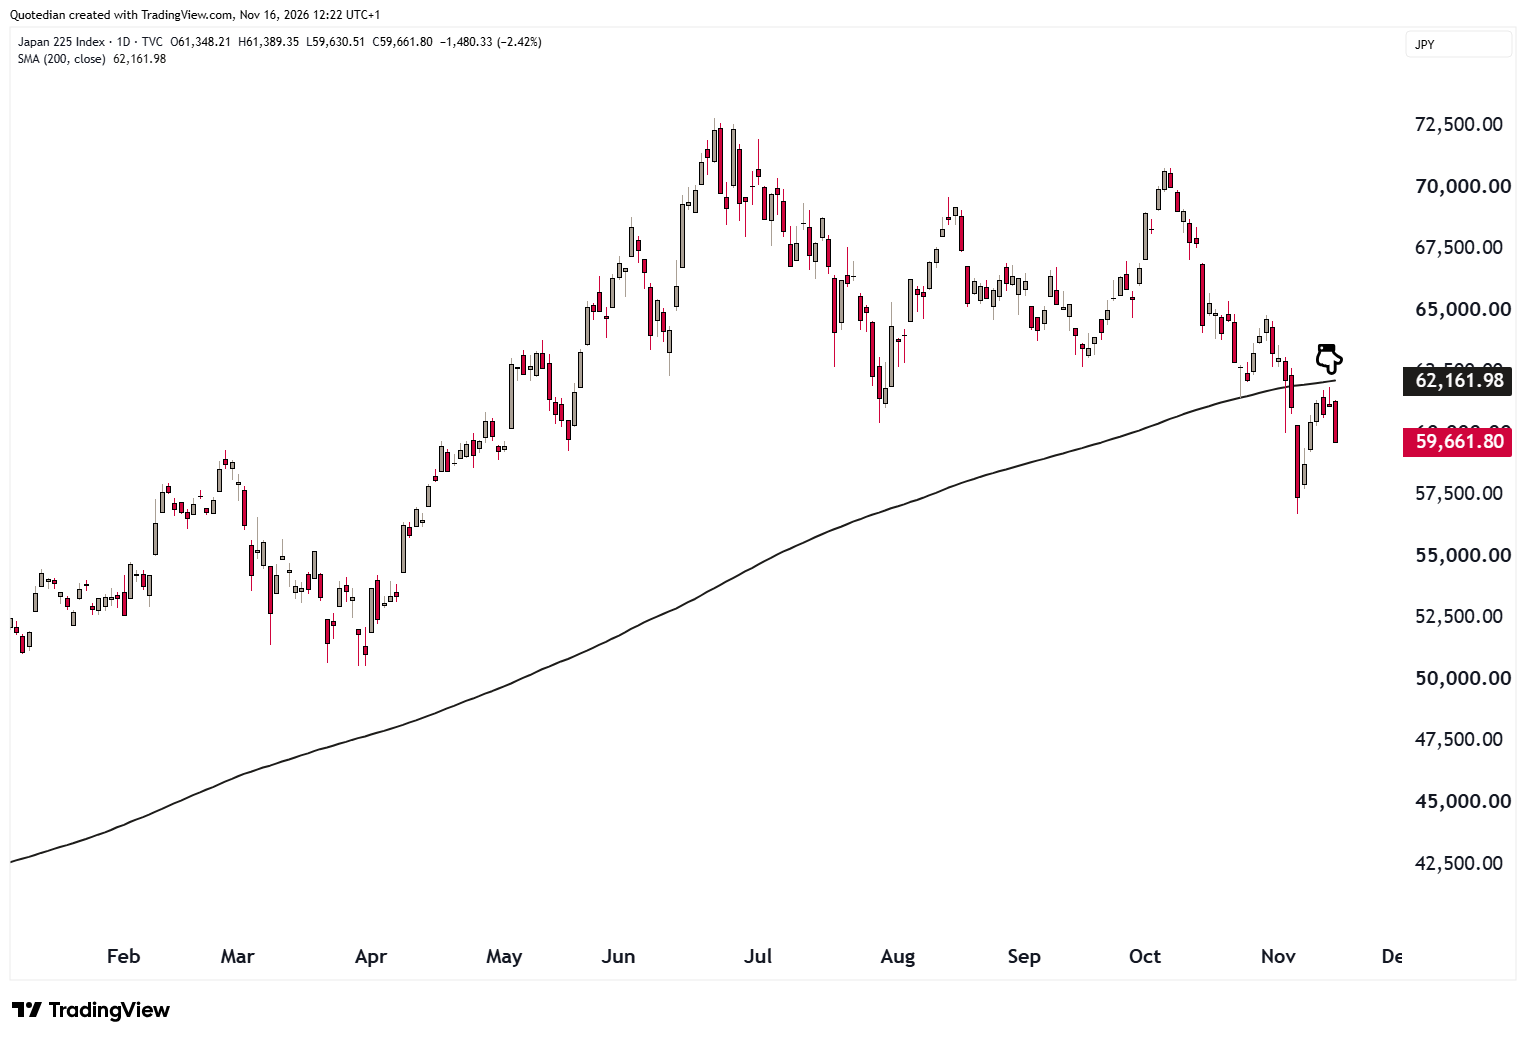
Will the broader Topix follow?
Chinese mainland stocks (CSI300) seem incapable of finding a bottom:
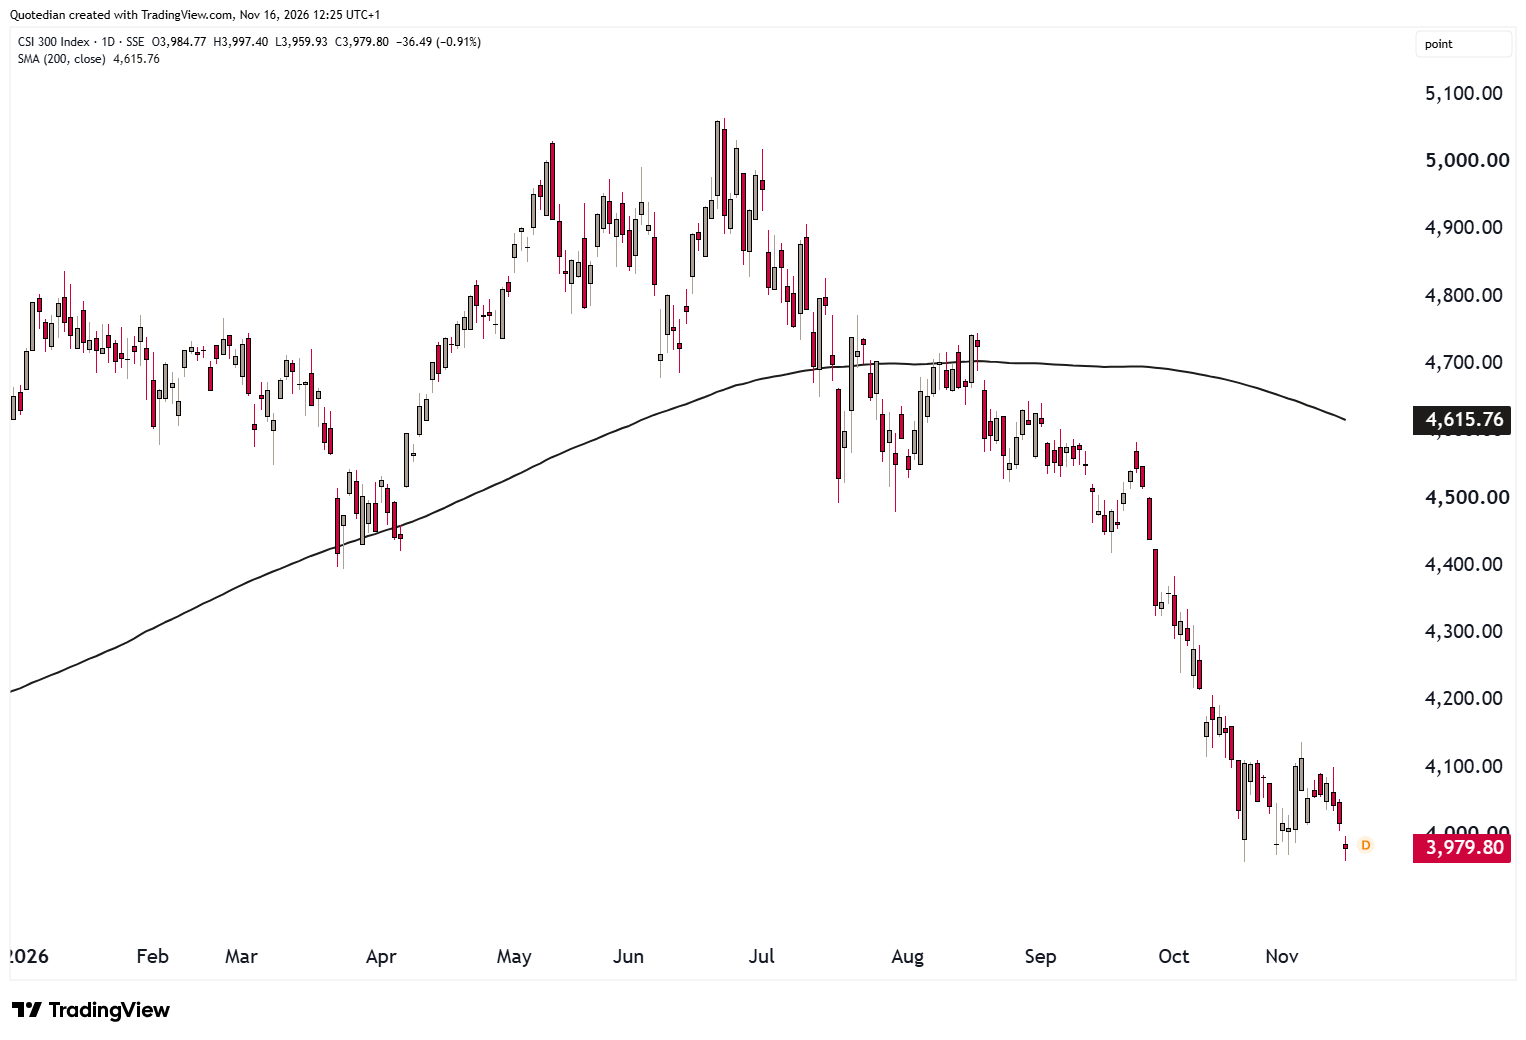
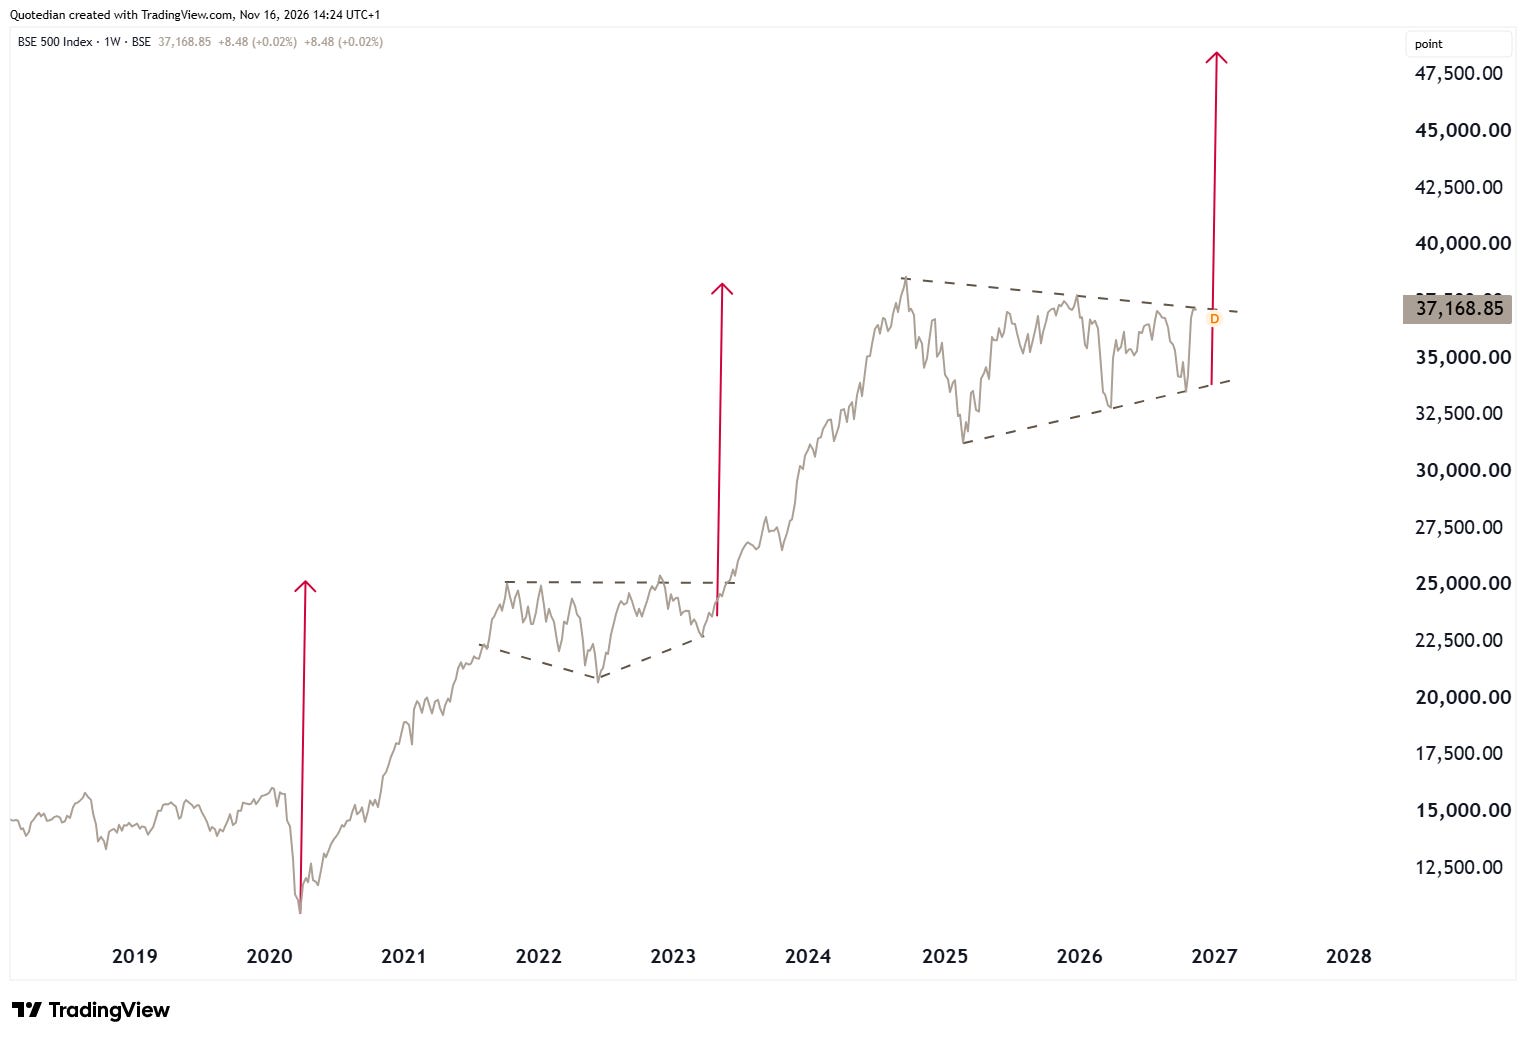
India’s celebrates Diwali, the festival of light, symbolising light over darkness, good over evil, and knowledge over ignorance, in November - and the stock market if fully participating in the “party”:
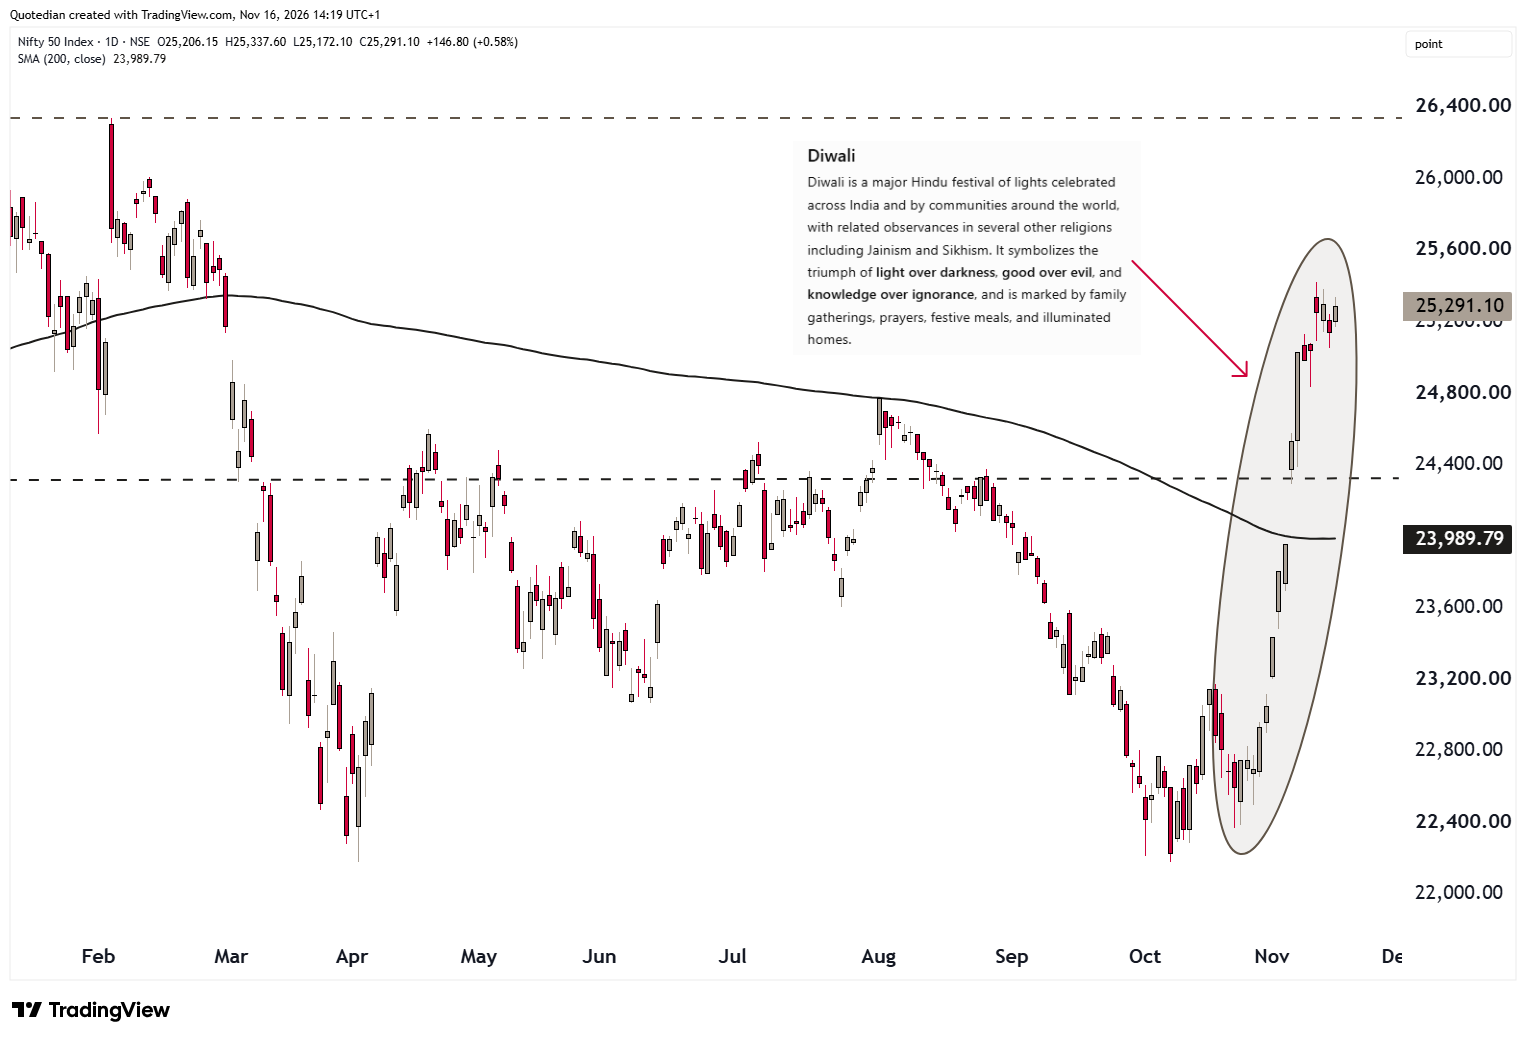
A break out of the consolidation range here, could have serious positive implications on the BSE500, just as it did back in mid-2023:
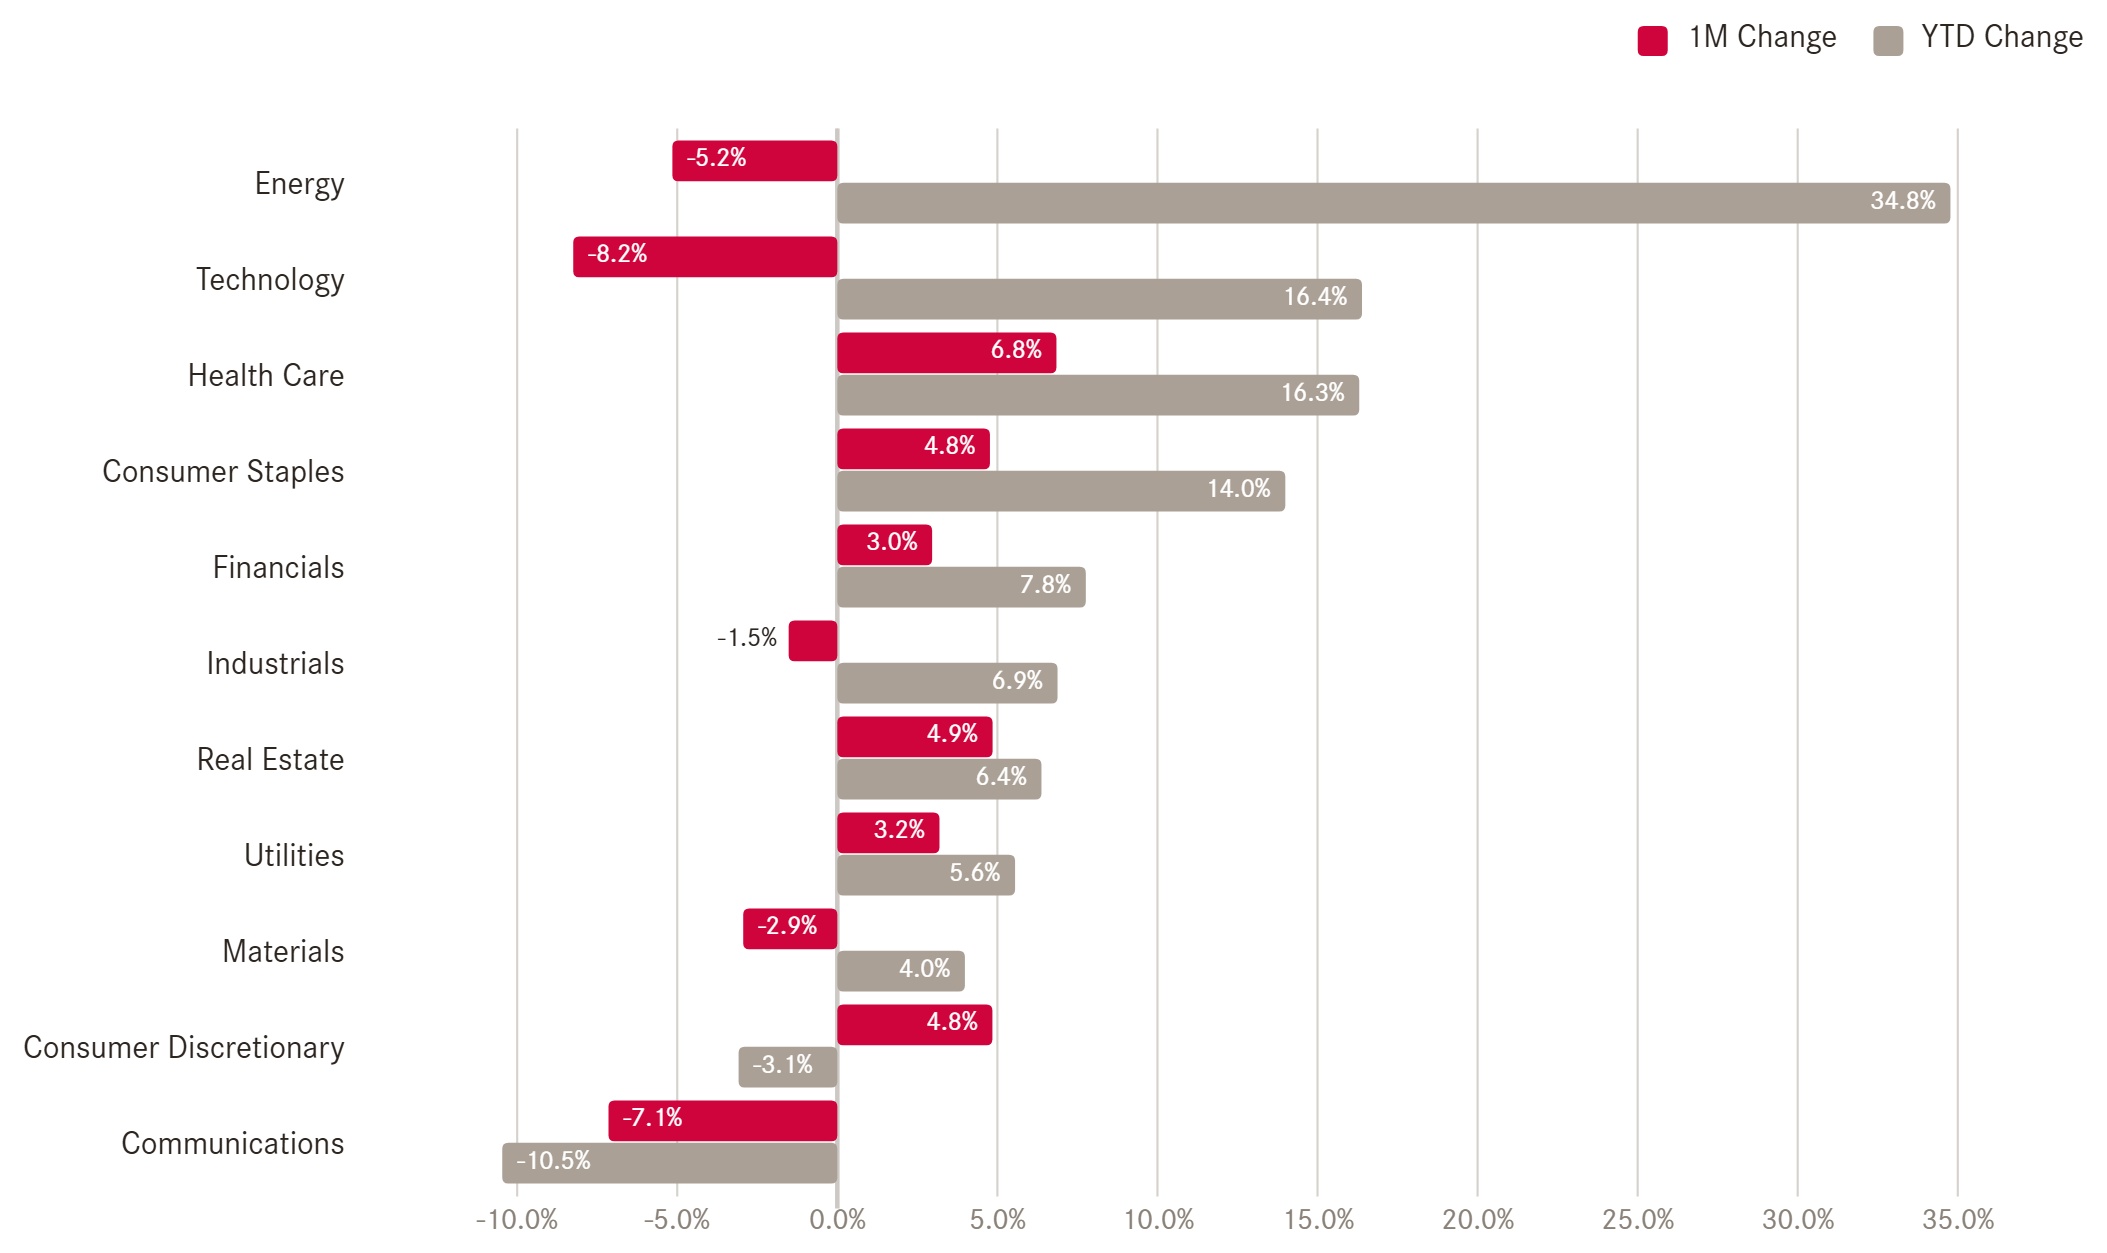
In terms of sector performance, there have been some important shifts over the past month:
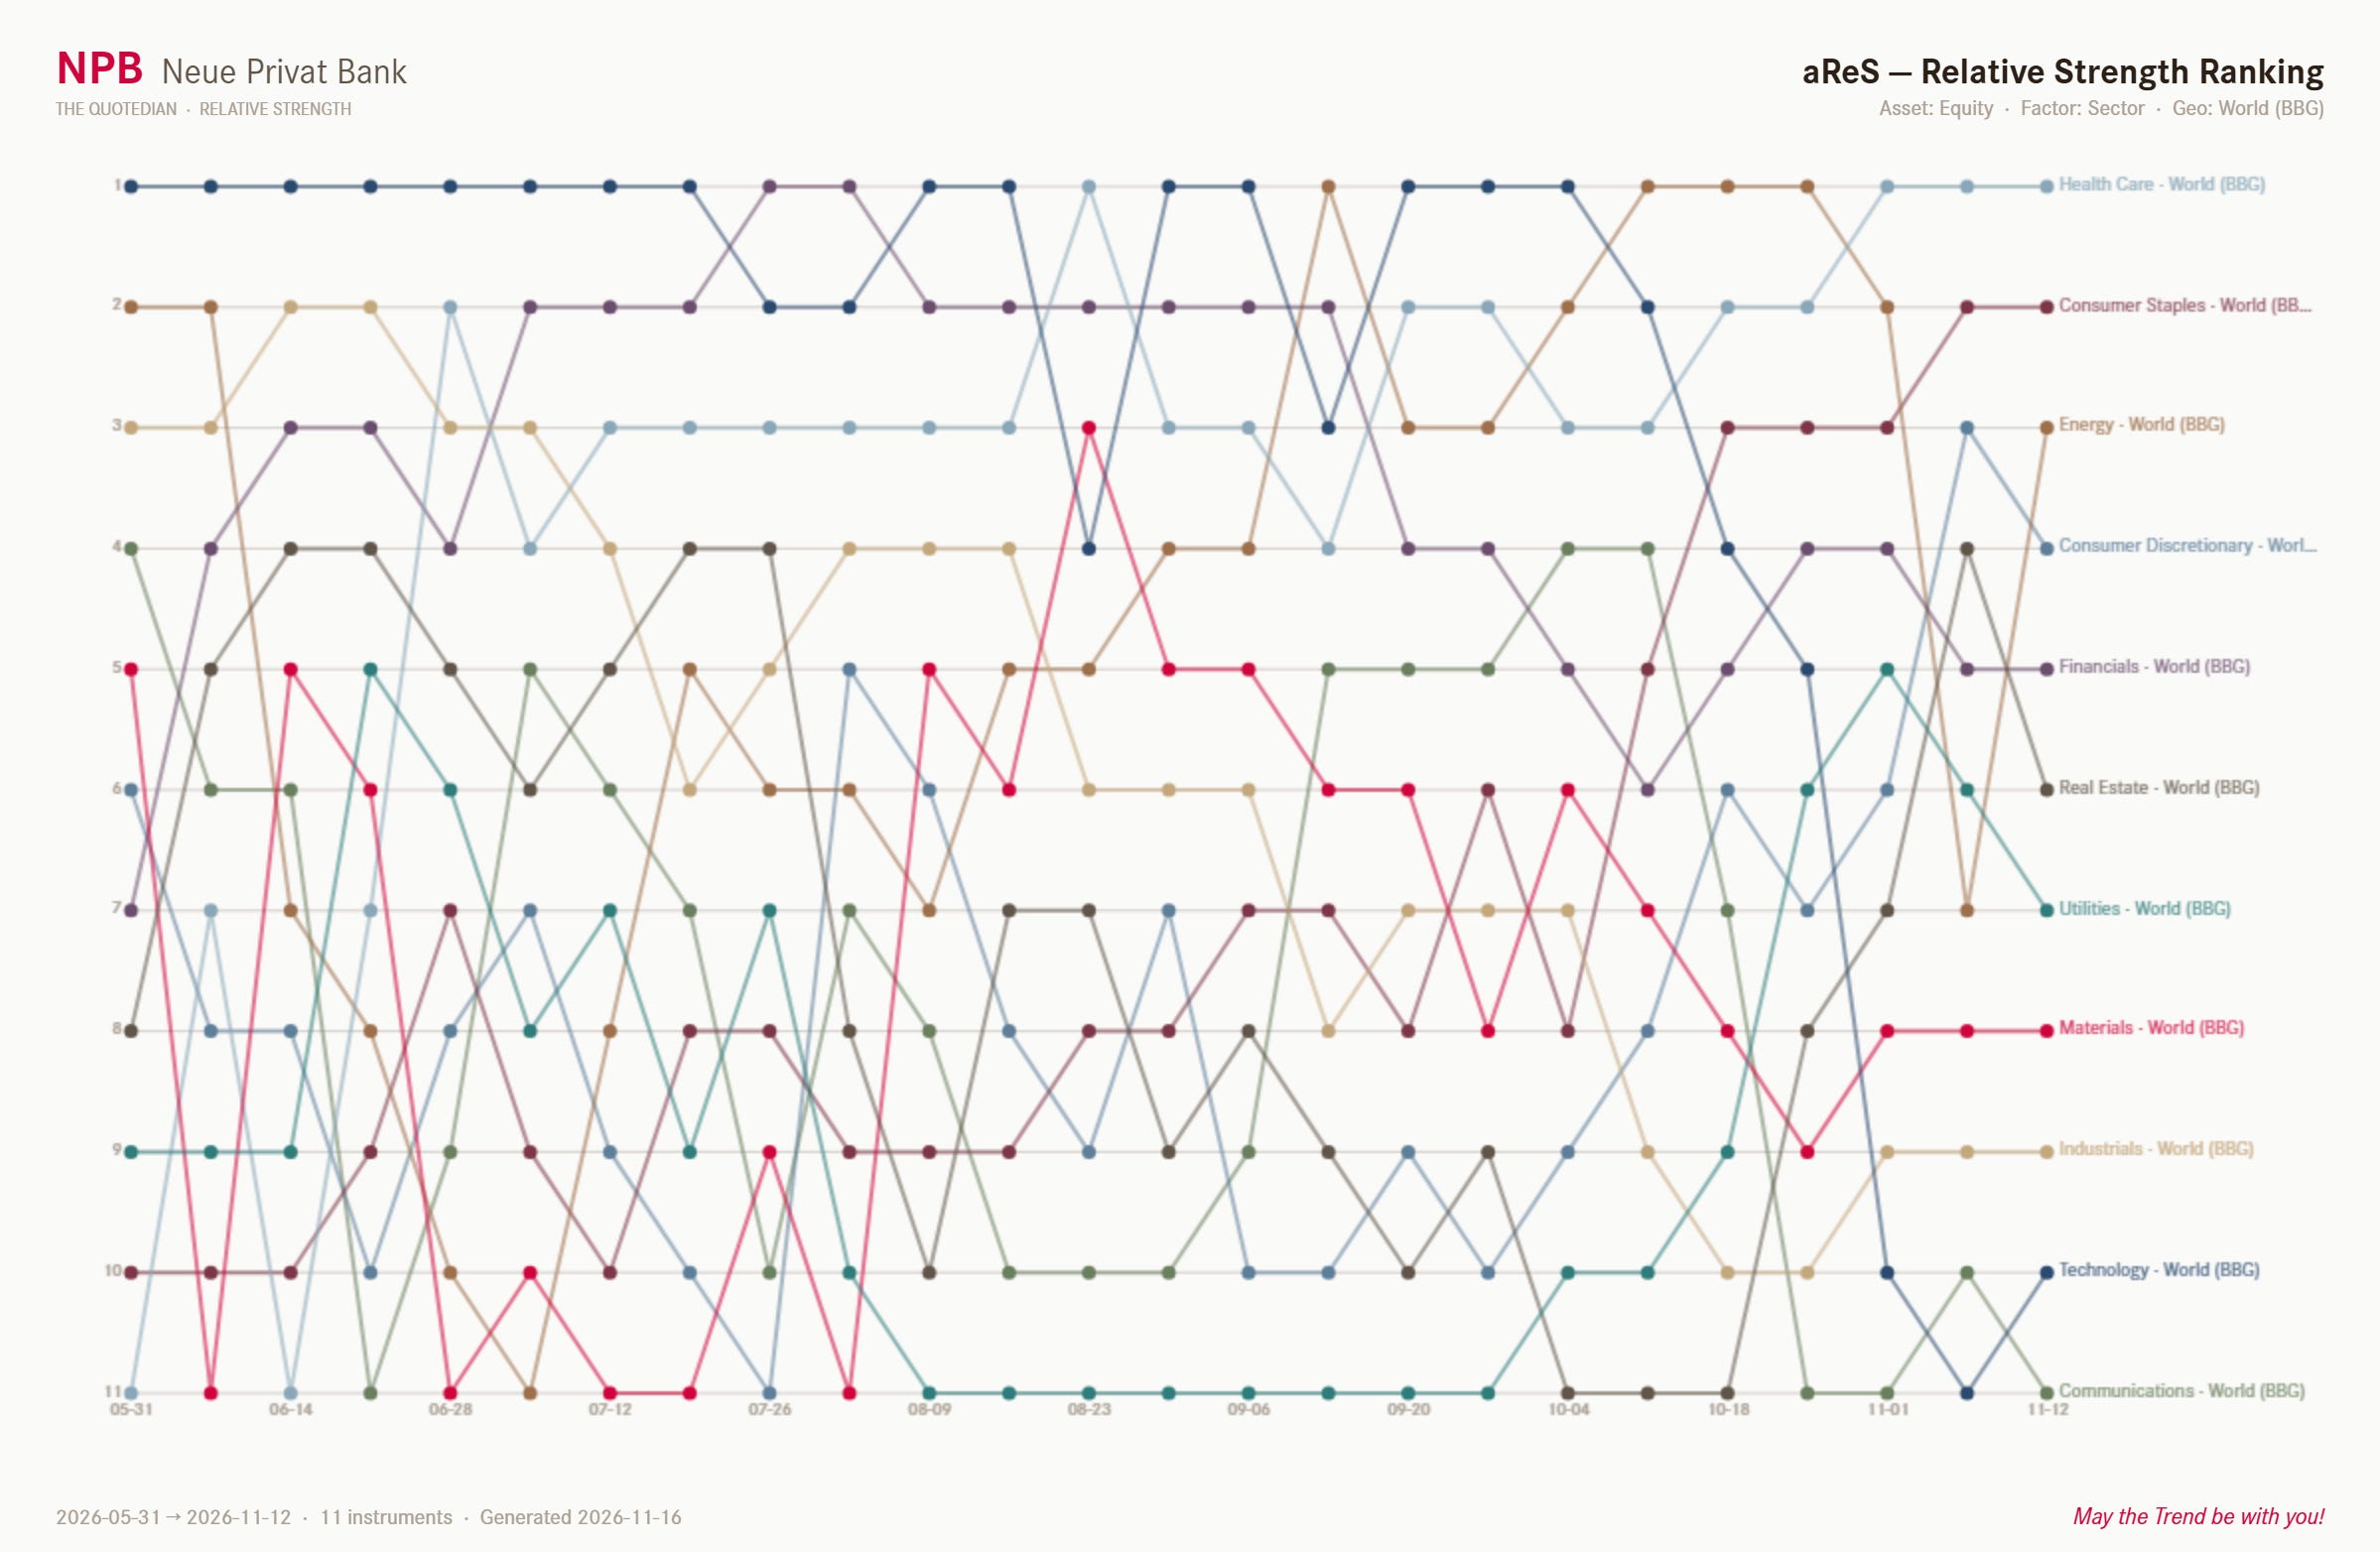
Our proprietary aReS™ model now has health care as number one sector, followed by consumer staples. And whilst energy has been able to reclaim third spot, tech and communication stocks have completely lost their shine:
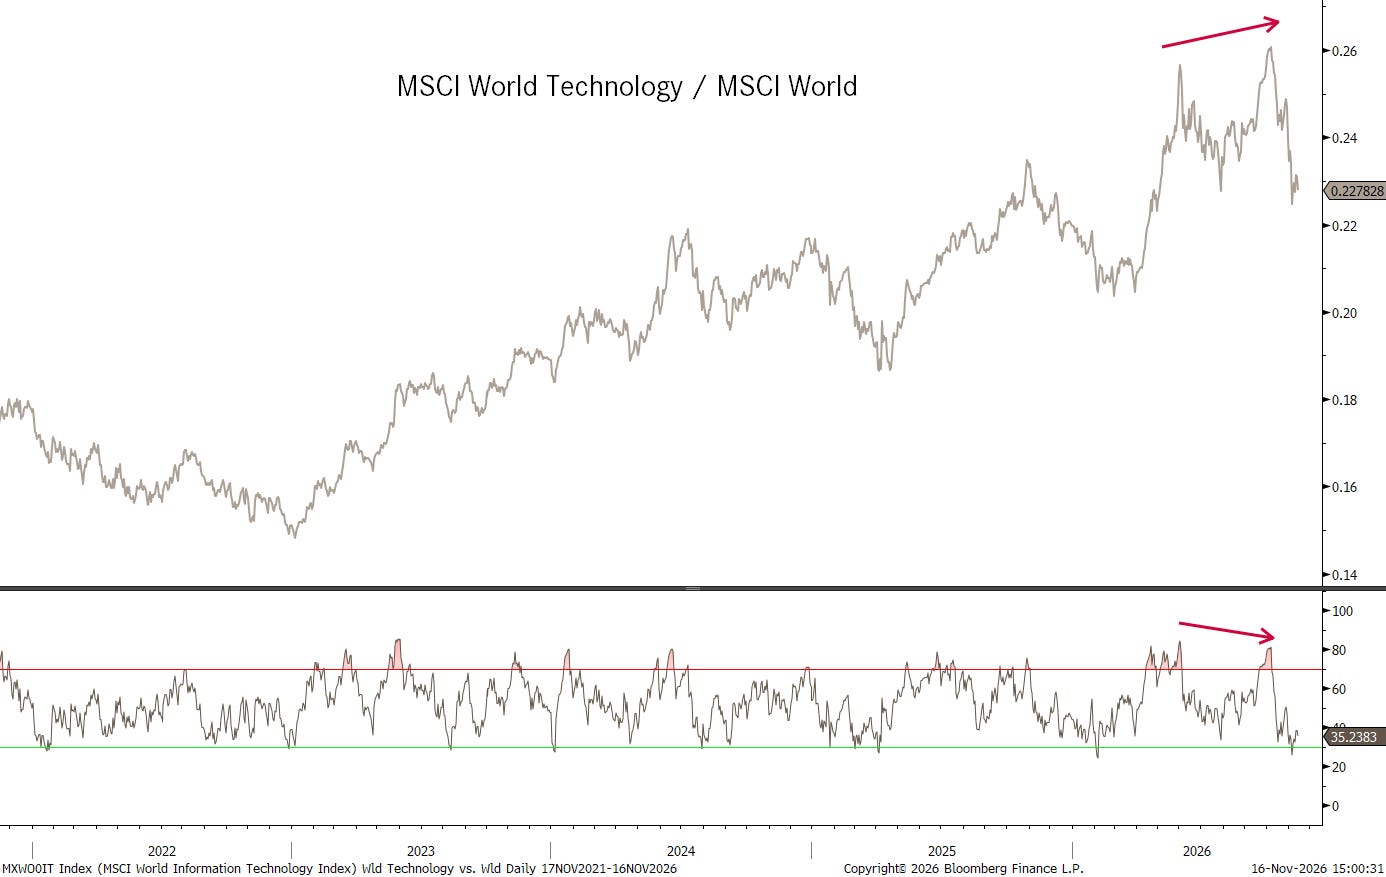
Have we seen a secular “double-top” in technology relative outperformance?
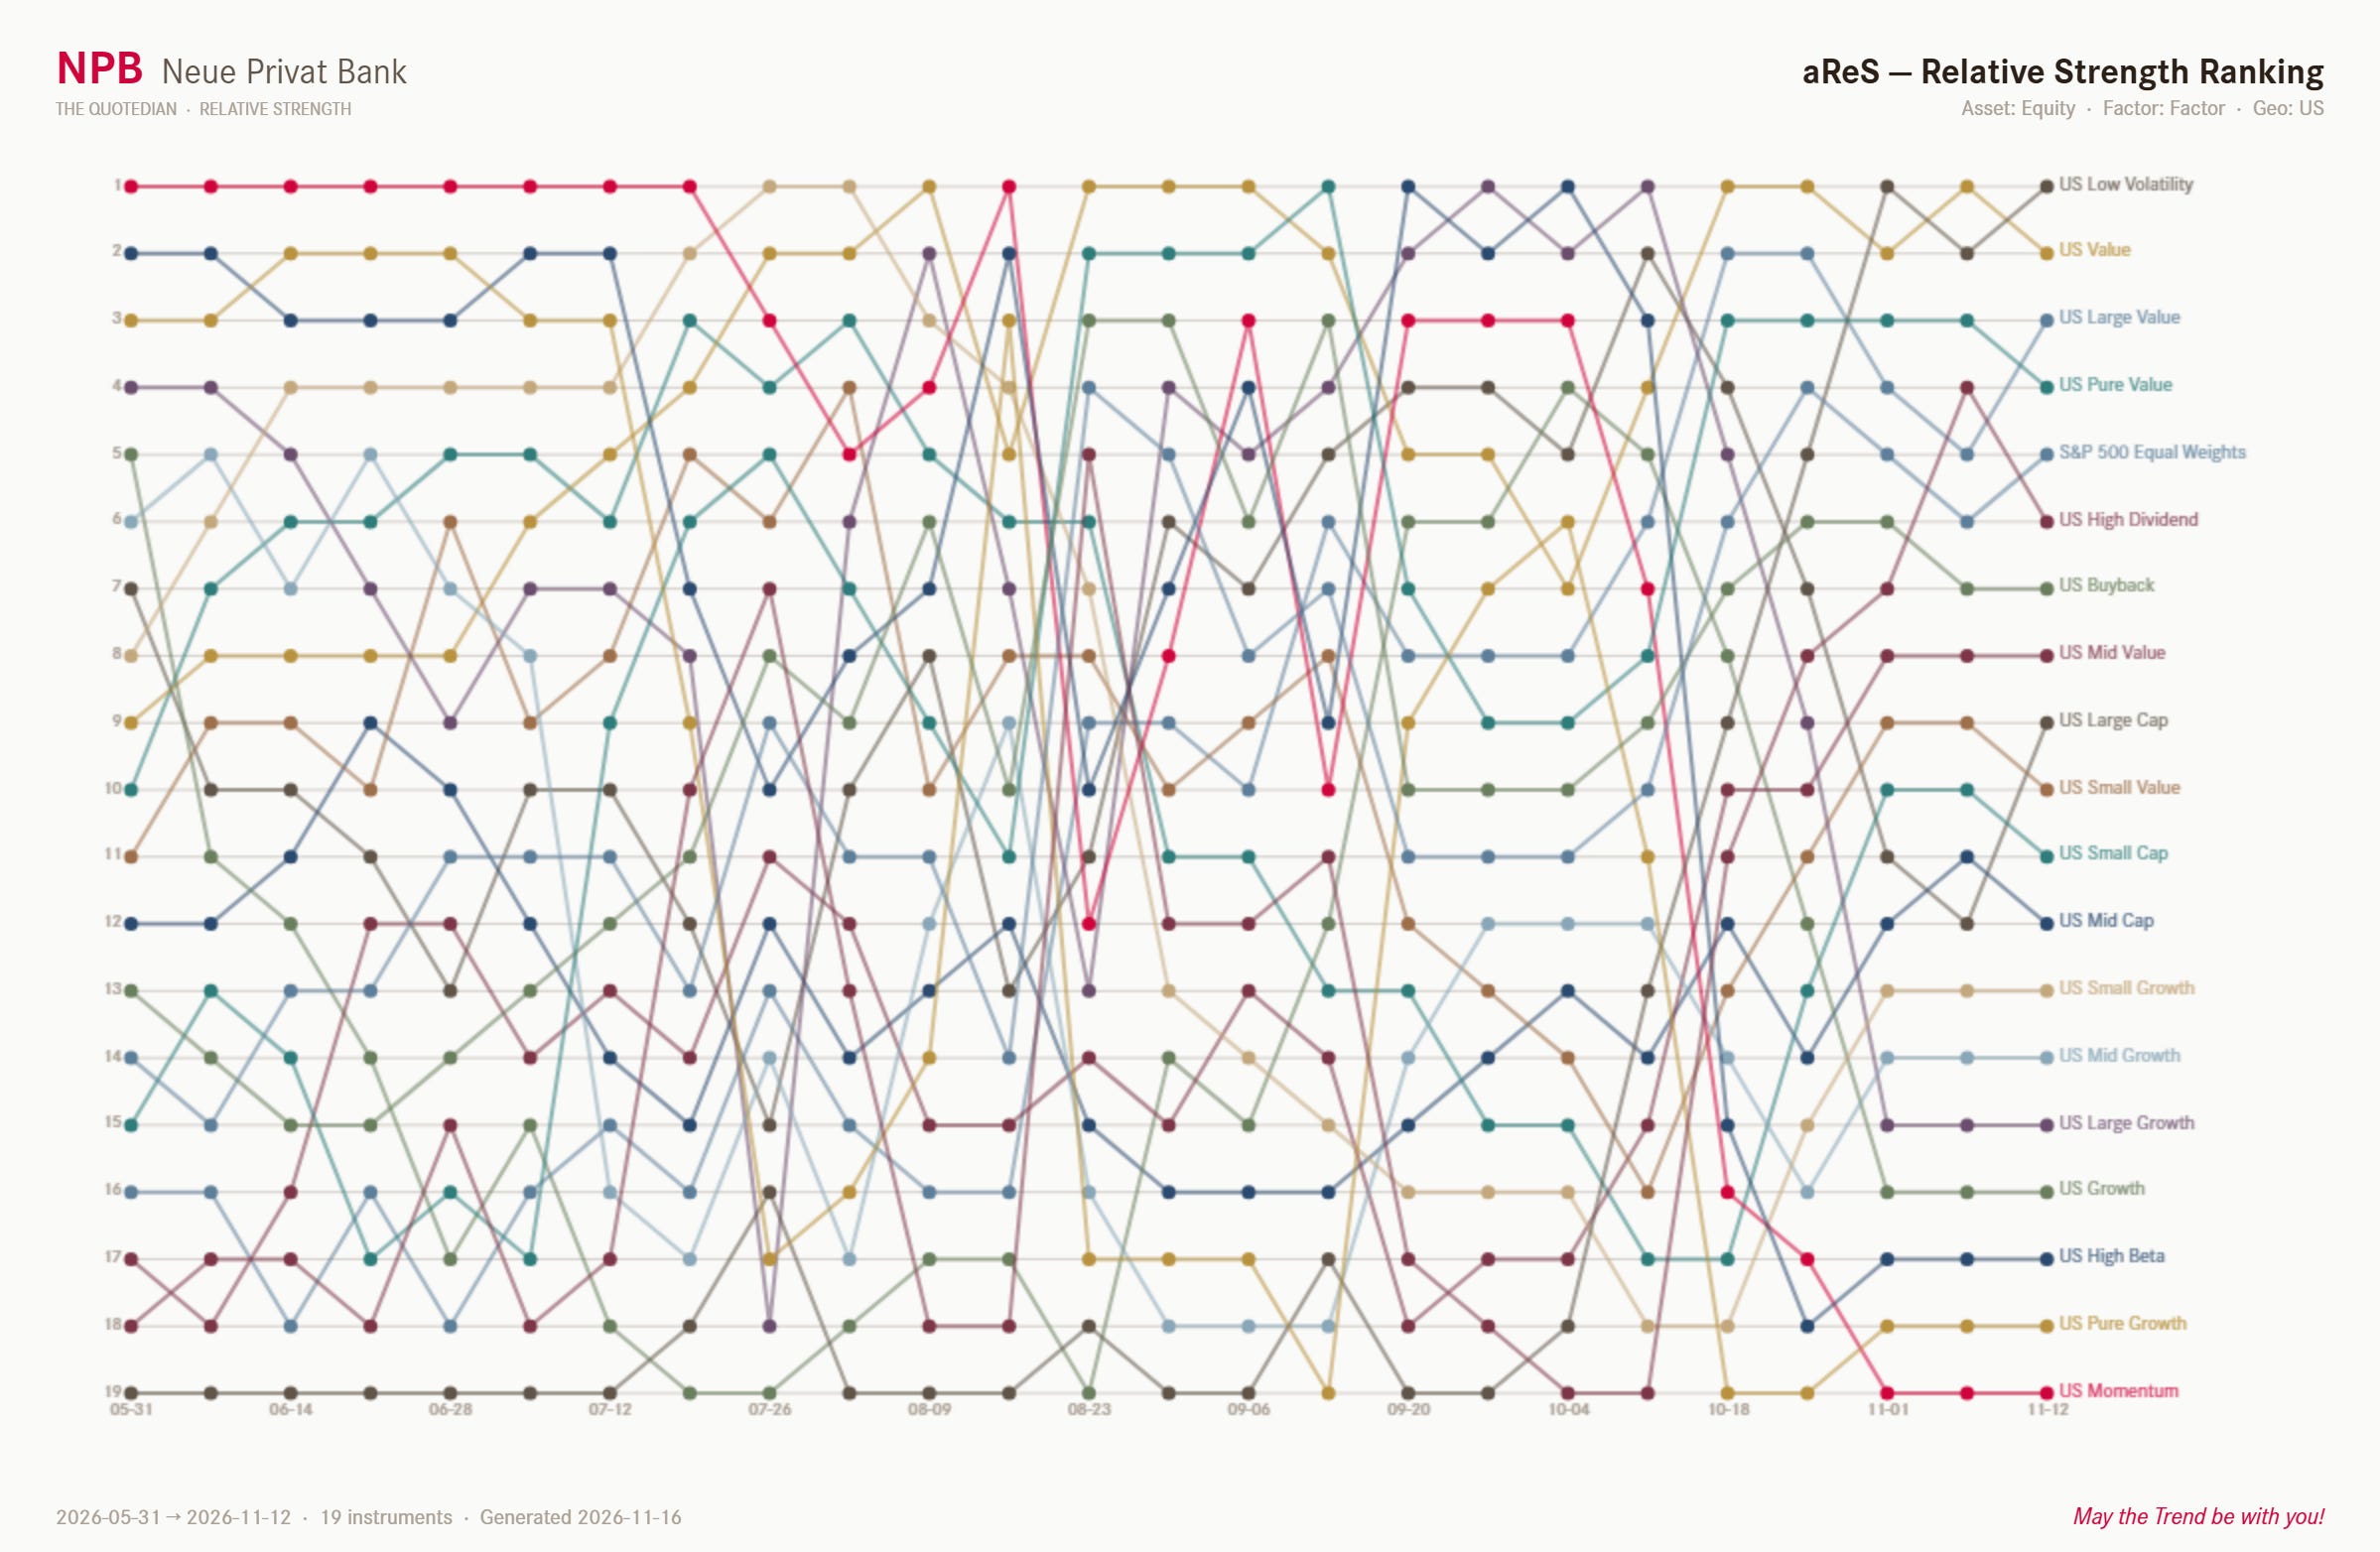
In terms of factor selection, our aReS™ model shows that several measures of value are in the top quartile of the ranking table:
Could it really be?
Is it really possible?
Has the time for prolonged outperformance of value over growth arrived?
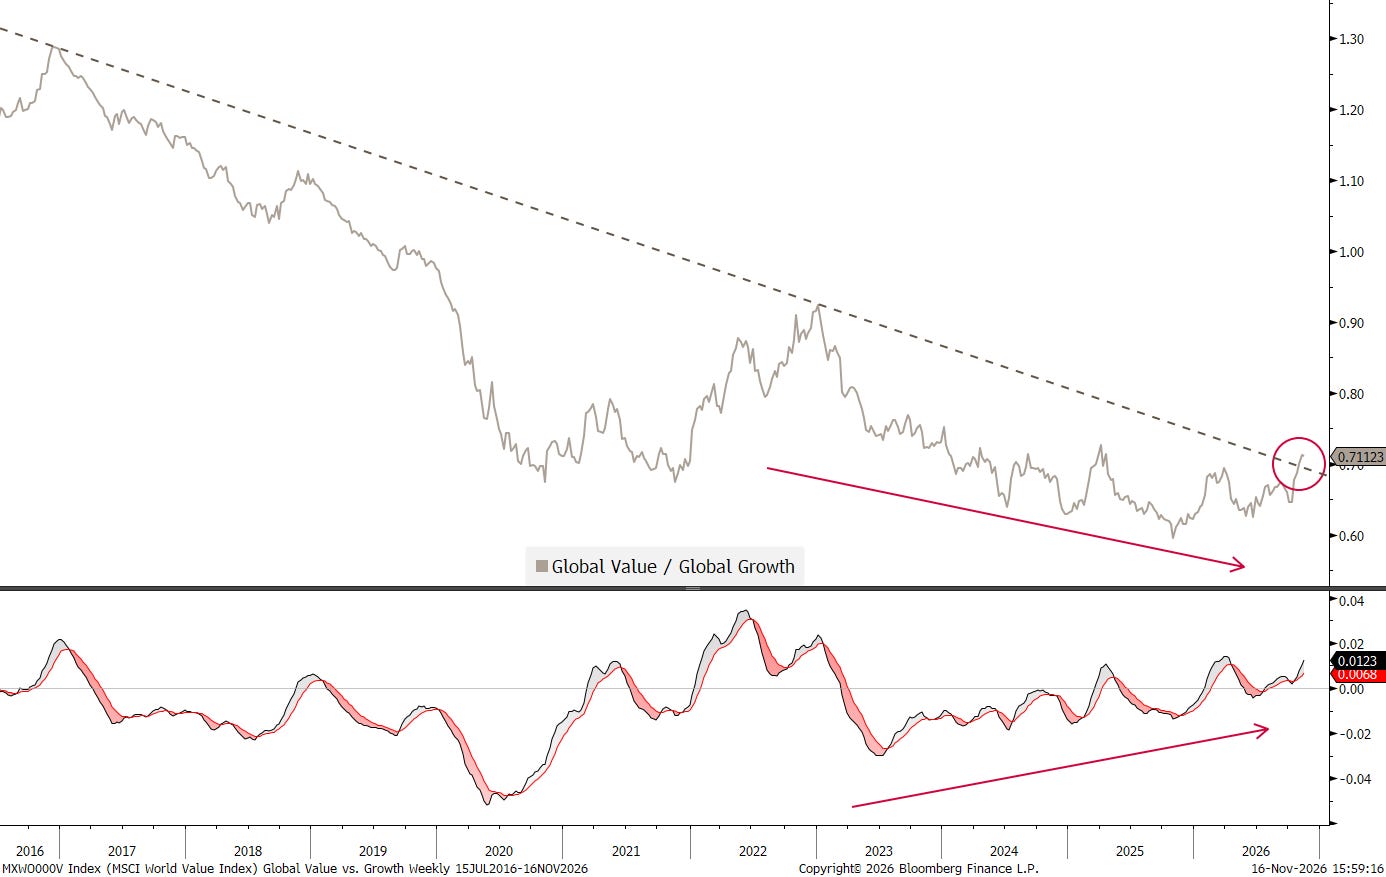
Perhaps.
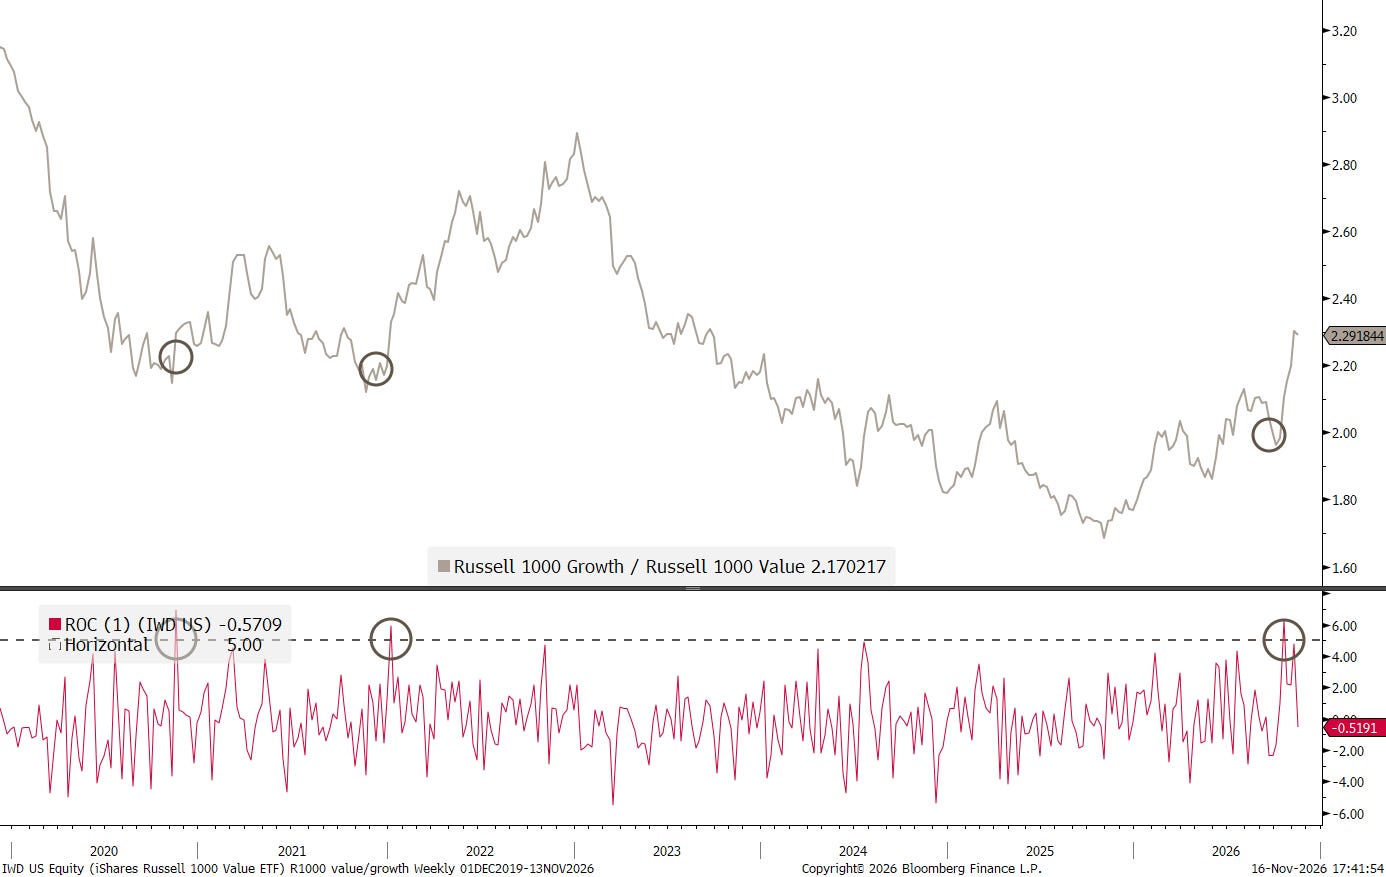
A good sign is that this decade, whenever the one-week rate of change on the Russell 1000 Value/Growth ratio exceeded five percent, it was a good time to remain on the long value side:
Time to roll over into the fixed income space, where we start with credit first.
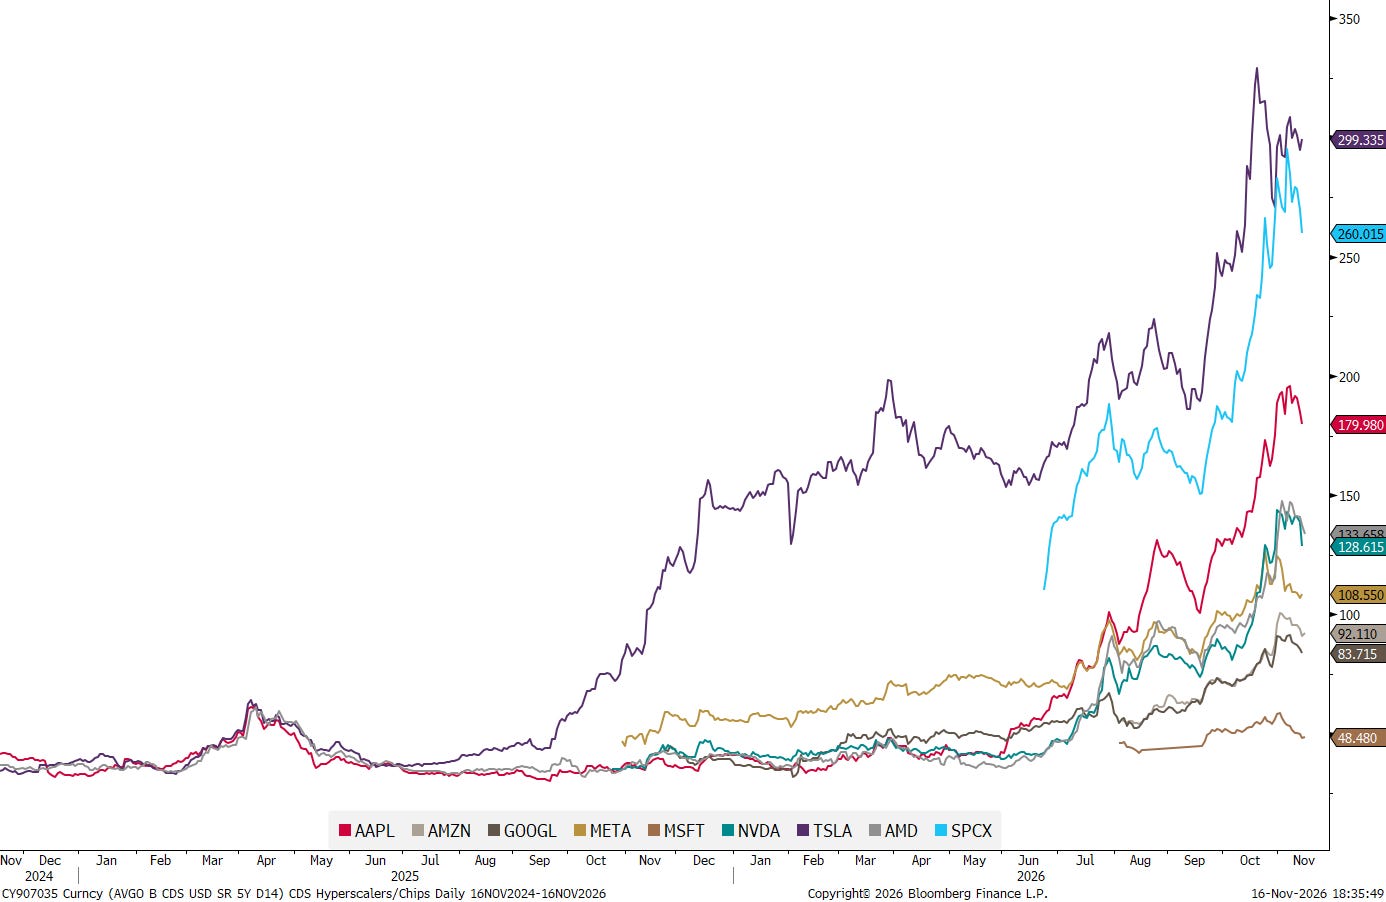
Investors are getting increasingly nervous about the hyperscalers and chipmakers finances, as shown via their rising five year Credit Default Swap (CDS) rates:
Broader credit spread indices have started to tighten again with one important exception:
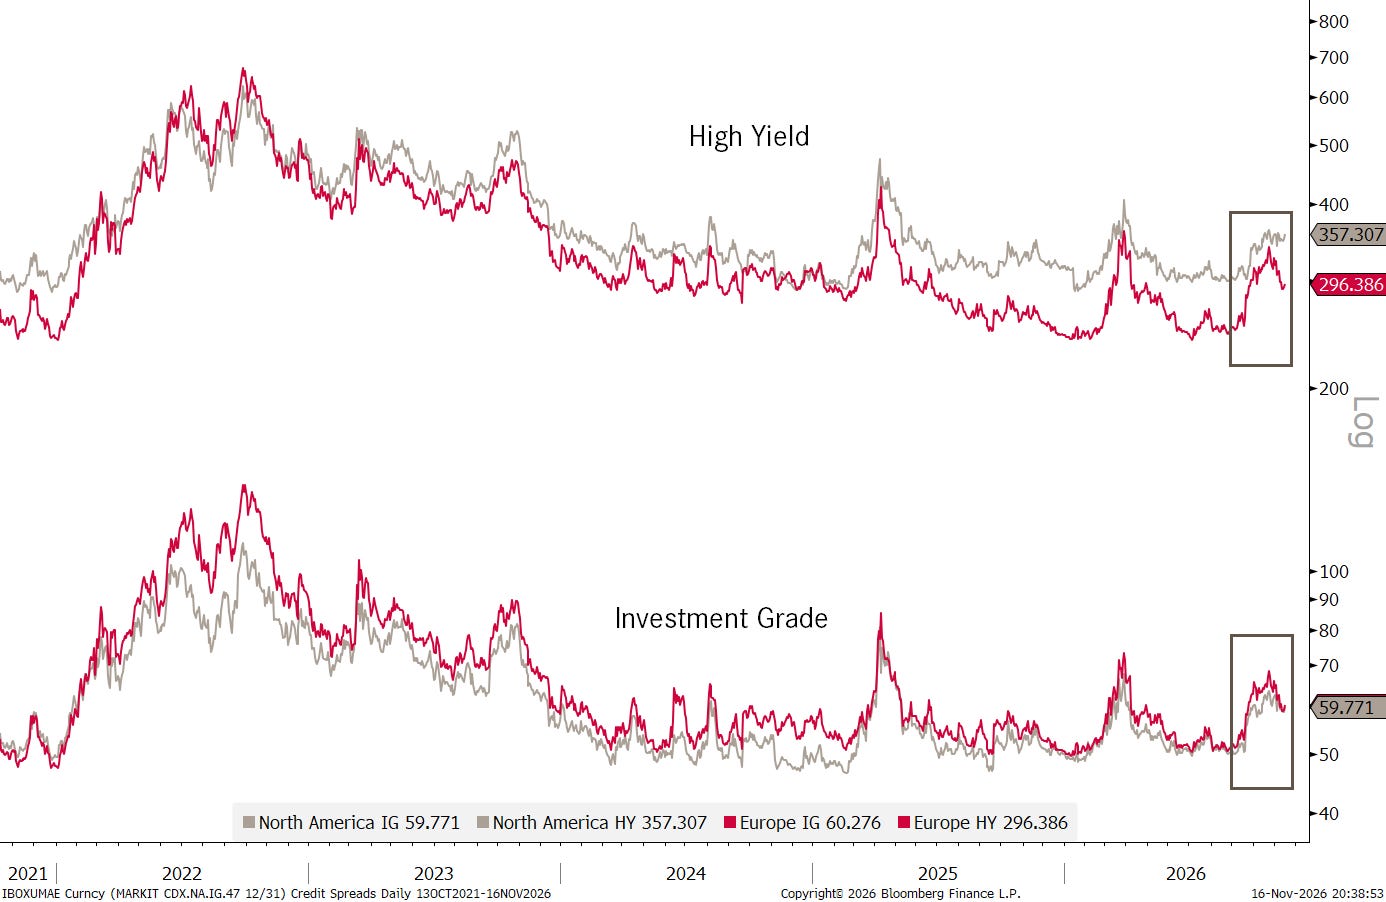
US High Yield!
US Treasury yields shifted higher last week after the CPI report was released on Monday:
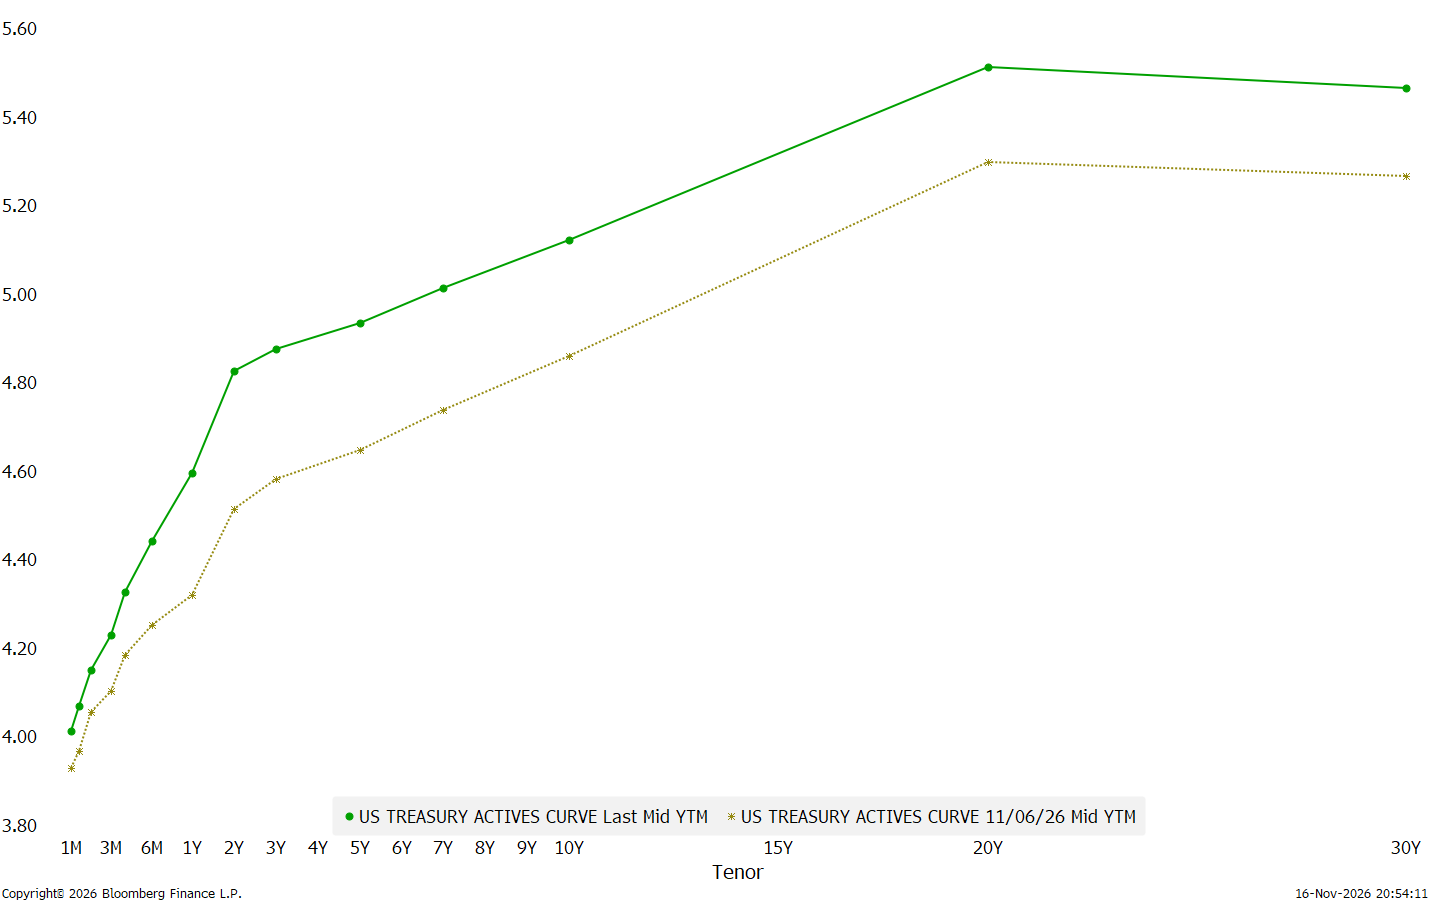
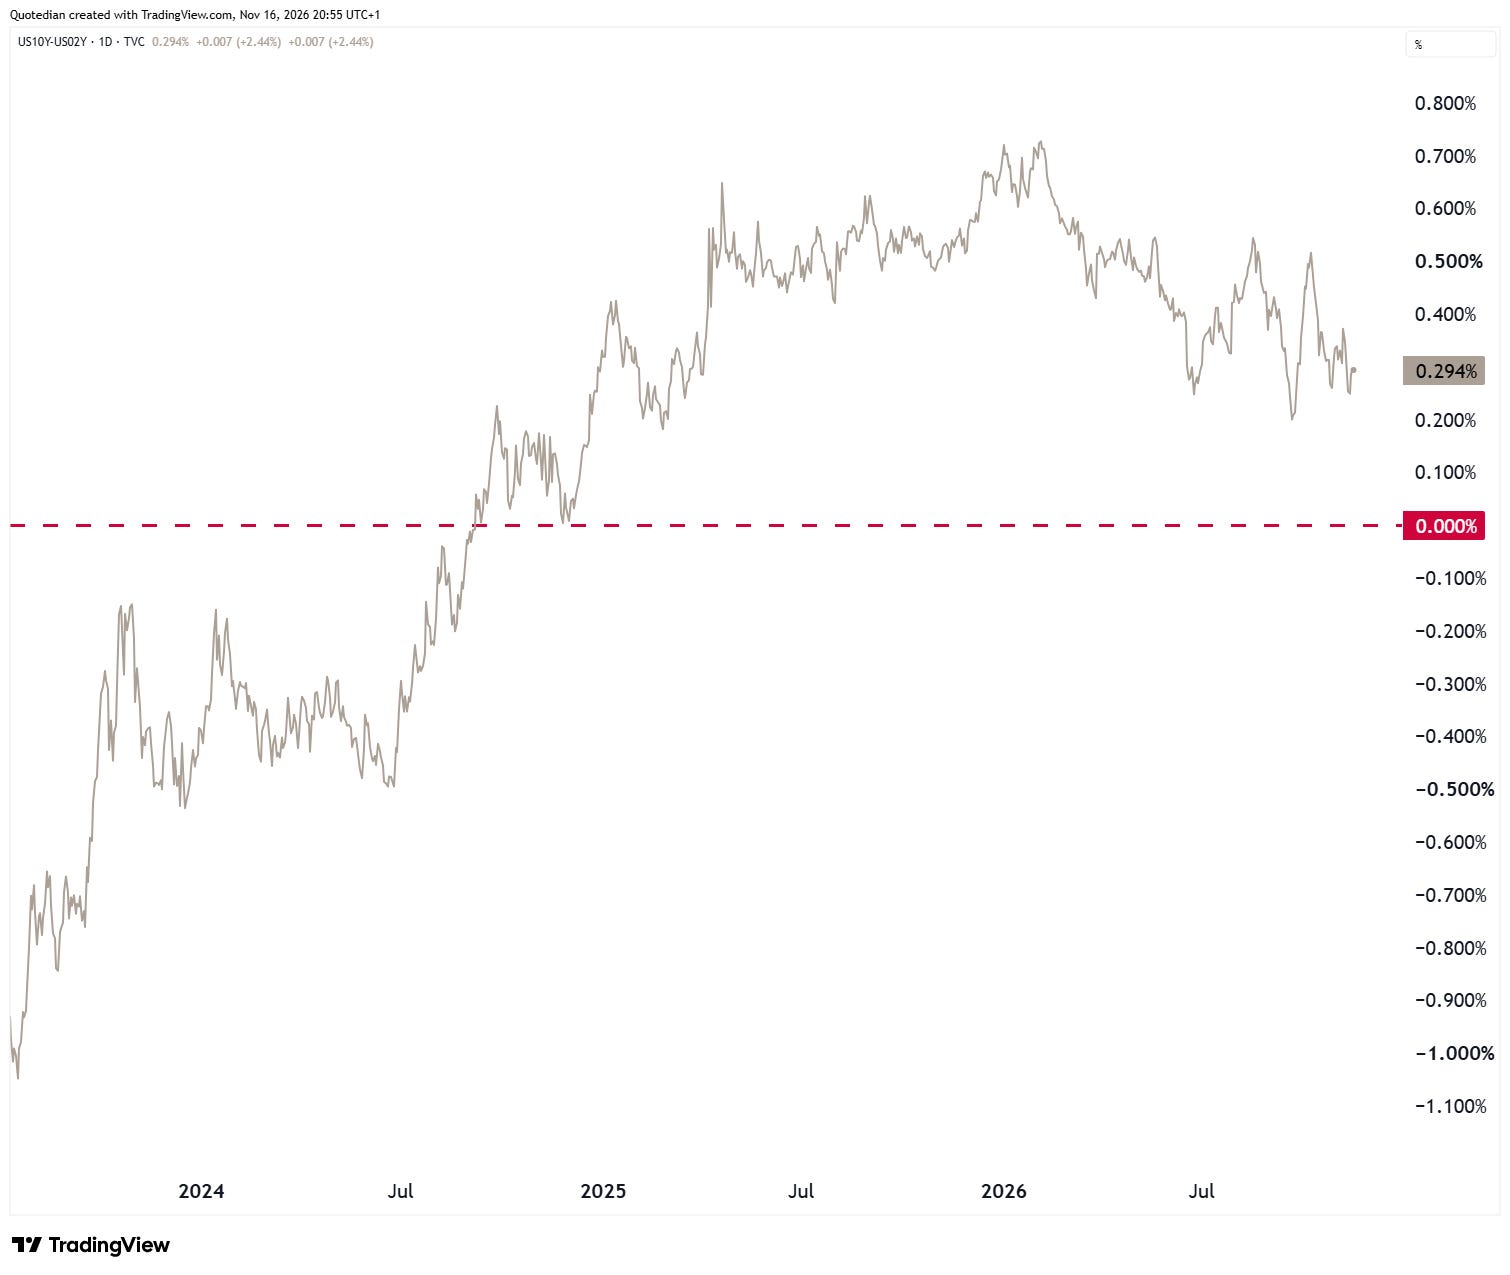
The move was a tad more pronounced at the long end, leading to some flattening of the yield curve (10y-2y):
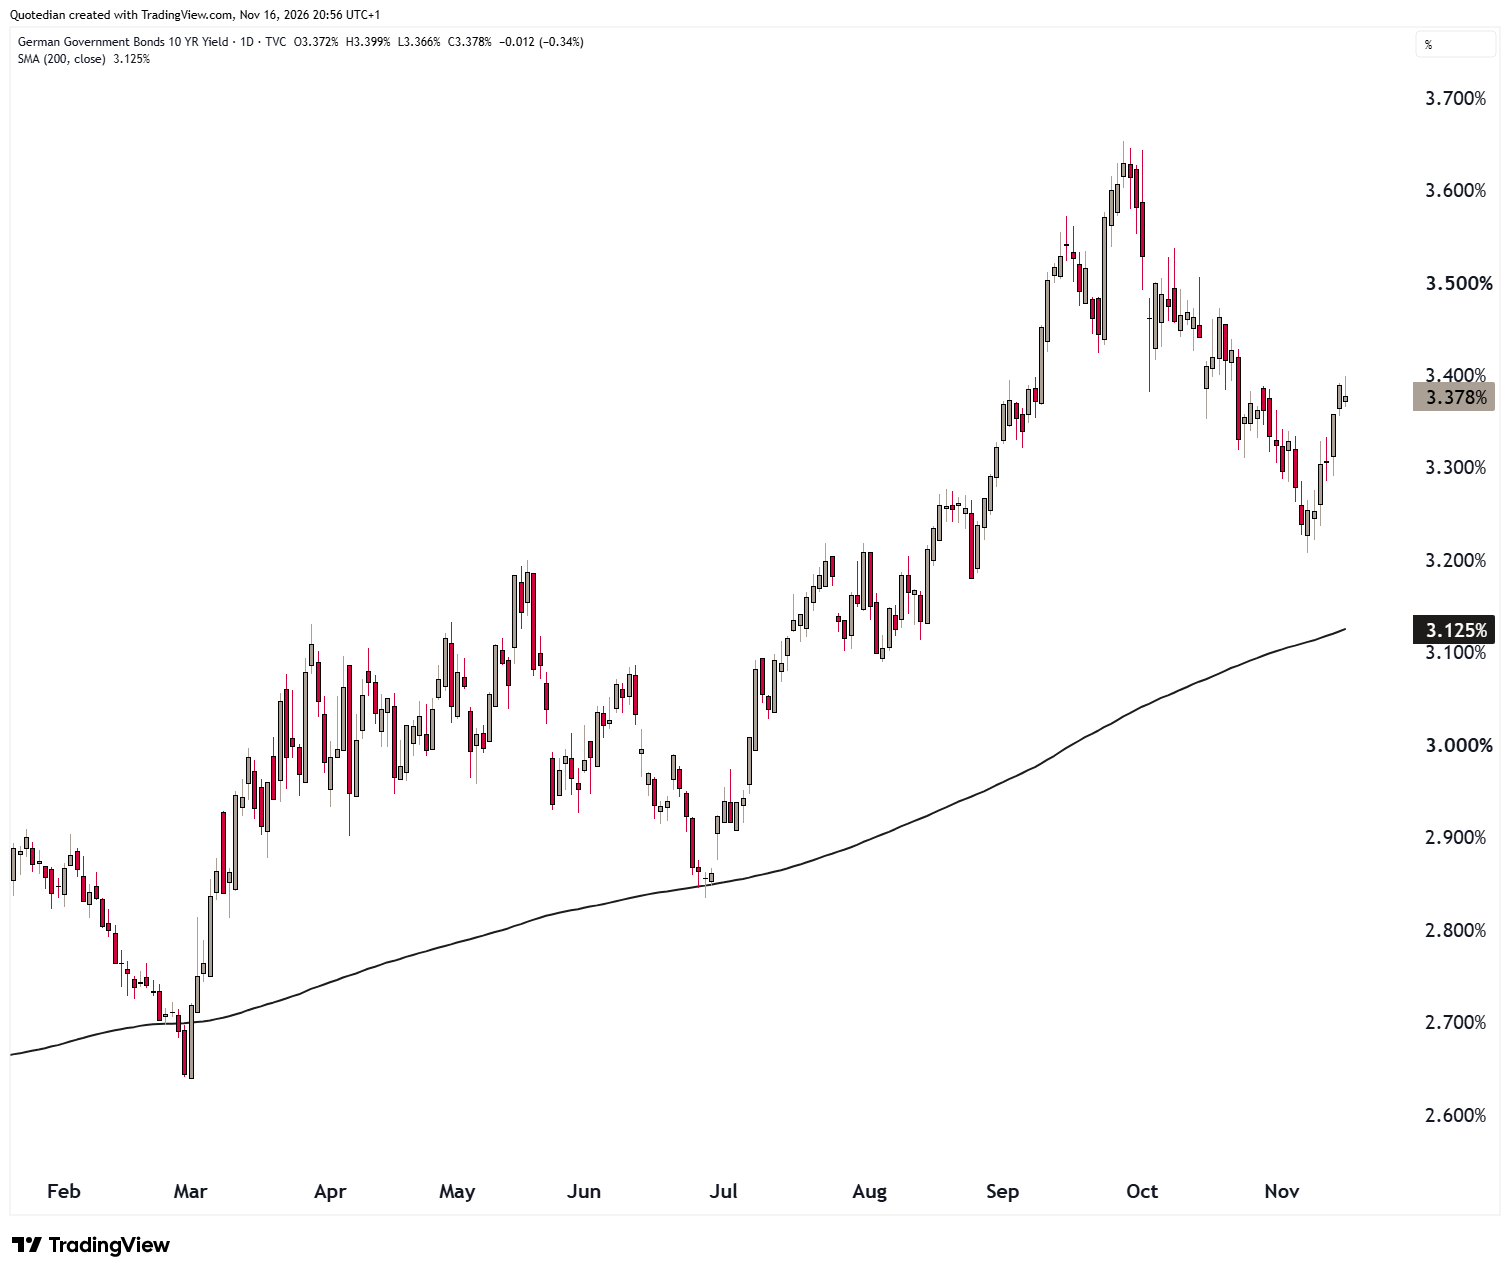
Eurozone yields, below proxied via the 10-year German Bund, moved higher too:
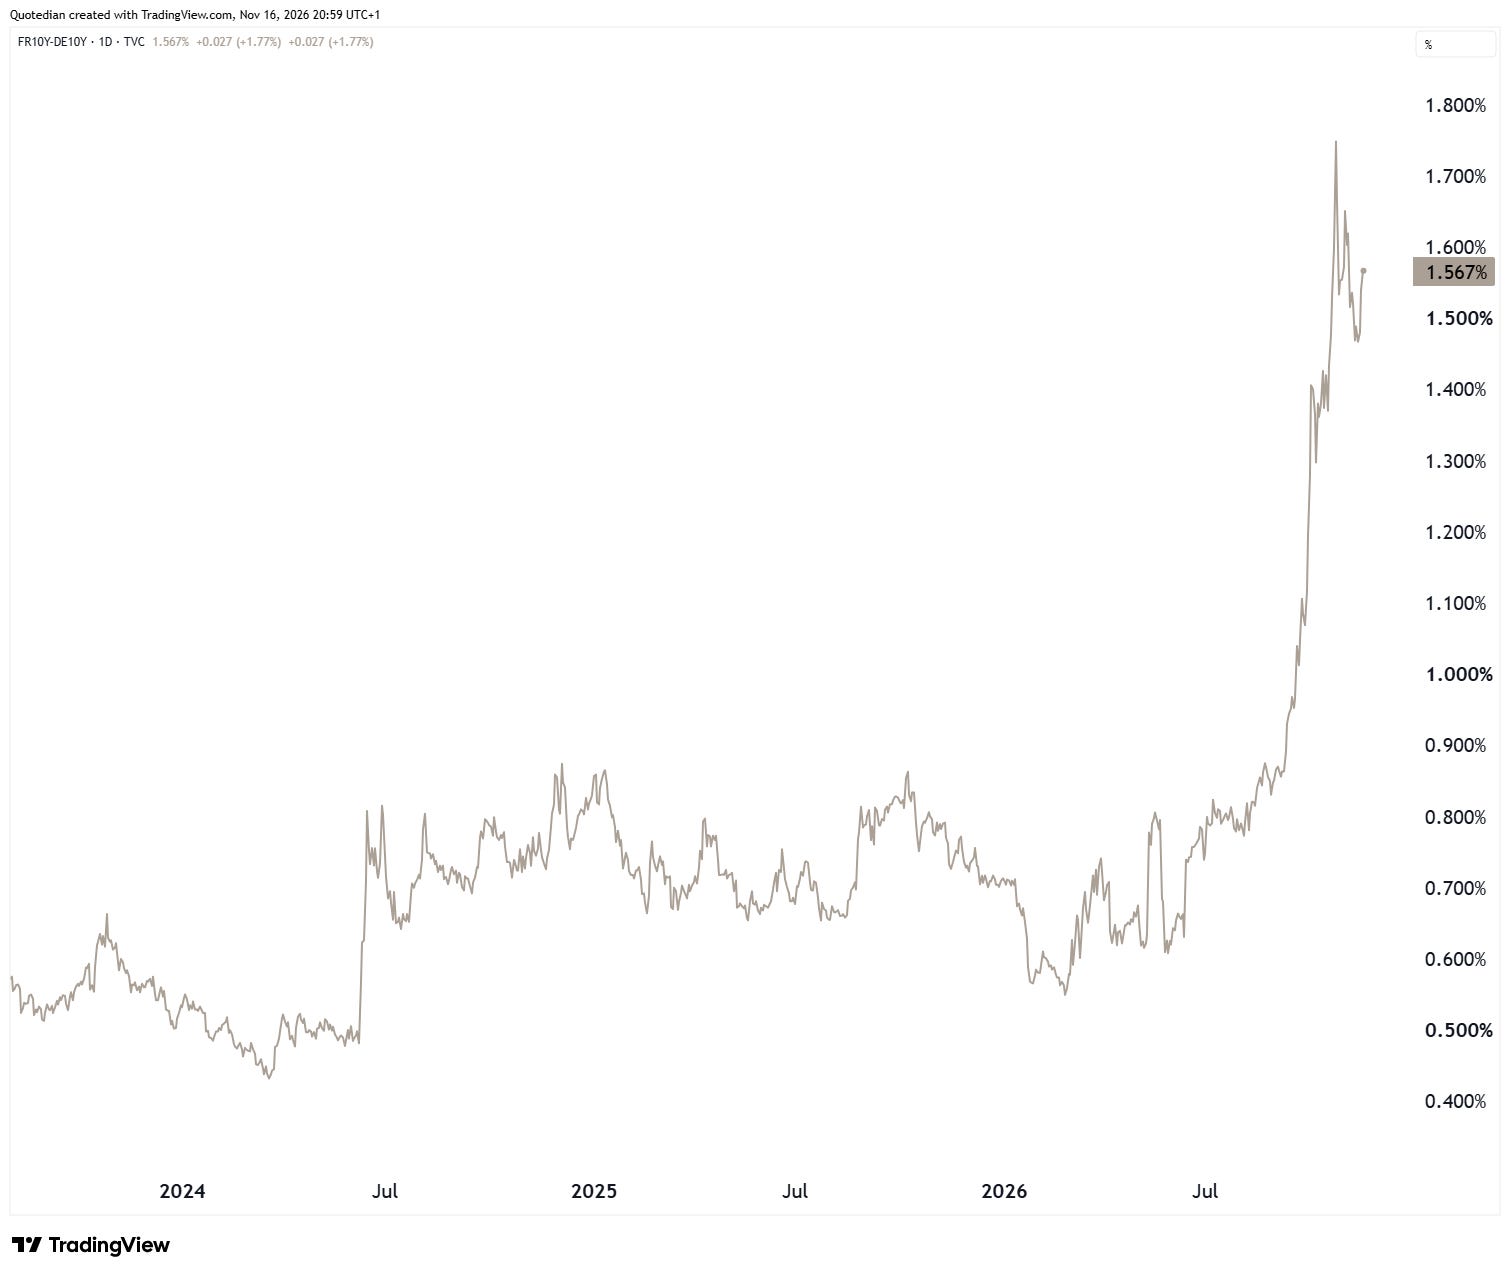
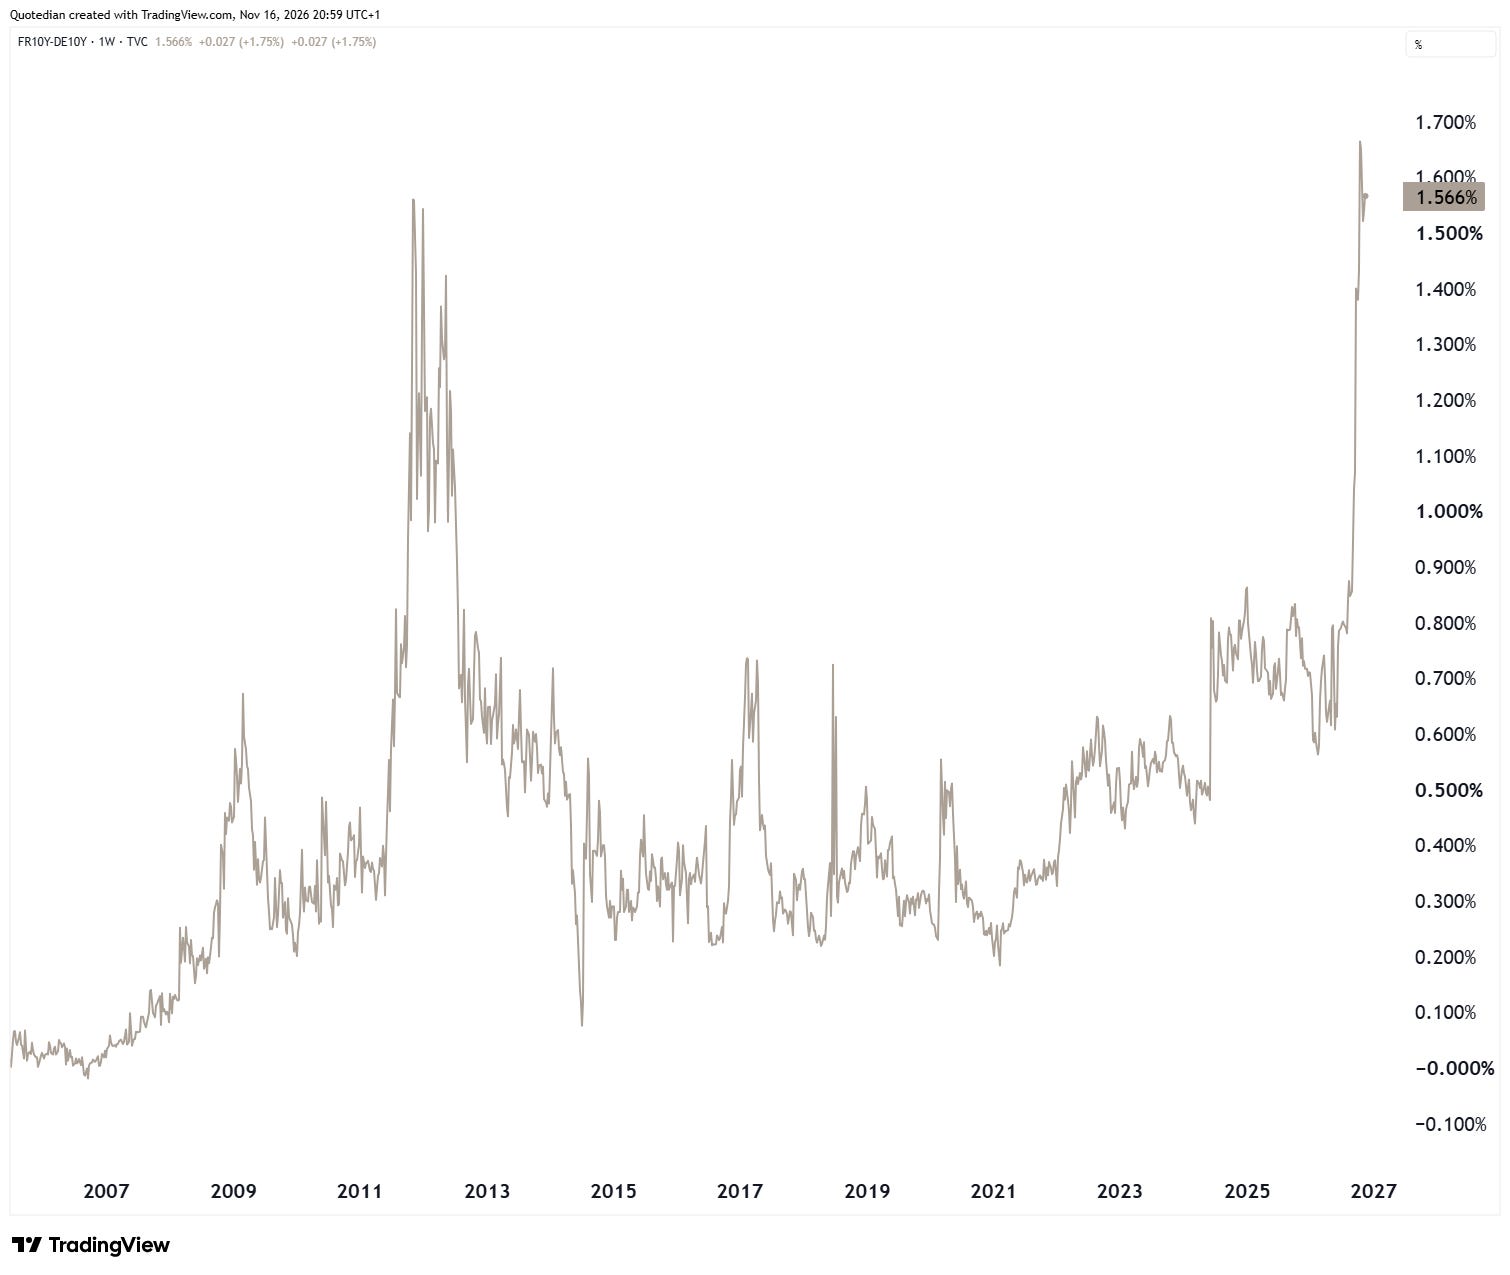
The alarm bells are still ringing on French OATs (below the Franco-German 10y yield spread):
As a reminder, the same chart again, but zooming out for context:
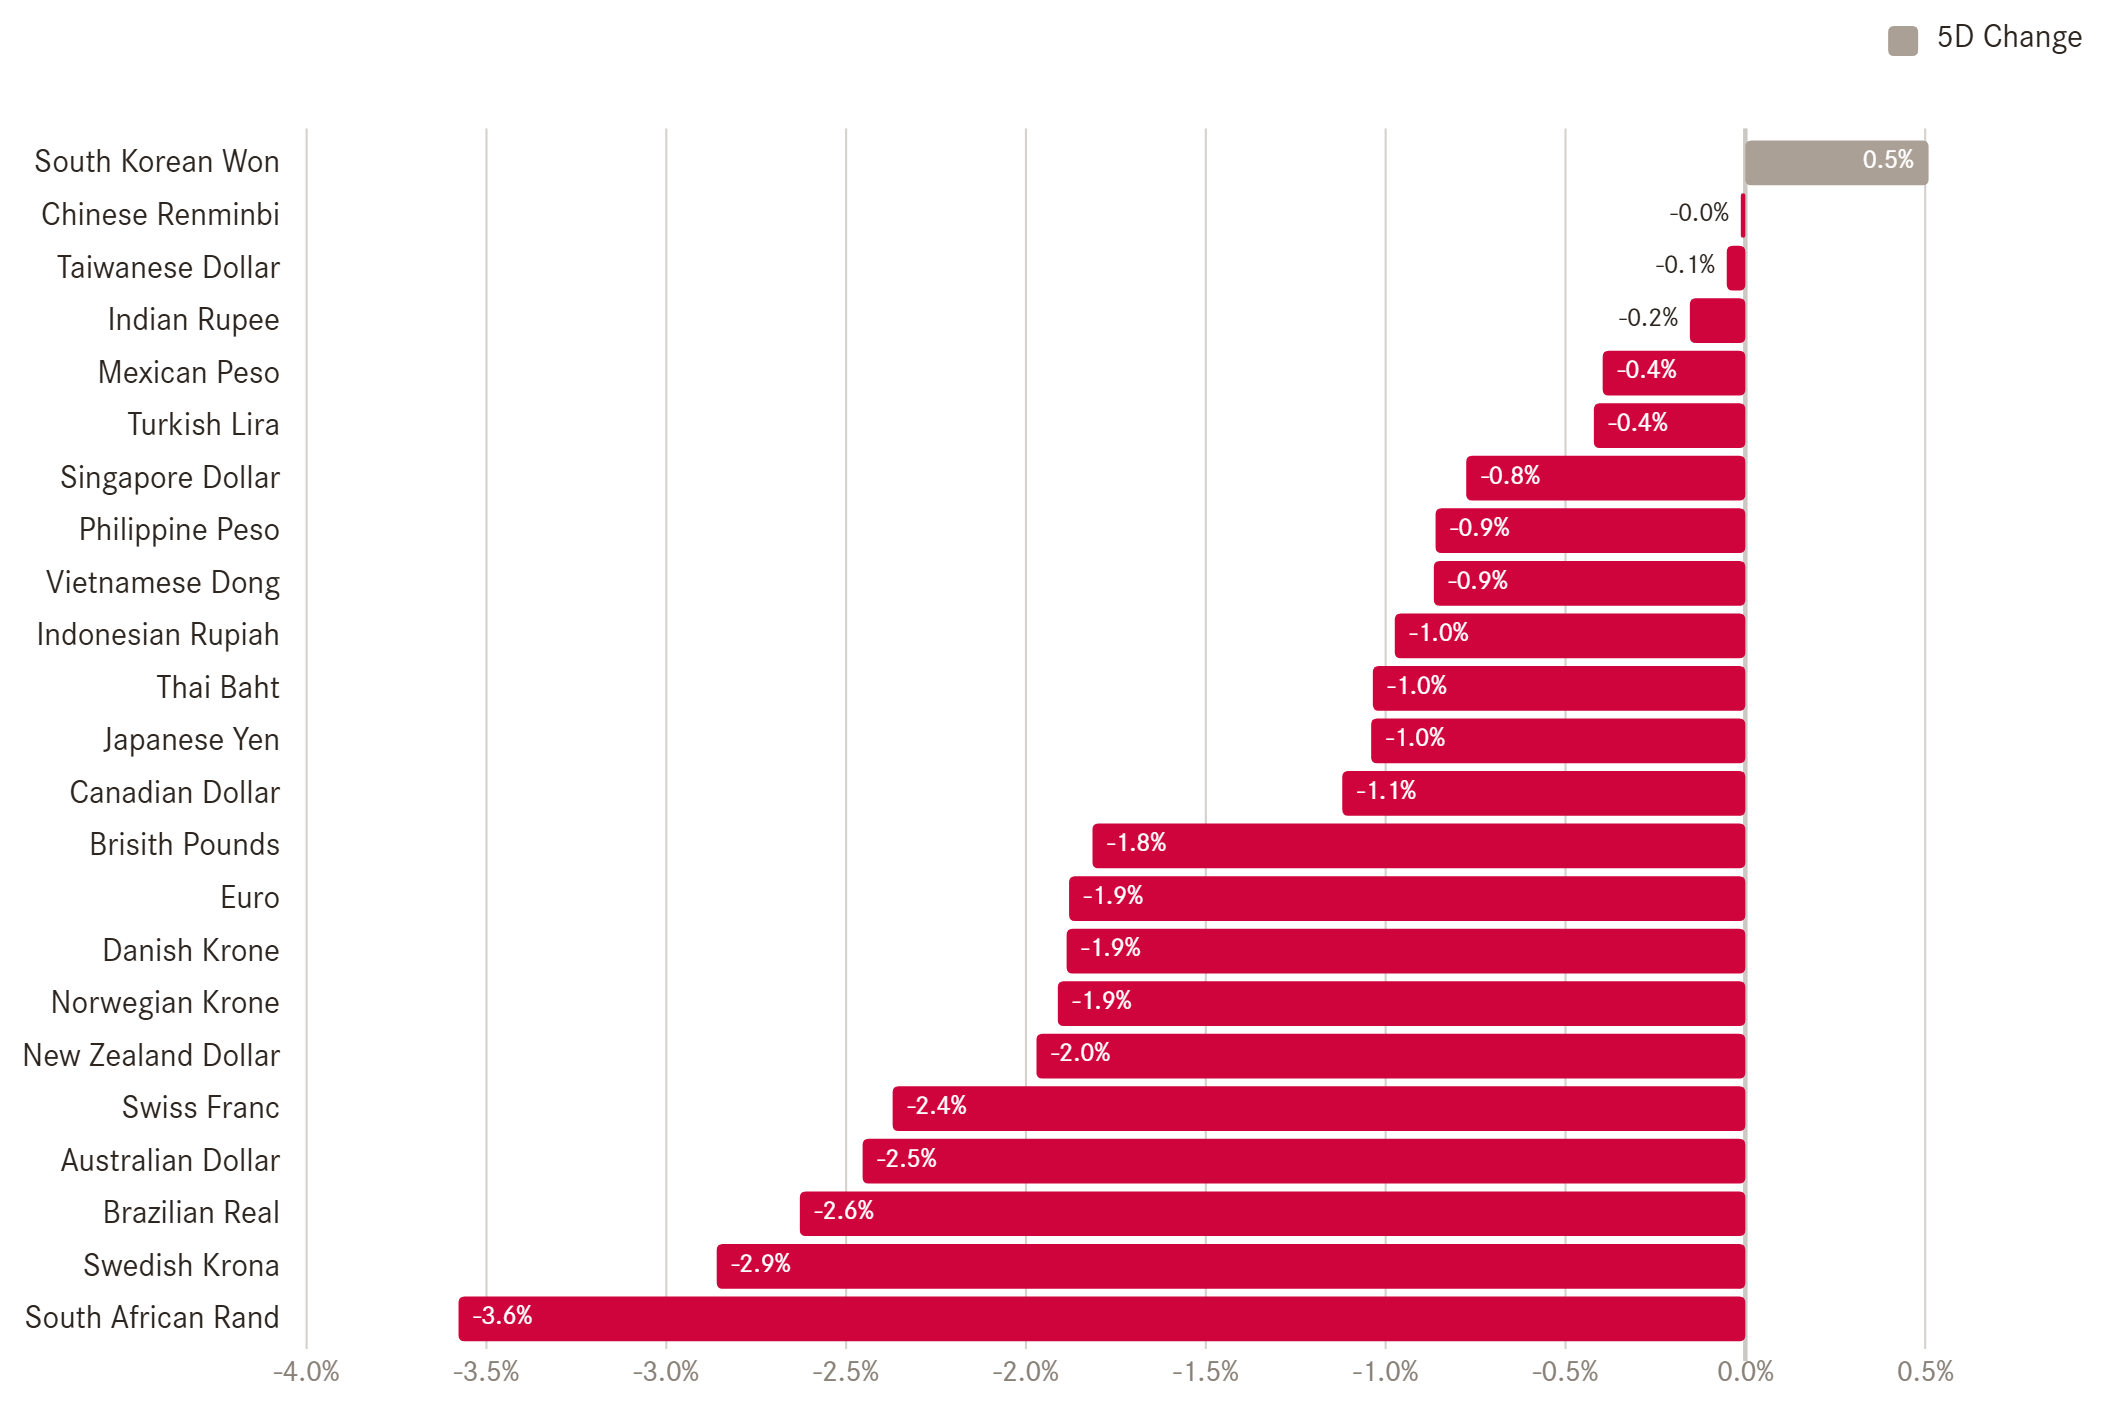
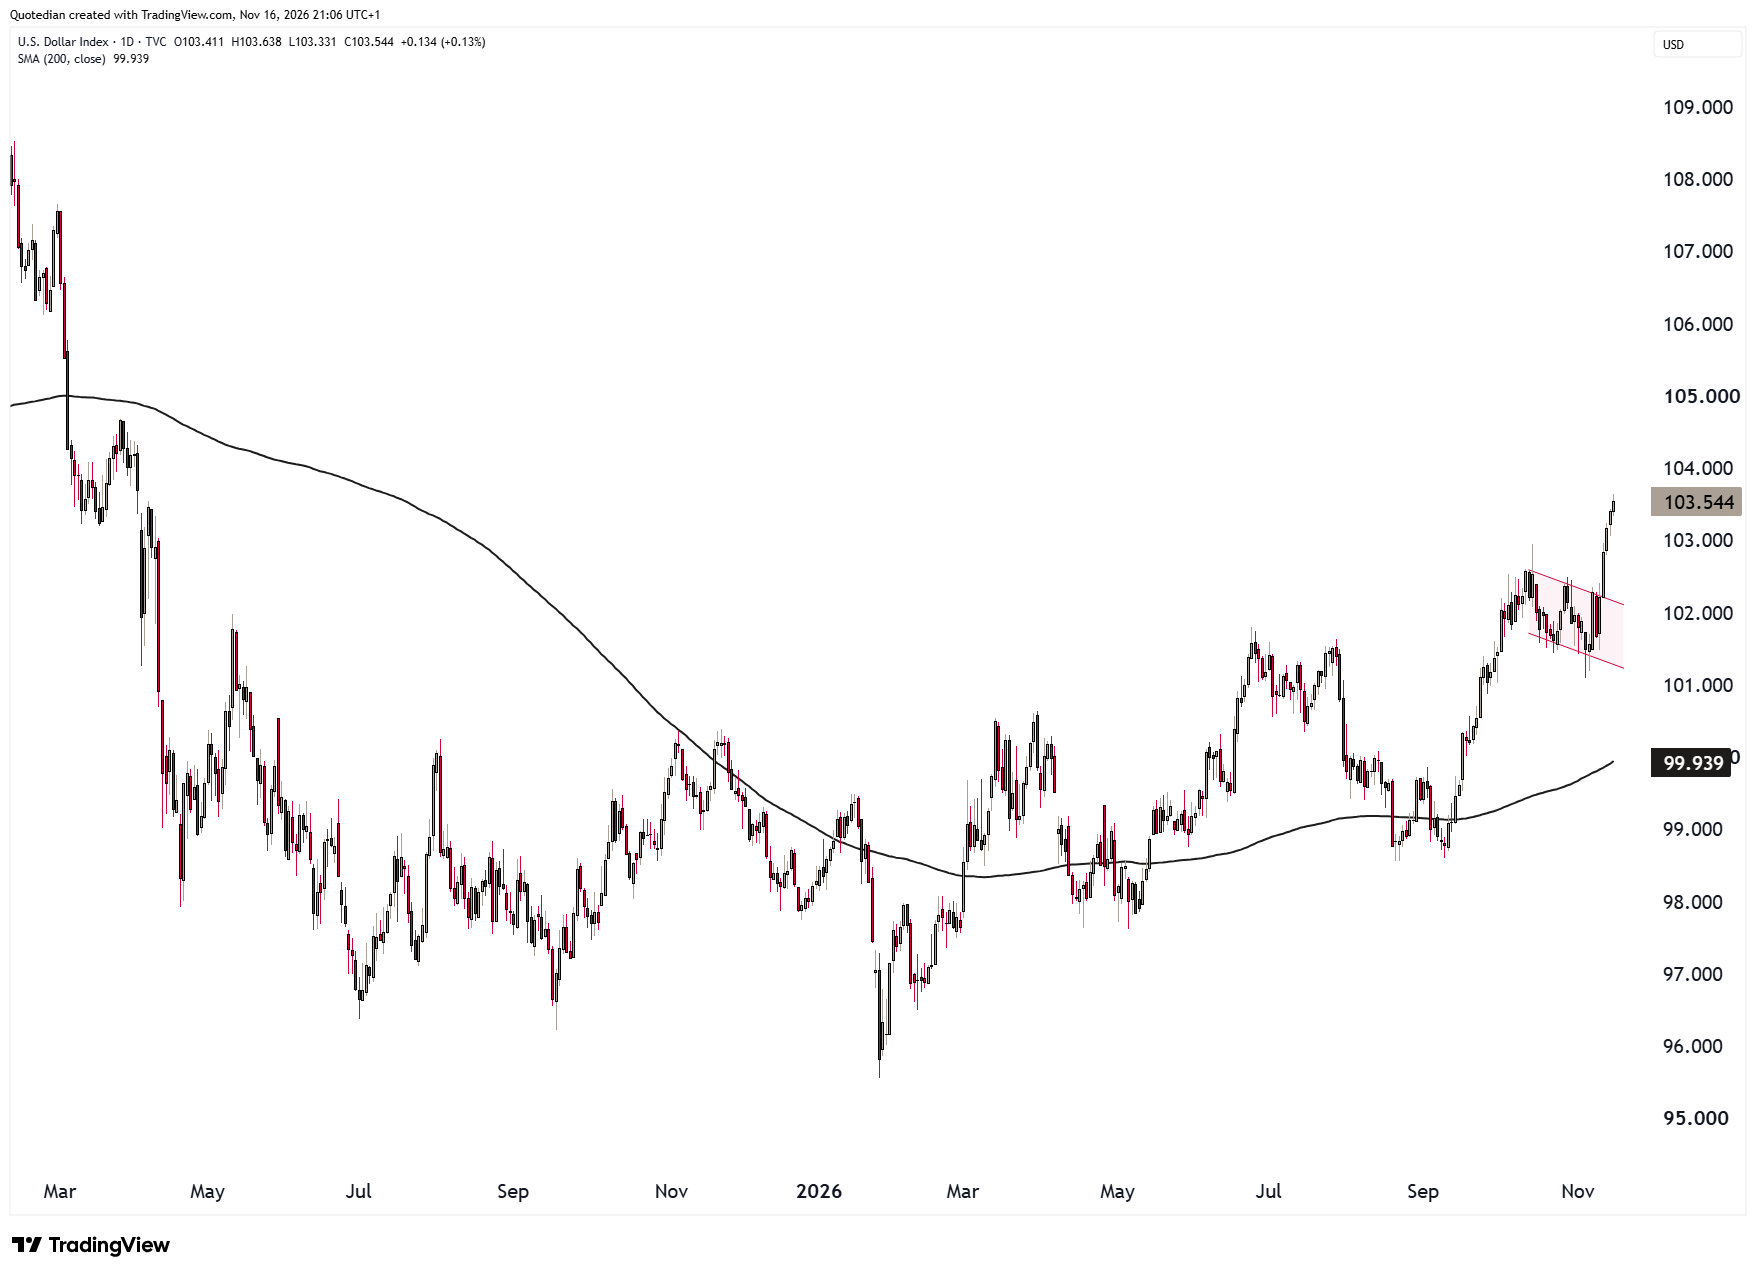
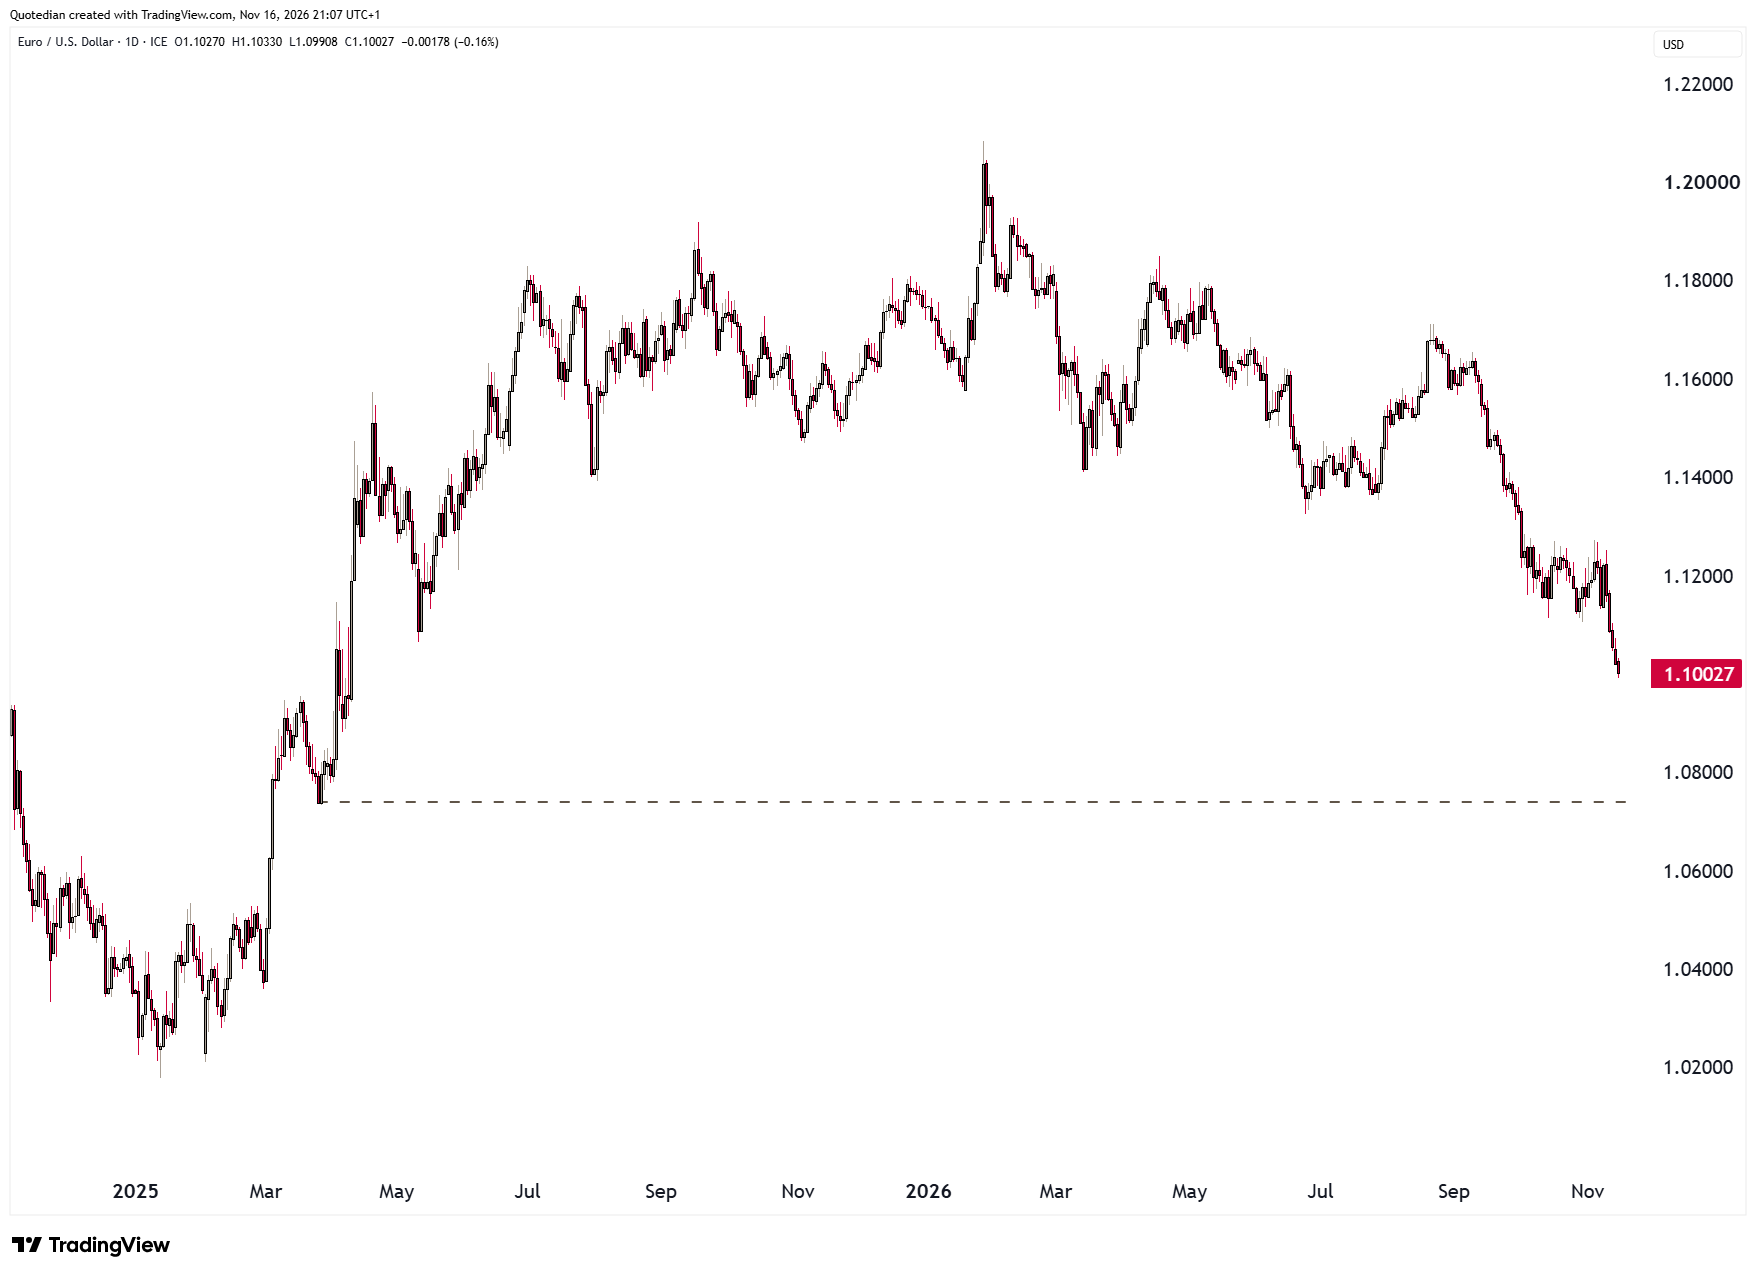
In currency markets, the US Dollar was stronger against literally all other major currencies over the past week, bar the South Korean Won:
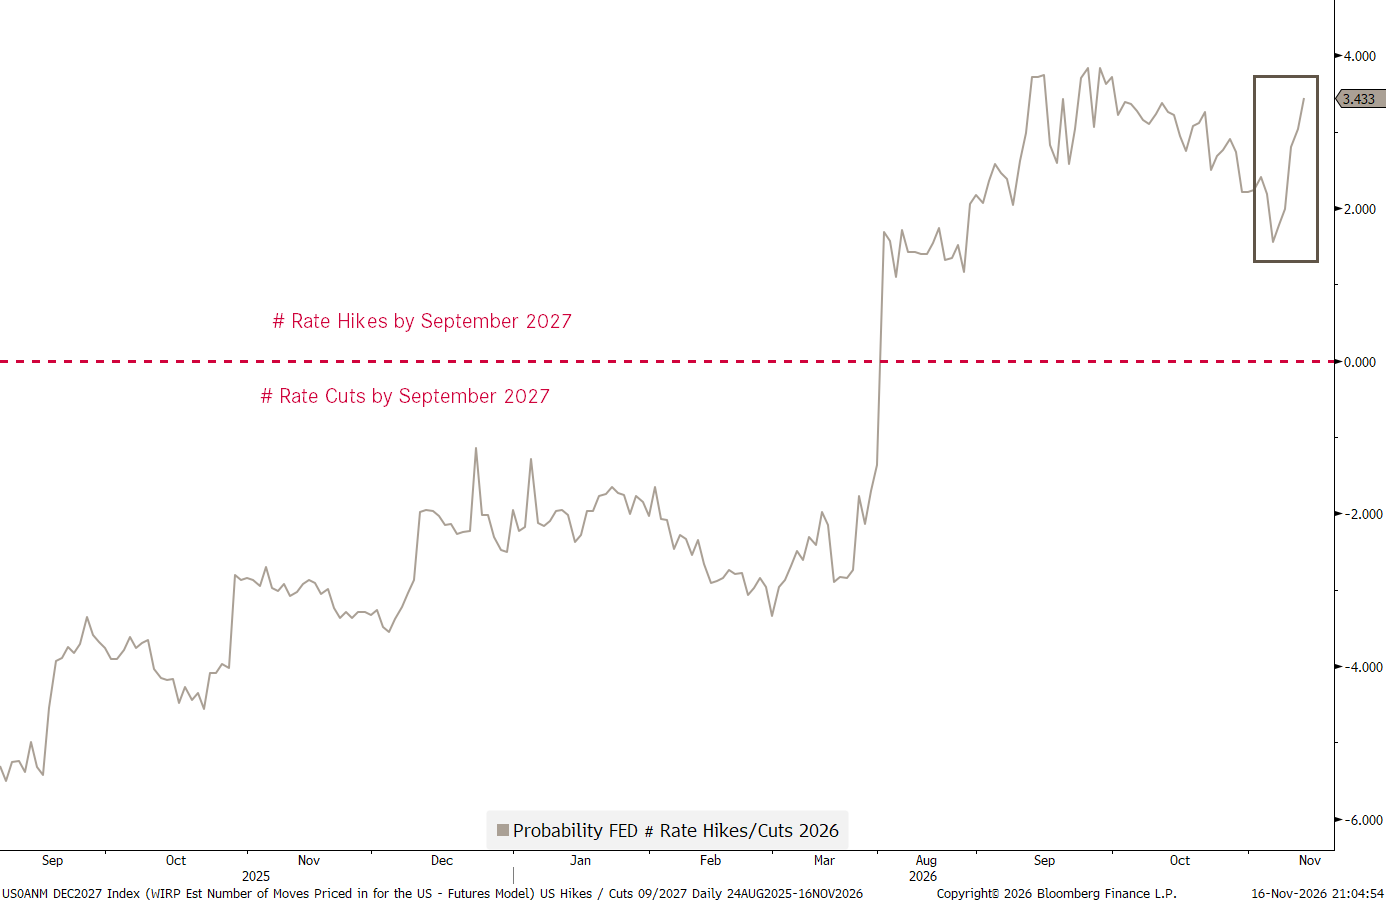
This can probably also be explained on the back of the higher bond yields and as rate hikes until end of next year as implied via futures markets have moved up again:
It is not looking good for us Dollar bears (DXY):
No meaningful support in sight on the EUR/USD until 1.07ish:
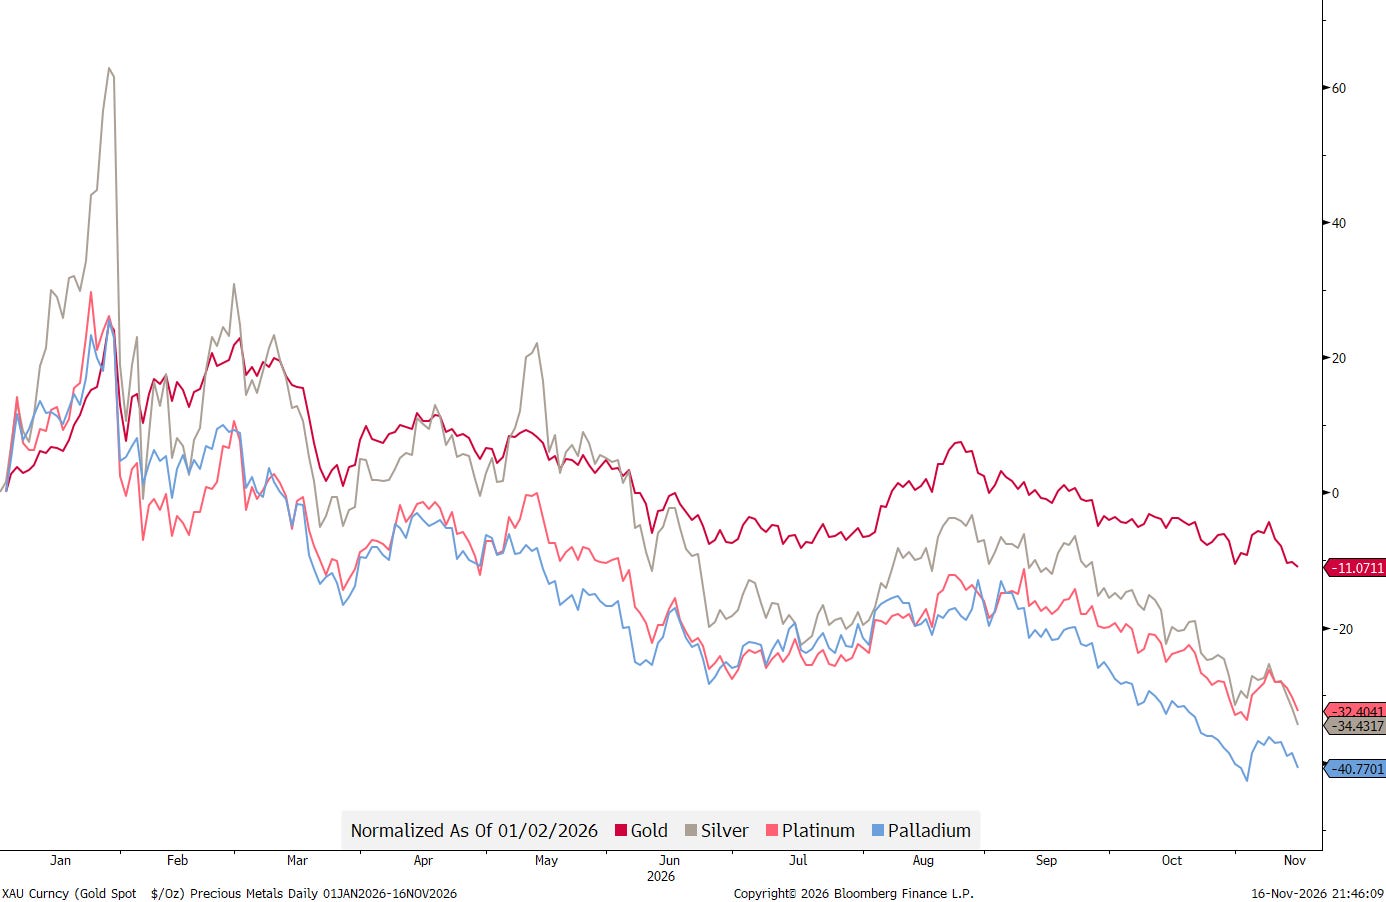
Let’s use the Dollar’s strength then as a segue into the commodity section and use it to explain the weakness in precious metals:
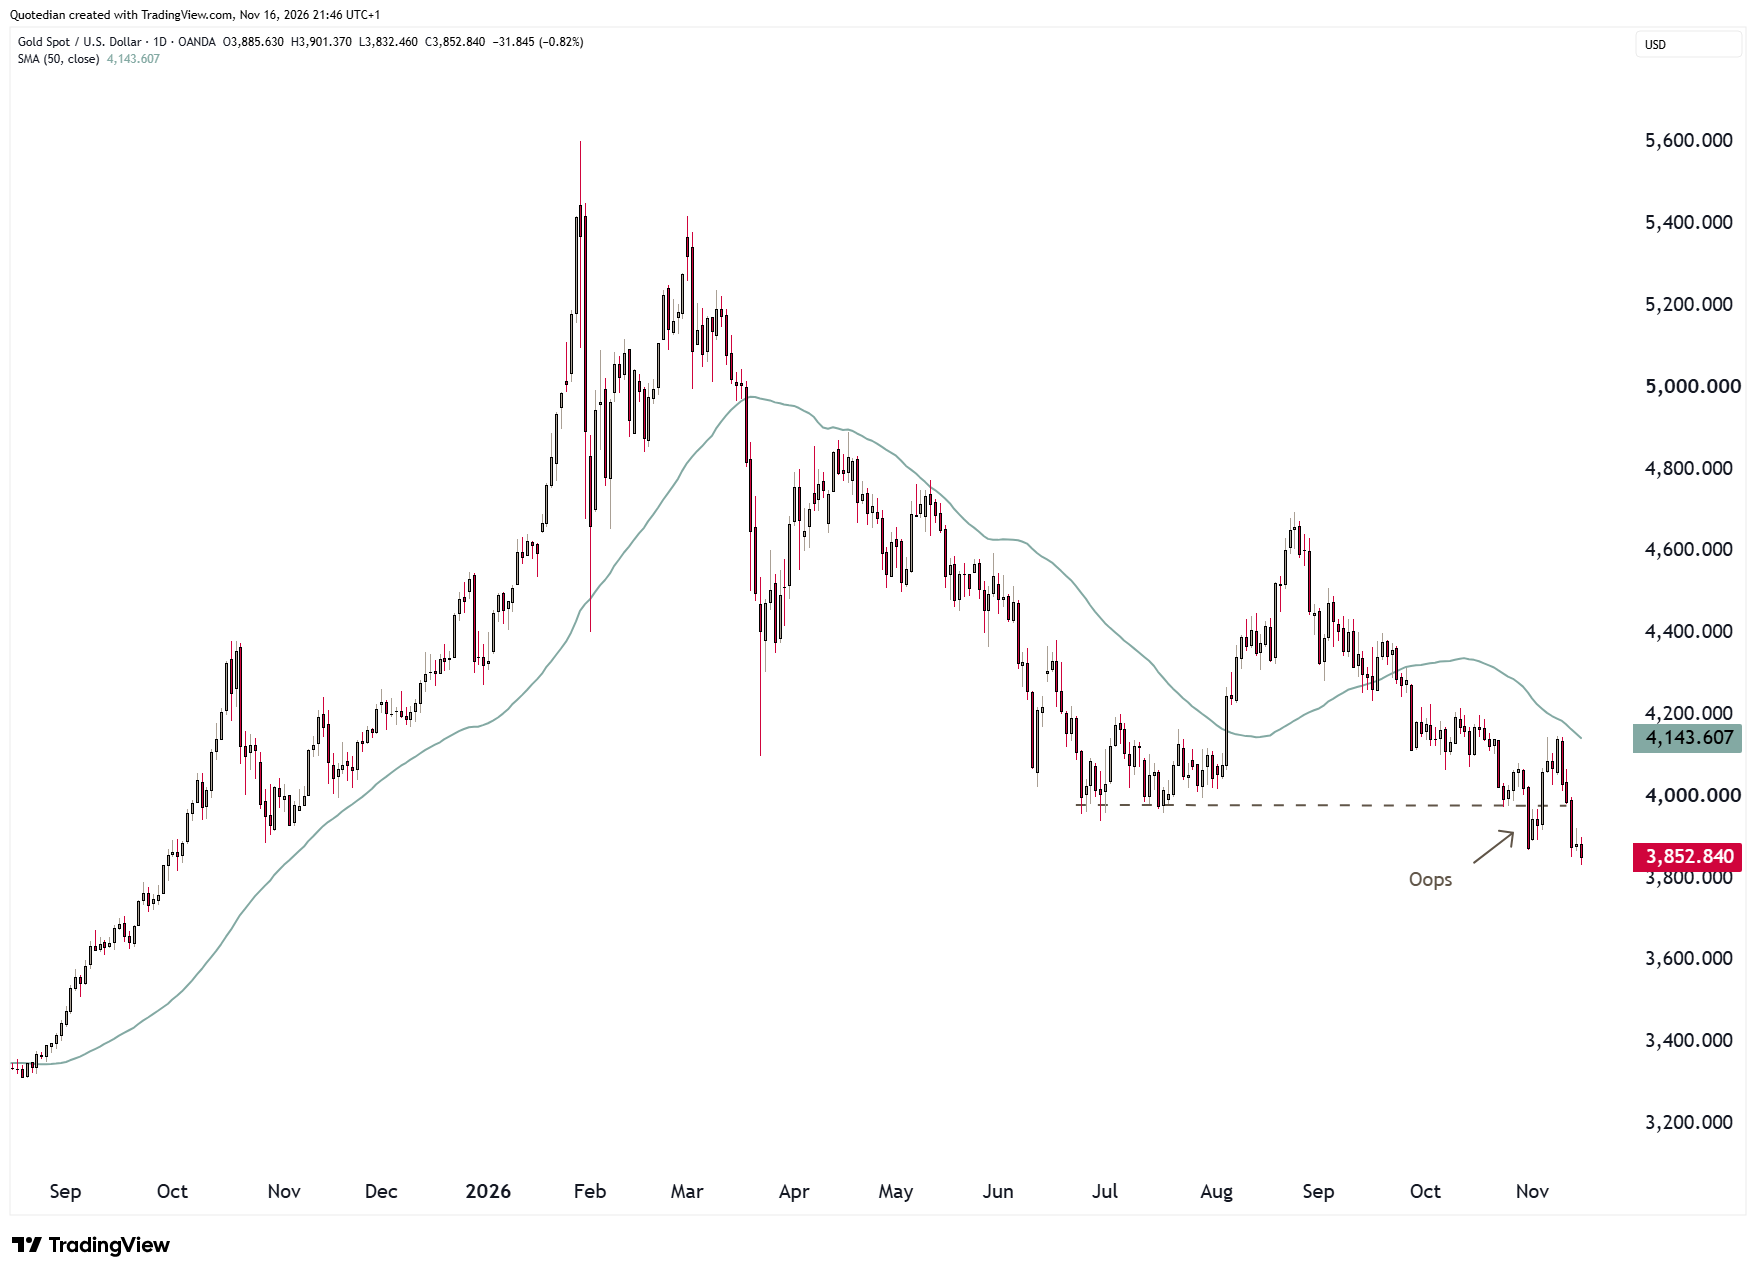
Gold is not looking healthy, having lost the bid at 4,000 again and trading now at its lowest since October last year:
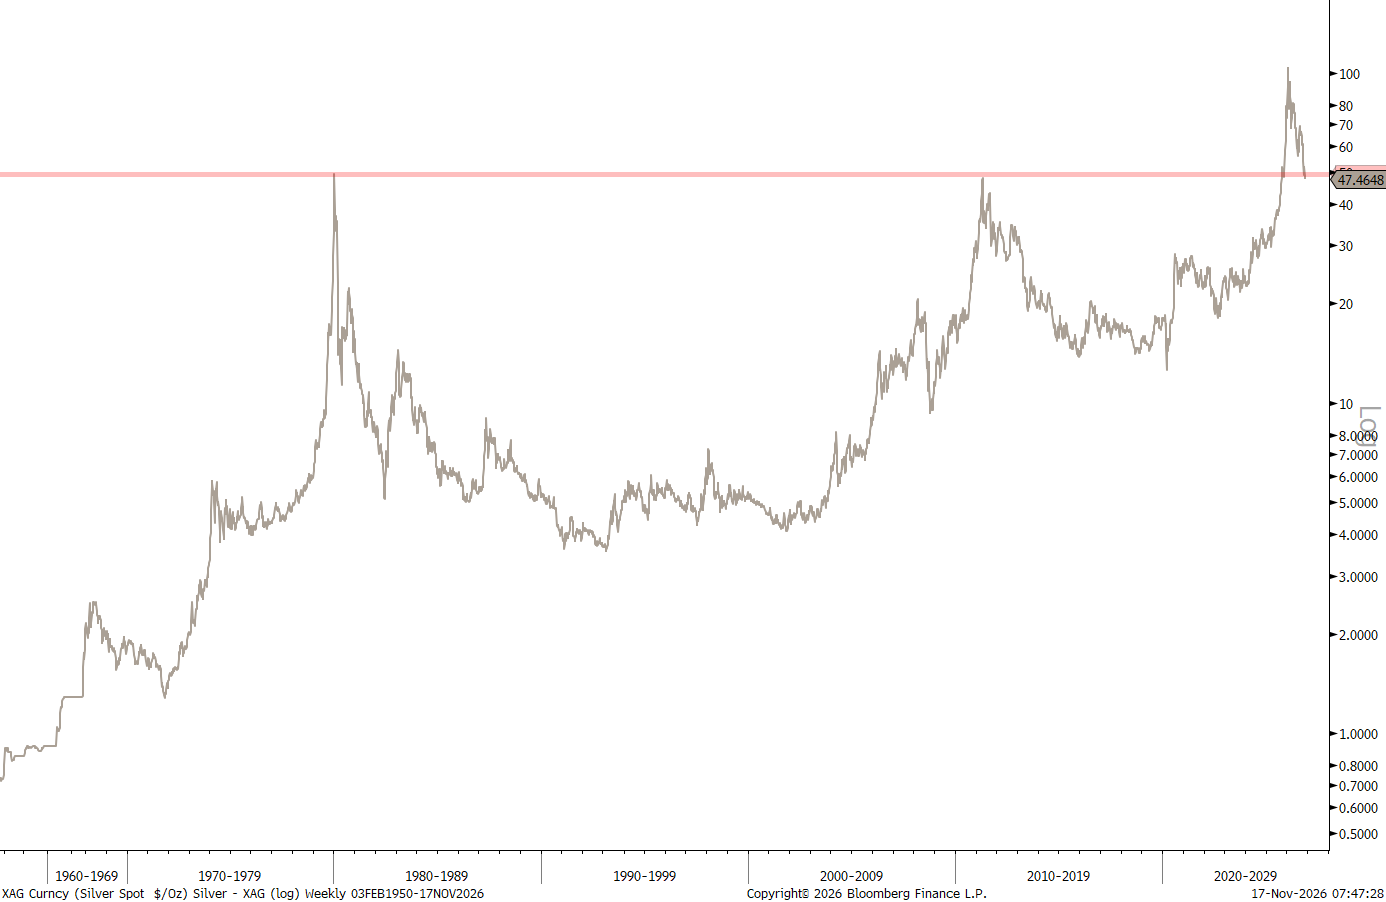
Silver (empty gulp) is right back at key support:
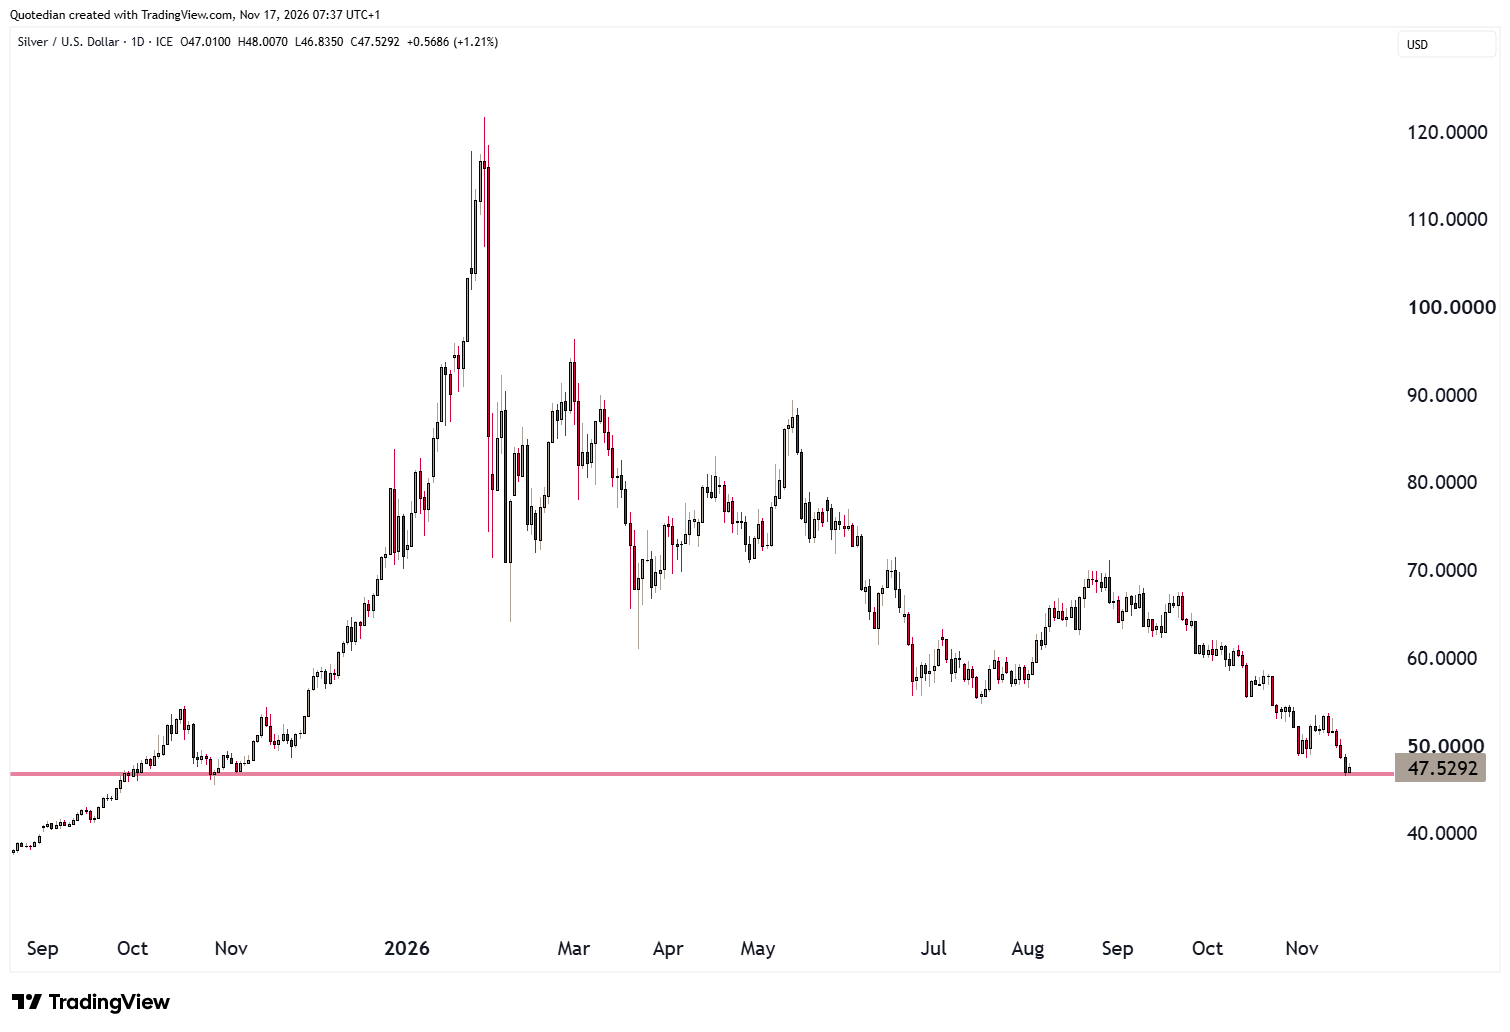
The importance of the current pivot-level at around $47 cannot be stressed enough:
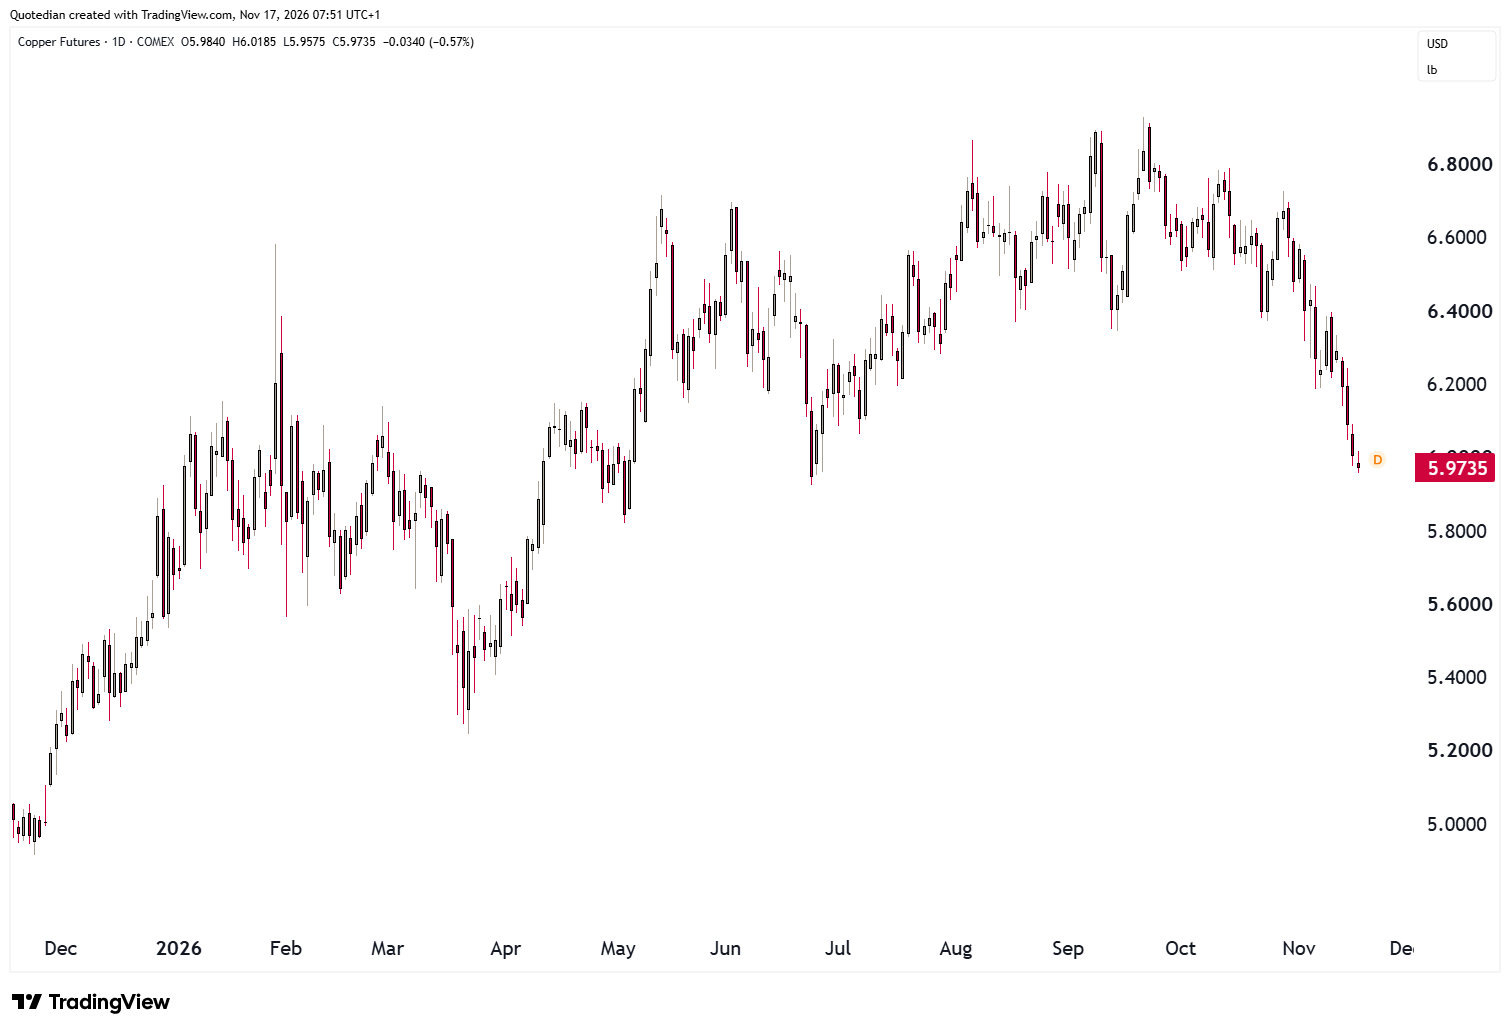
The bull in copper seems to have ended (hint: it’s also part of the AI trade):
If, and only if, copper (red) is coming down because the metal with a PhD in economics thinks the economy is slowing, and not because the AI trade is unwinding, then yields (grey) should also start heading south:
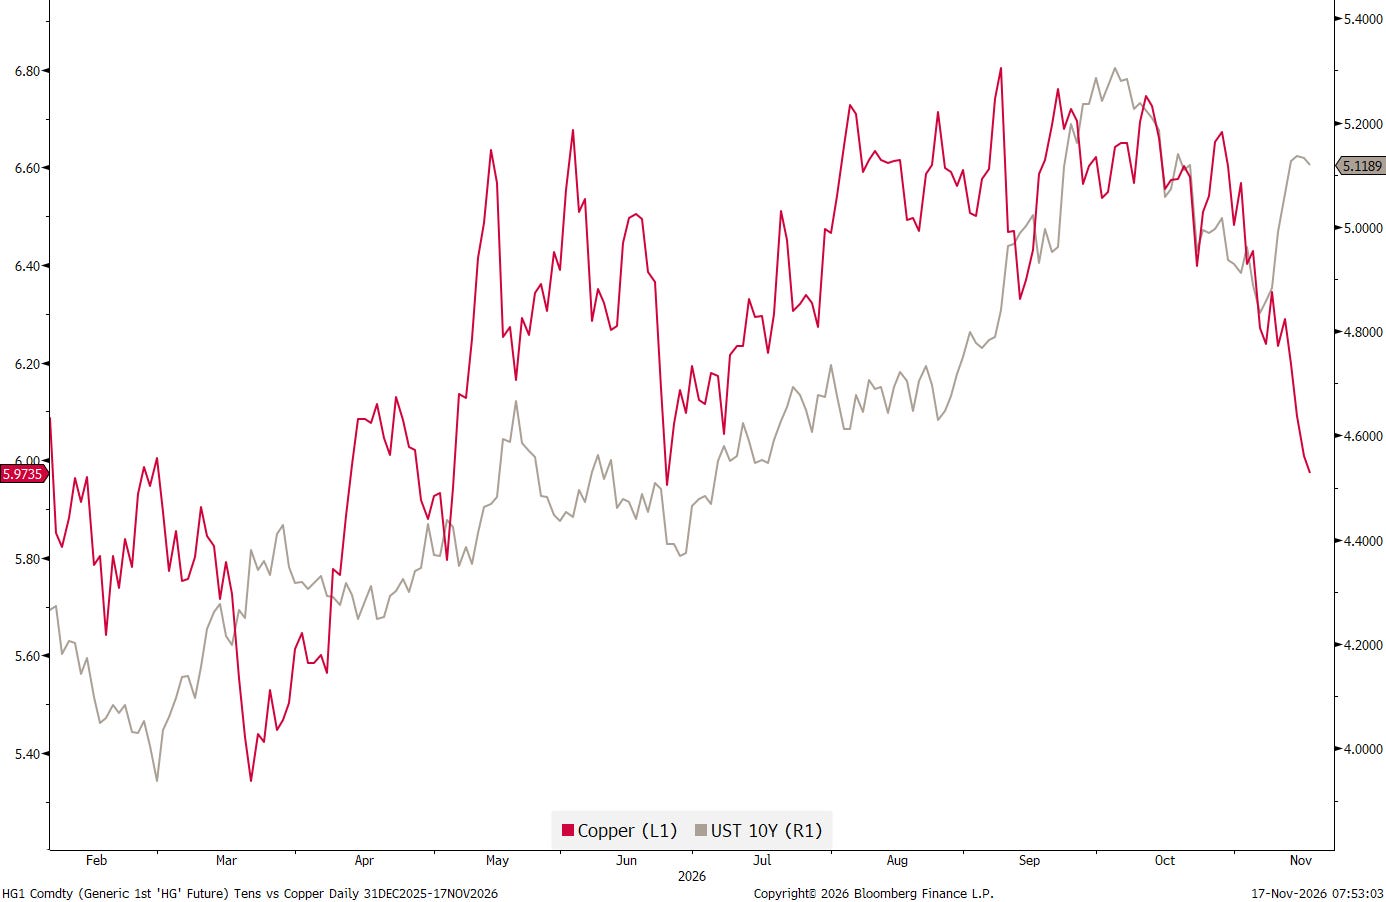
Big IF, I know.

Tonight, NVDA will report its Q3/27 earnings, for the first time in 33 years (biblical!) without its commander-in-chief Jensen Huang. I am sure the results will be fantastic and maybe even spark a small rally.
Thereafter, however, I fear a certain realization that it “just never will be the same” again may kick in and result in renewed selling pressure.
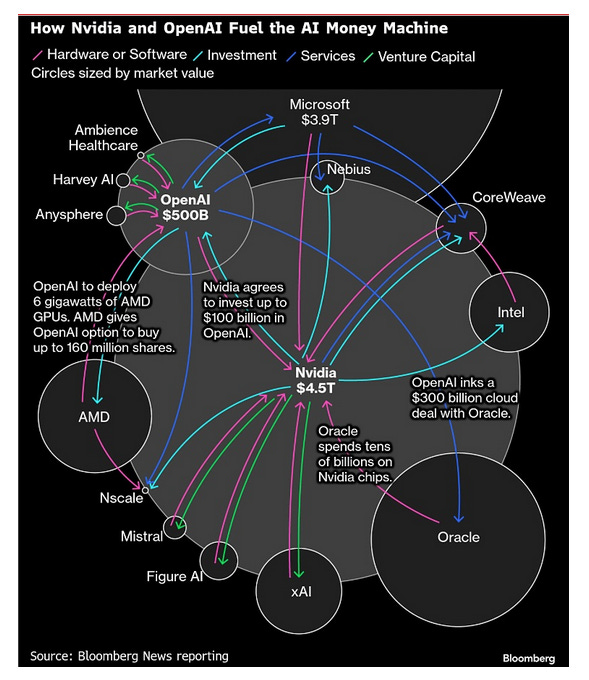
And not only at NVDA, but given the company’s heavy involvement in the circular economy (aka vendor financing), it could lead to a widespread wildfire:
Some of its strategic involvements of the past decades may also impact other less-AI-obvious segments:
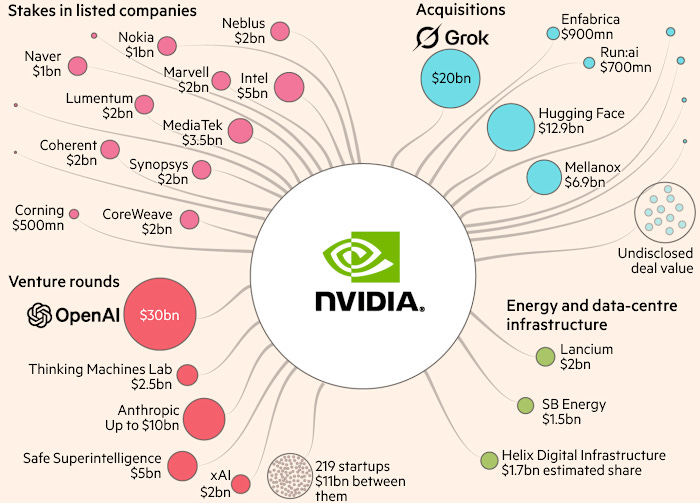
Nothing to ENVY about that possible outcome.
(ha.ha.)
Financial markets, stocks and bonds, are at a very delicate moment. For me, the question is, whether we will get one last hurray into year end, or, if the bear market programmed for 2027 is already here. Unfortunately, it increasingly looks like the latter. The next few sessions will be crucial.
Meanwhile, somewhere at Microsoft last Friday:
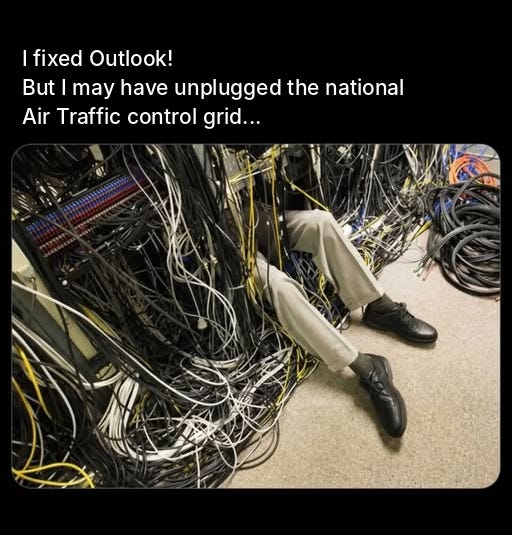
May Outlook remain with You!
André

The Important One:
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG
The Legal One:
Great stuff!