

“Markets, like beer, are best enjoyed in moderation. Unfortunately, nobody rings a bell when you've had too much.”
— The Quotedian

WHAT??!!
Another Quotedian?? We just had one a few hours ago!!
Yes, you are right, and this will be a mostly a factual recap of the performances of the different asset classes and subsets during the month of October for the sake of completeness.
If you are looking for fun, charts, and my silly and politically always incorrect deliberations, open up yesterday’s Quotedian: Trick or Treat? and delete this one.
No feelings hurt. Promised.
But if you decided to stick around and just before we start, talking about political incorrectness, let’s run a quick poll on the outcome of tomorrow’s US midterm election:
Please poll in numbers and obviously before the results are out.
Everybody participating in the poll will automatically receive The Quotedian one more year for free! 😜
To the stats …
October turned out to be good for bonds, but bad for stocks, leaving the 60/40 portfolio where it was.
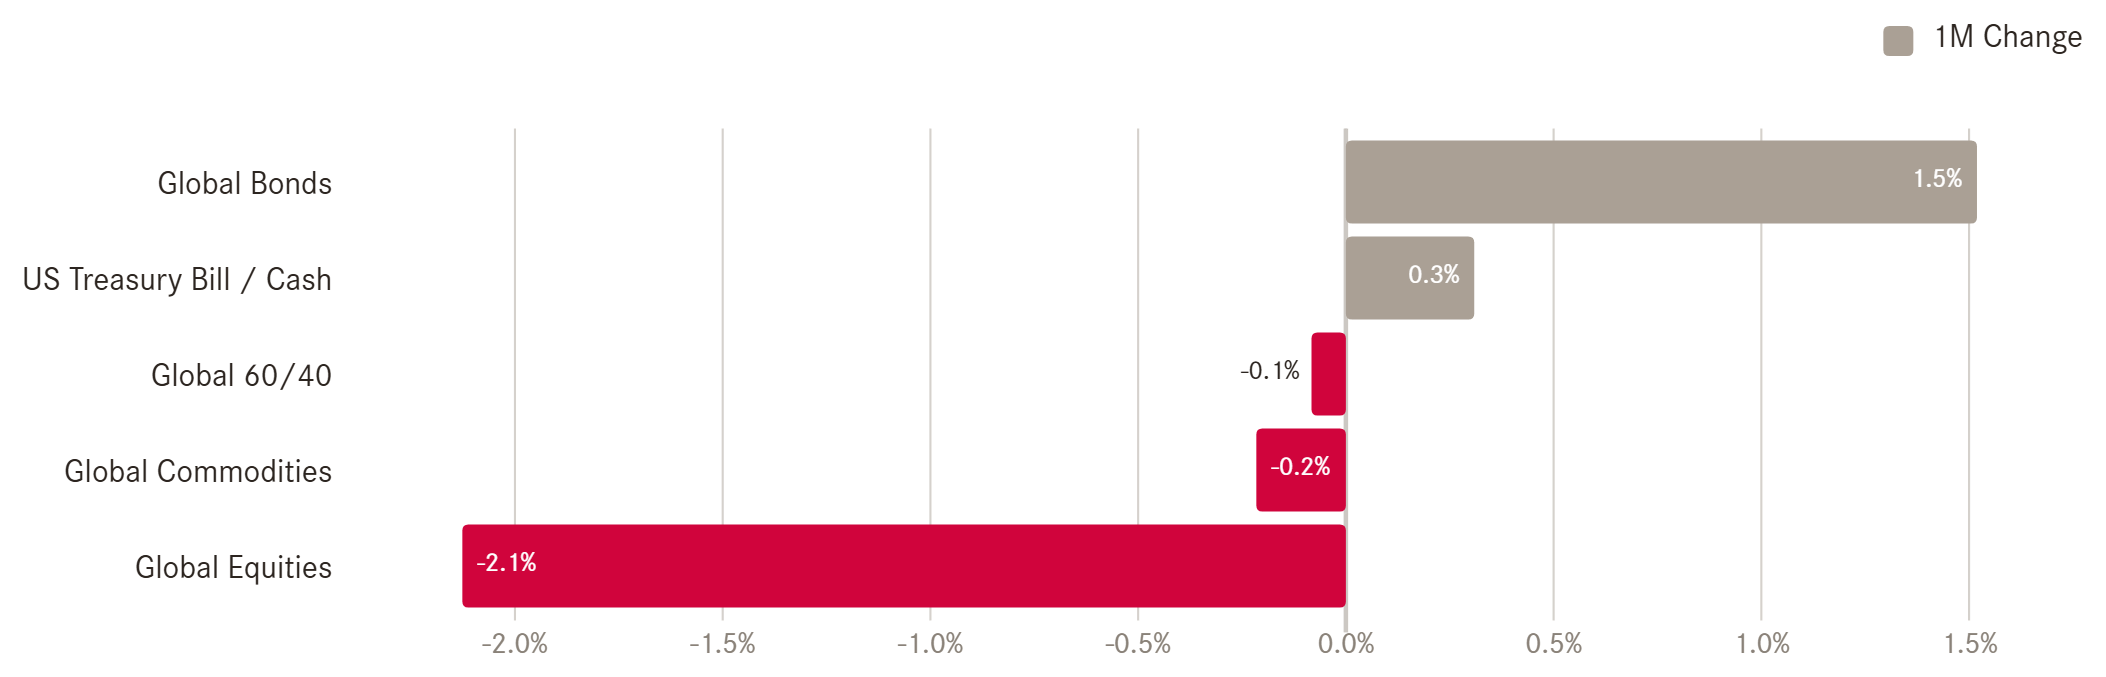
Isn’t diversification a wonderful thing?
Of course, as usual, the nuances in the performance of the subcategories in each asset class were success (or not) defining.
EQUITIES
By and large, it was a difficult month for most major equity benchmarks:
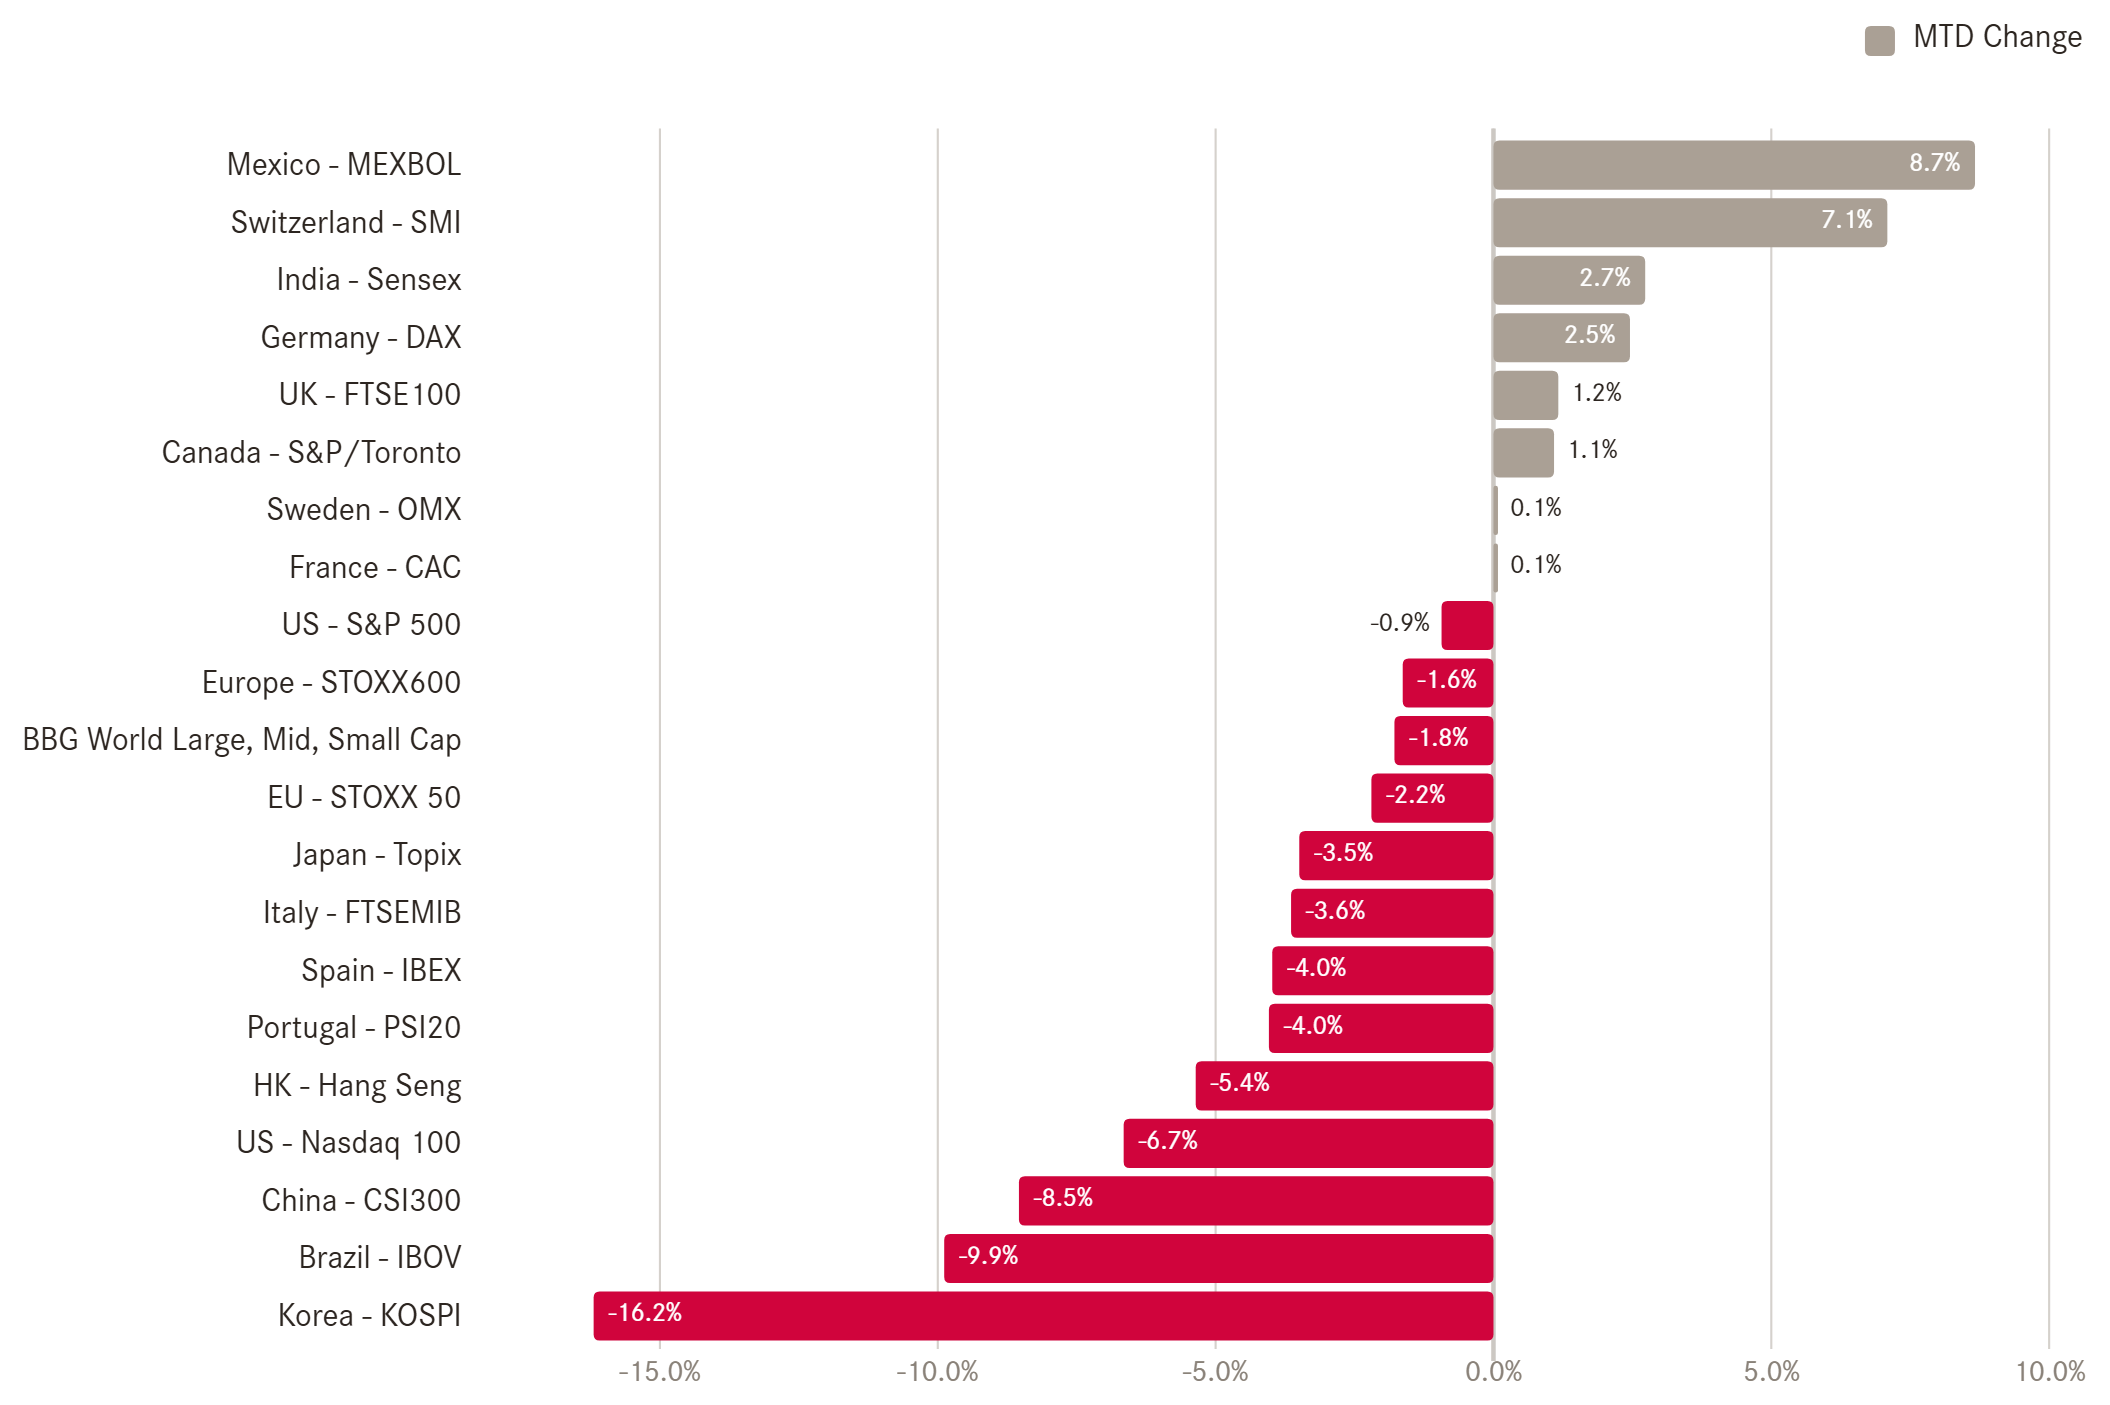
Korea mean reverted and Brazil got the election shock, whilst China has dropped into yet another bear market. Bright spots were Mexico, Switzerland and blimey, India!
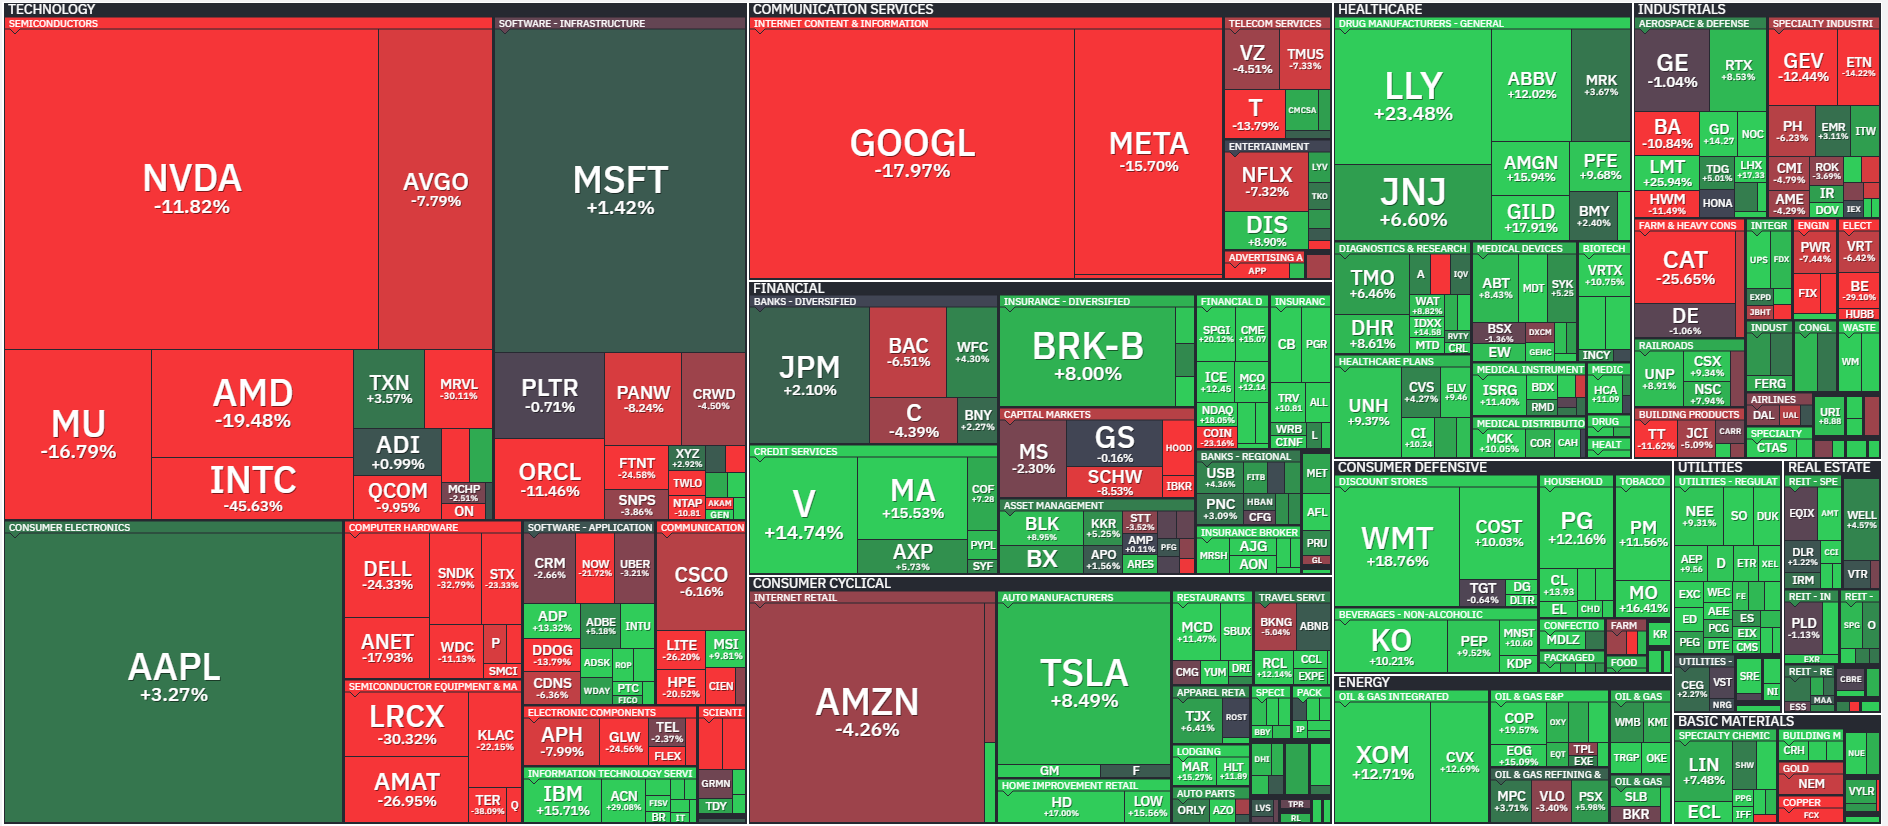
In cap-weighted terms the S&P 500 was down close to one percent, according to the previous statistic. However, and it is an important however, in equal-weight terms the index actually advanced nearly five percent!
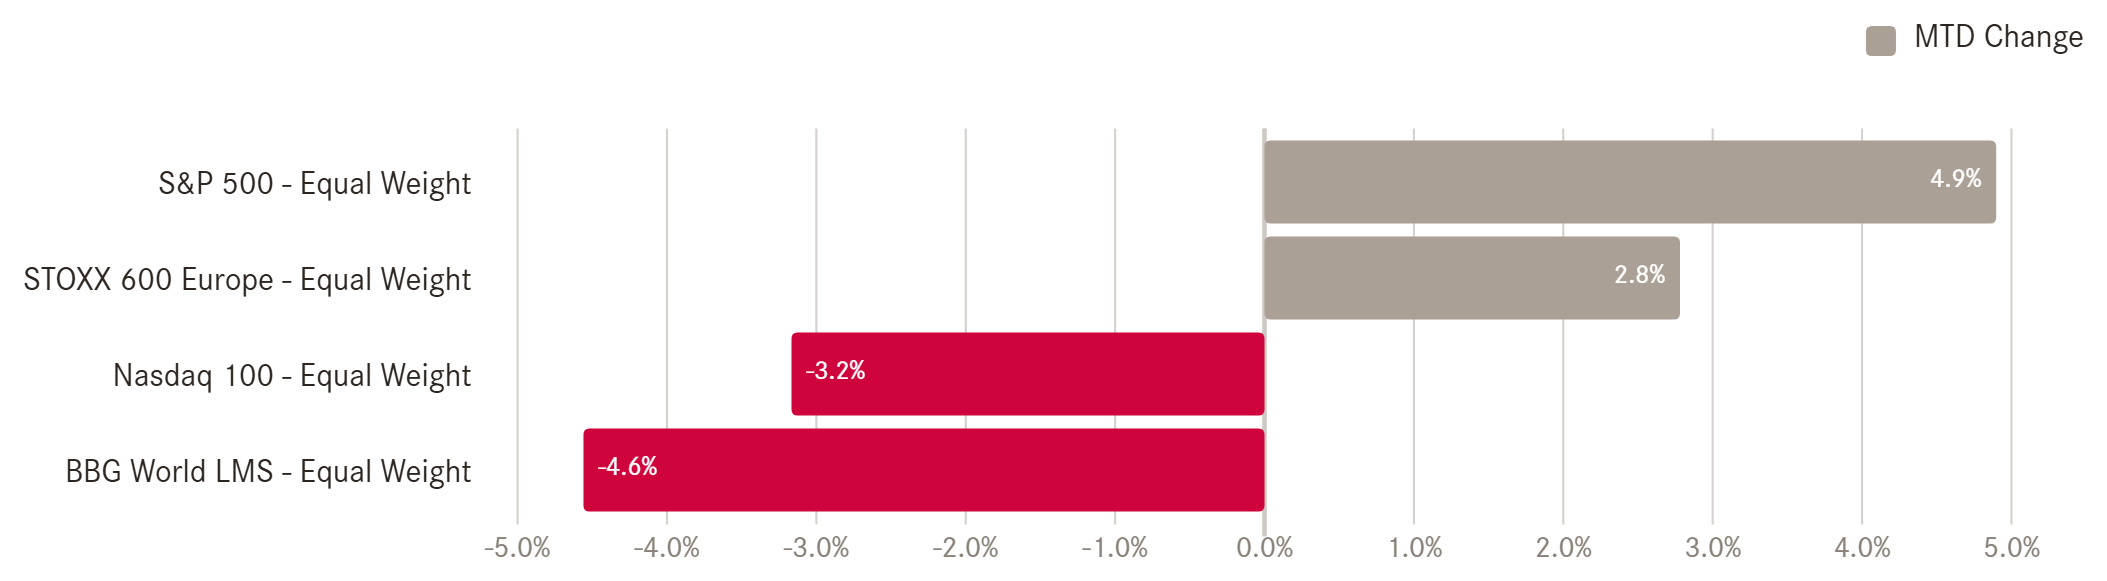
Hence, arguably, breadth actually improved during October as more stocks rose than dropped. Indeed, a lot of green on that one-month market carpet:
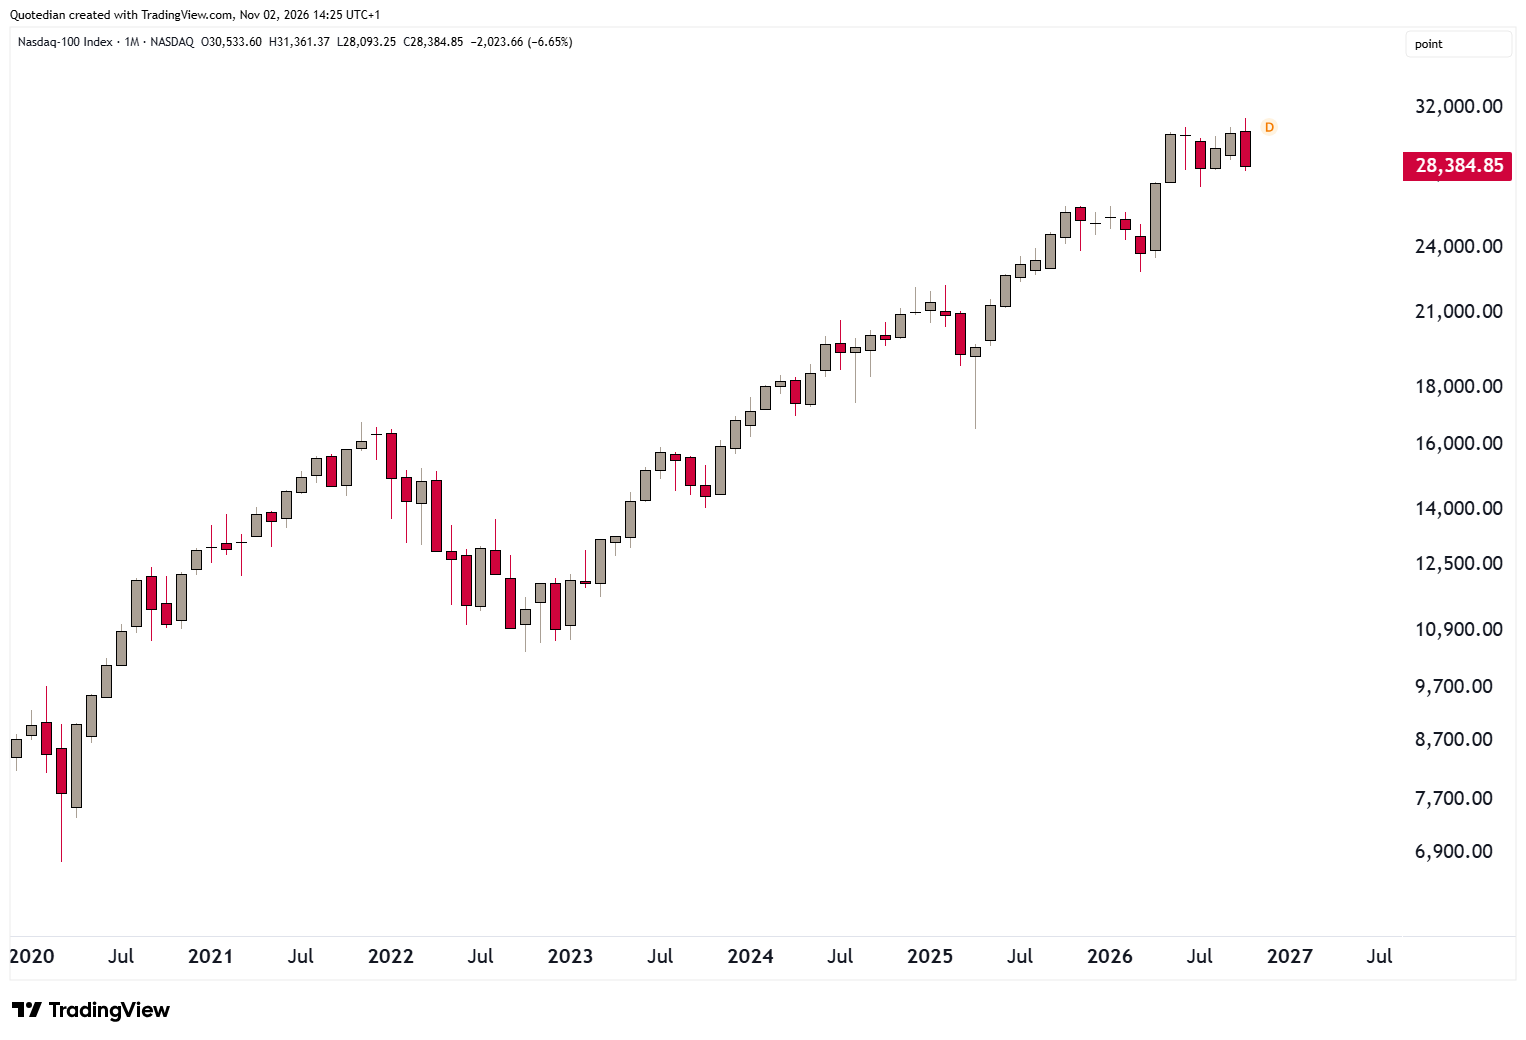
But even the Nasdaq, which was down in market-cap and equal-weight terms, does not show an overly negative monthly chart:
Sector selection also turned out to be crucial during October:
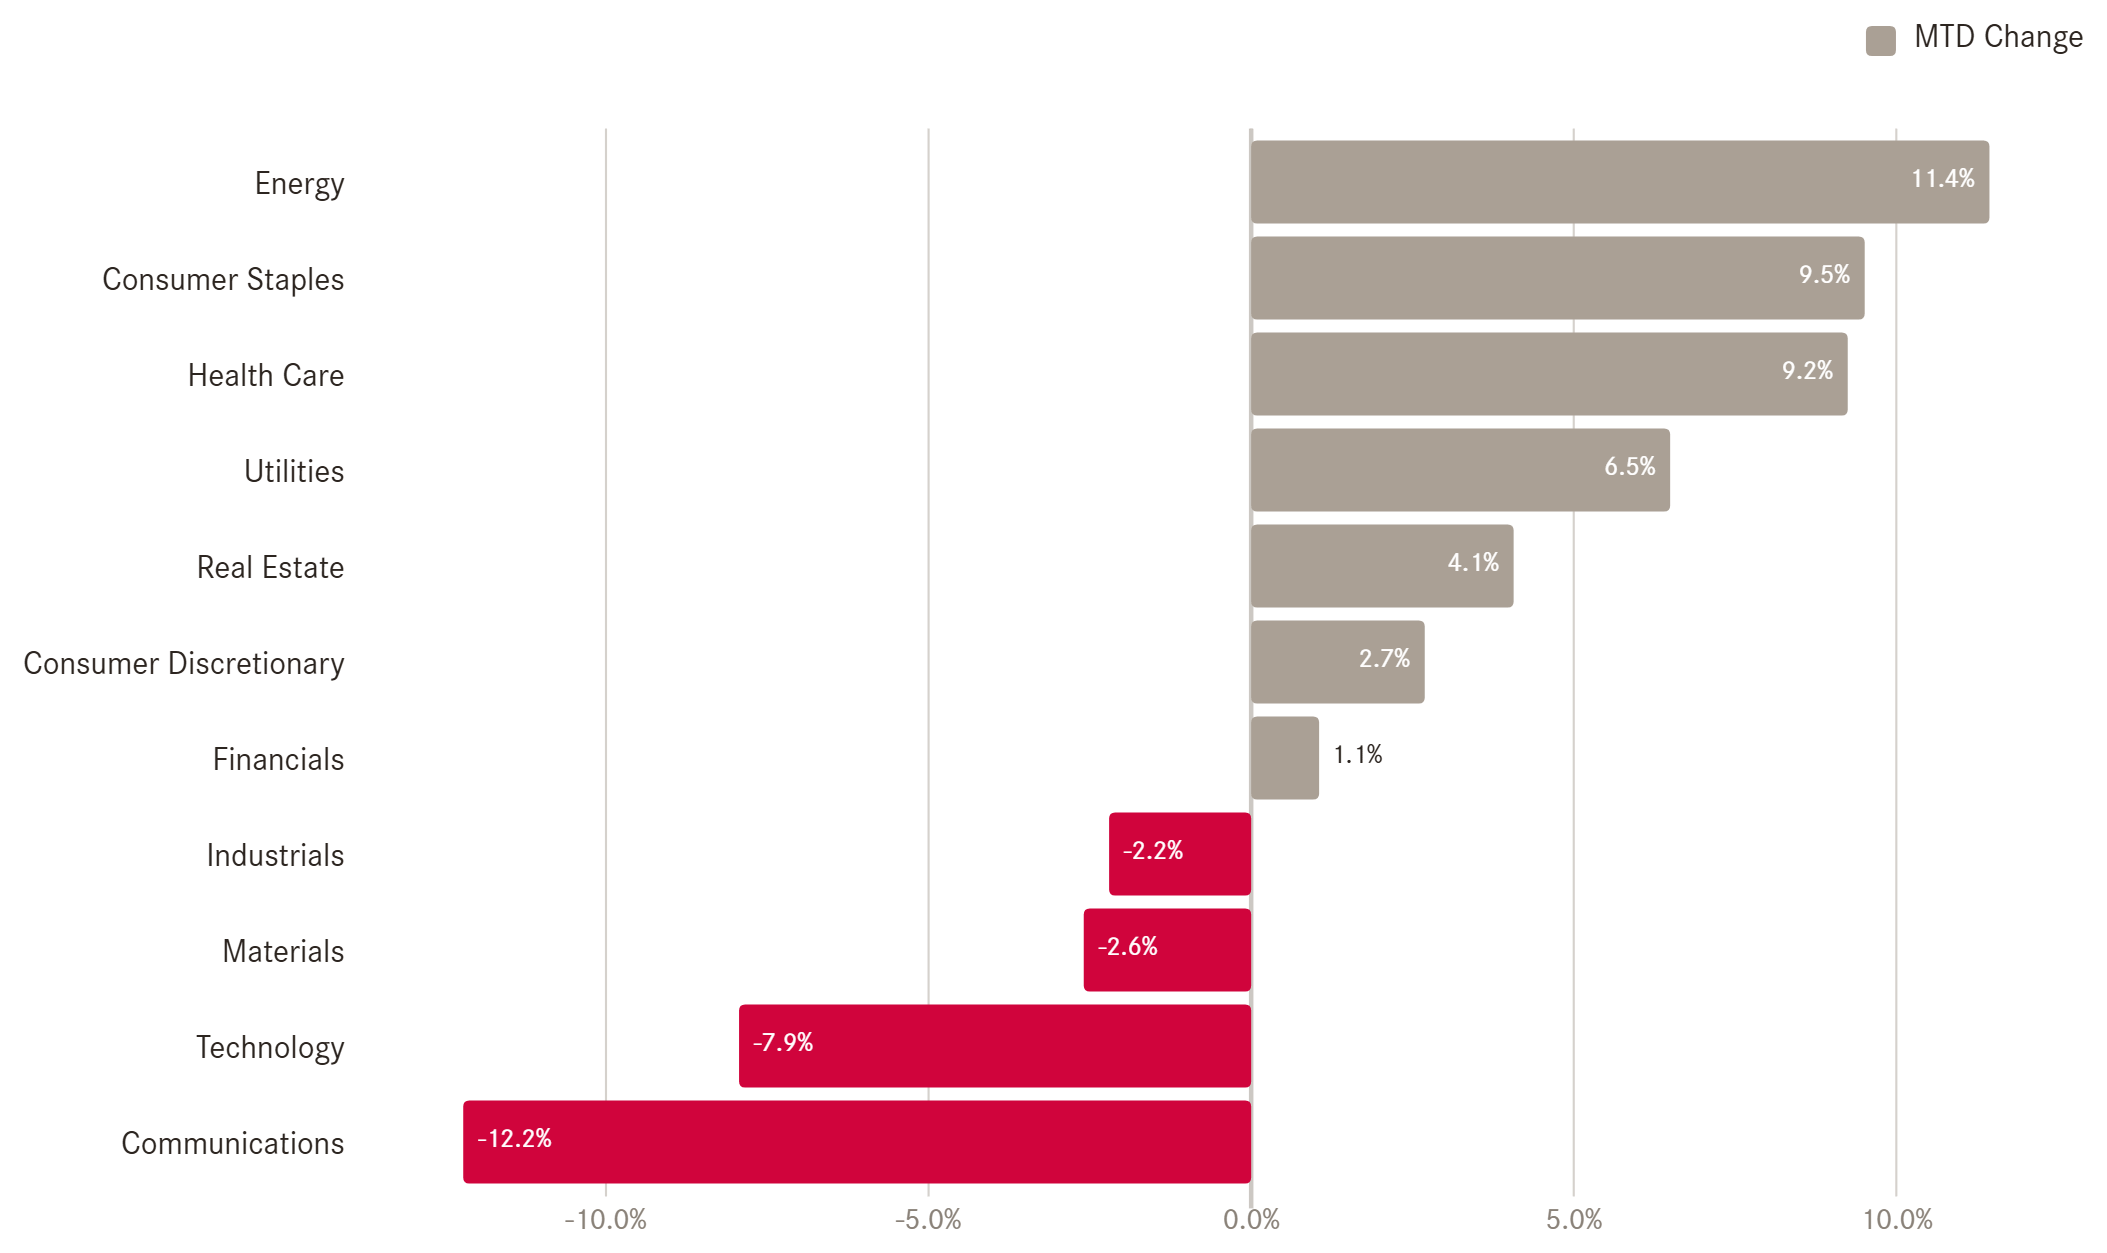
Take note of the sector rotation to defensive…
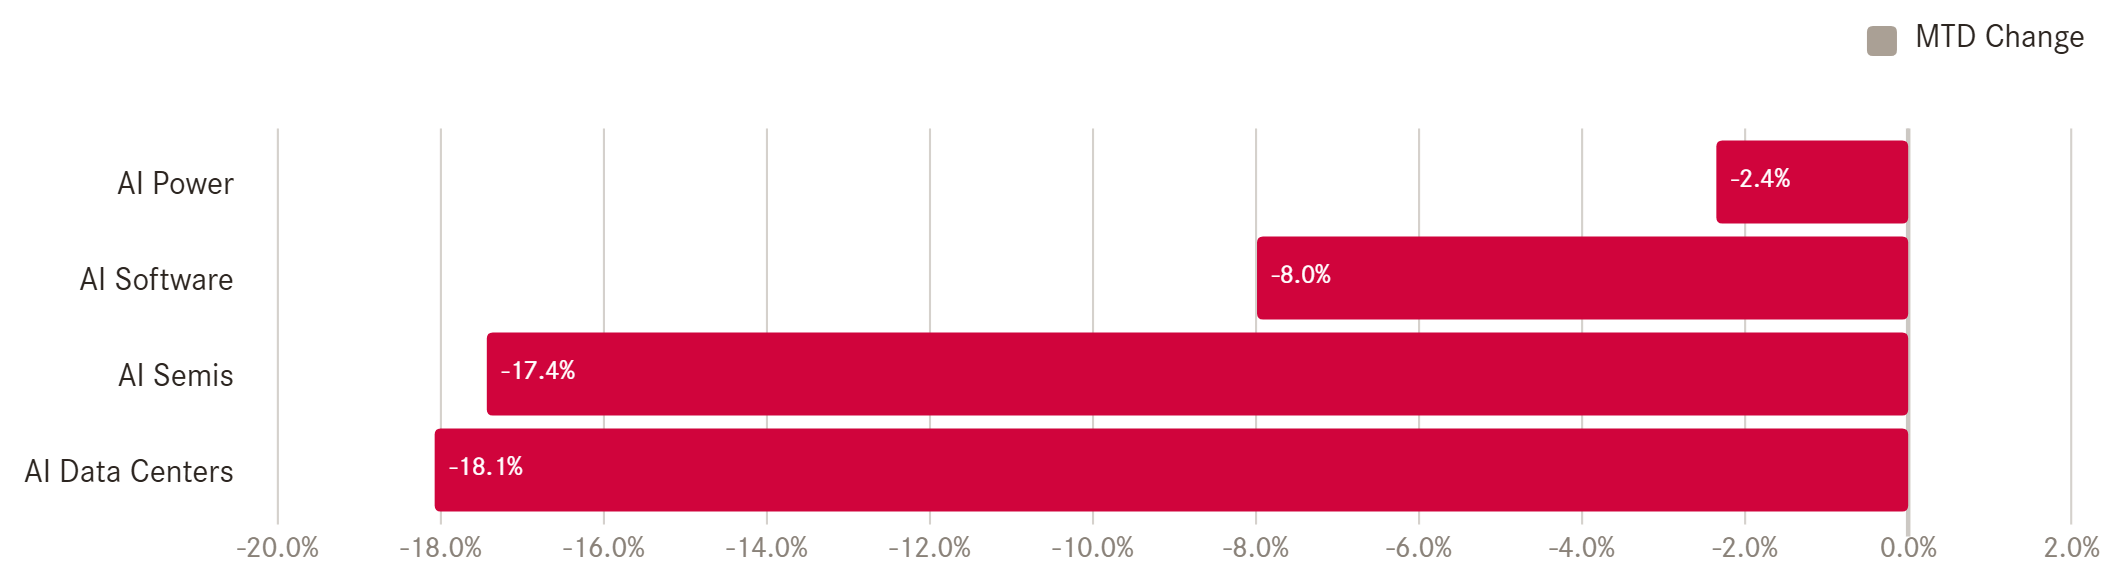
Many popular themes were under pressure in October:
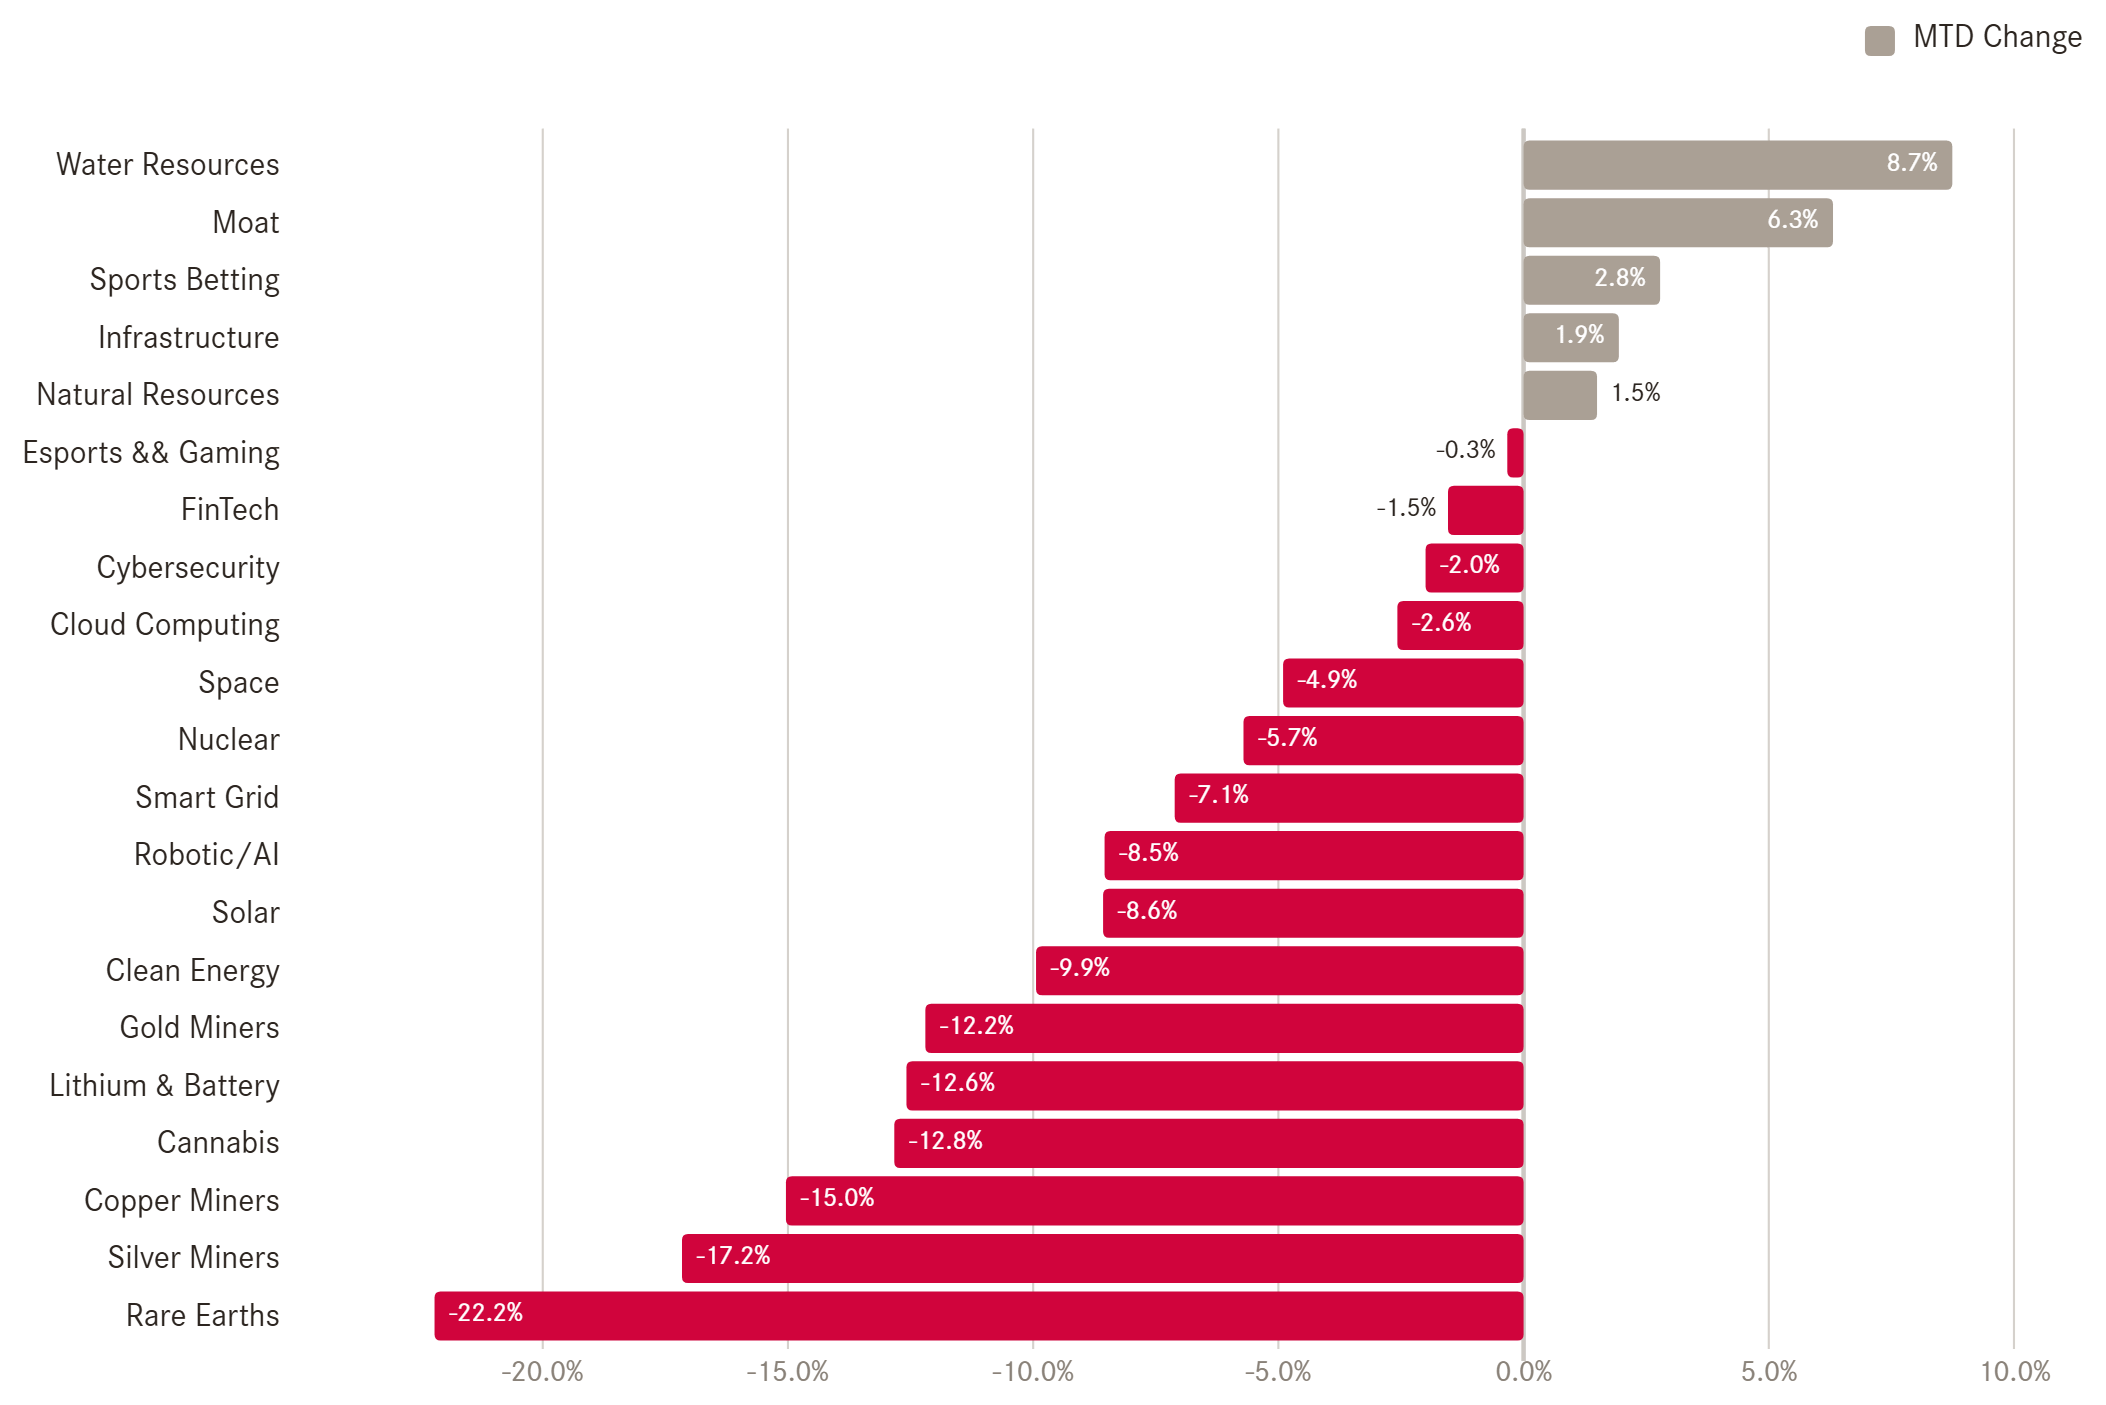
But the AI-trade got completely ‘hammered’:
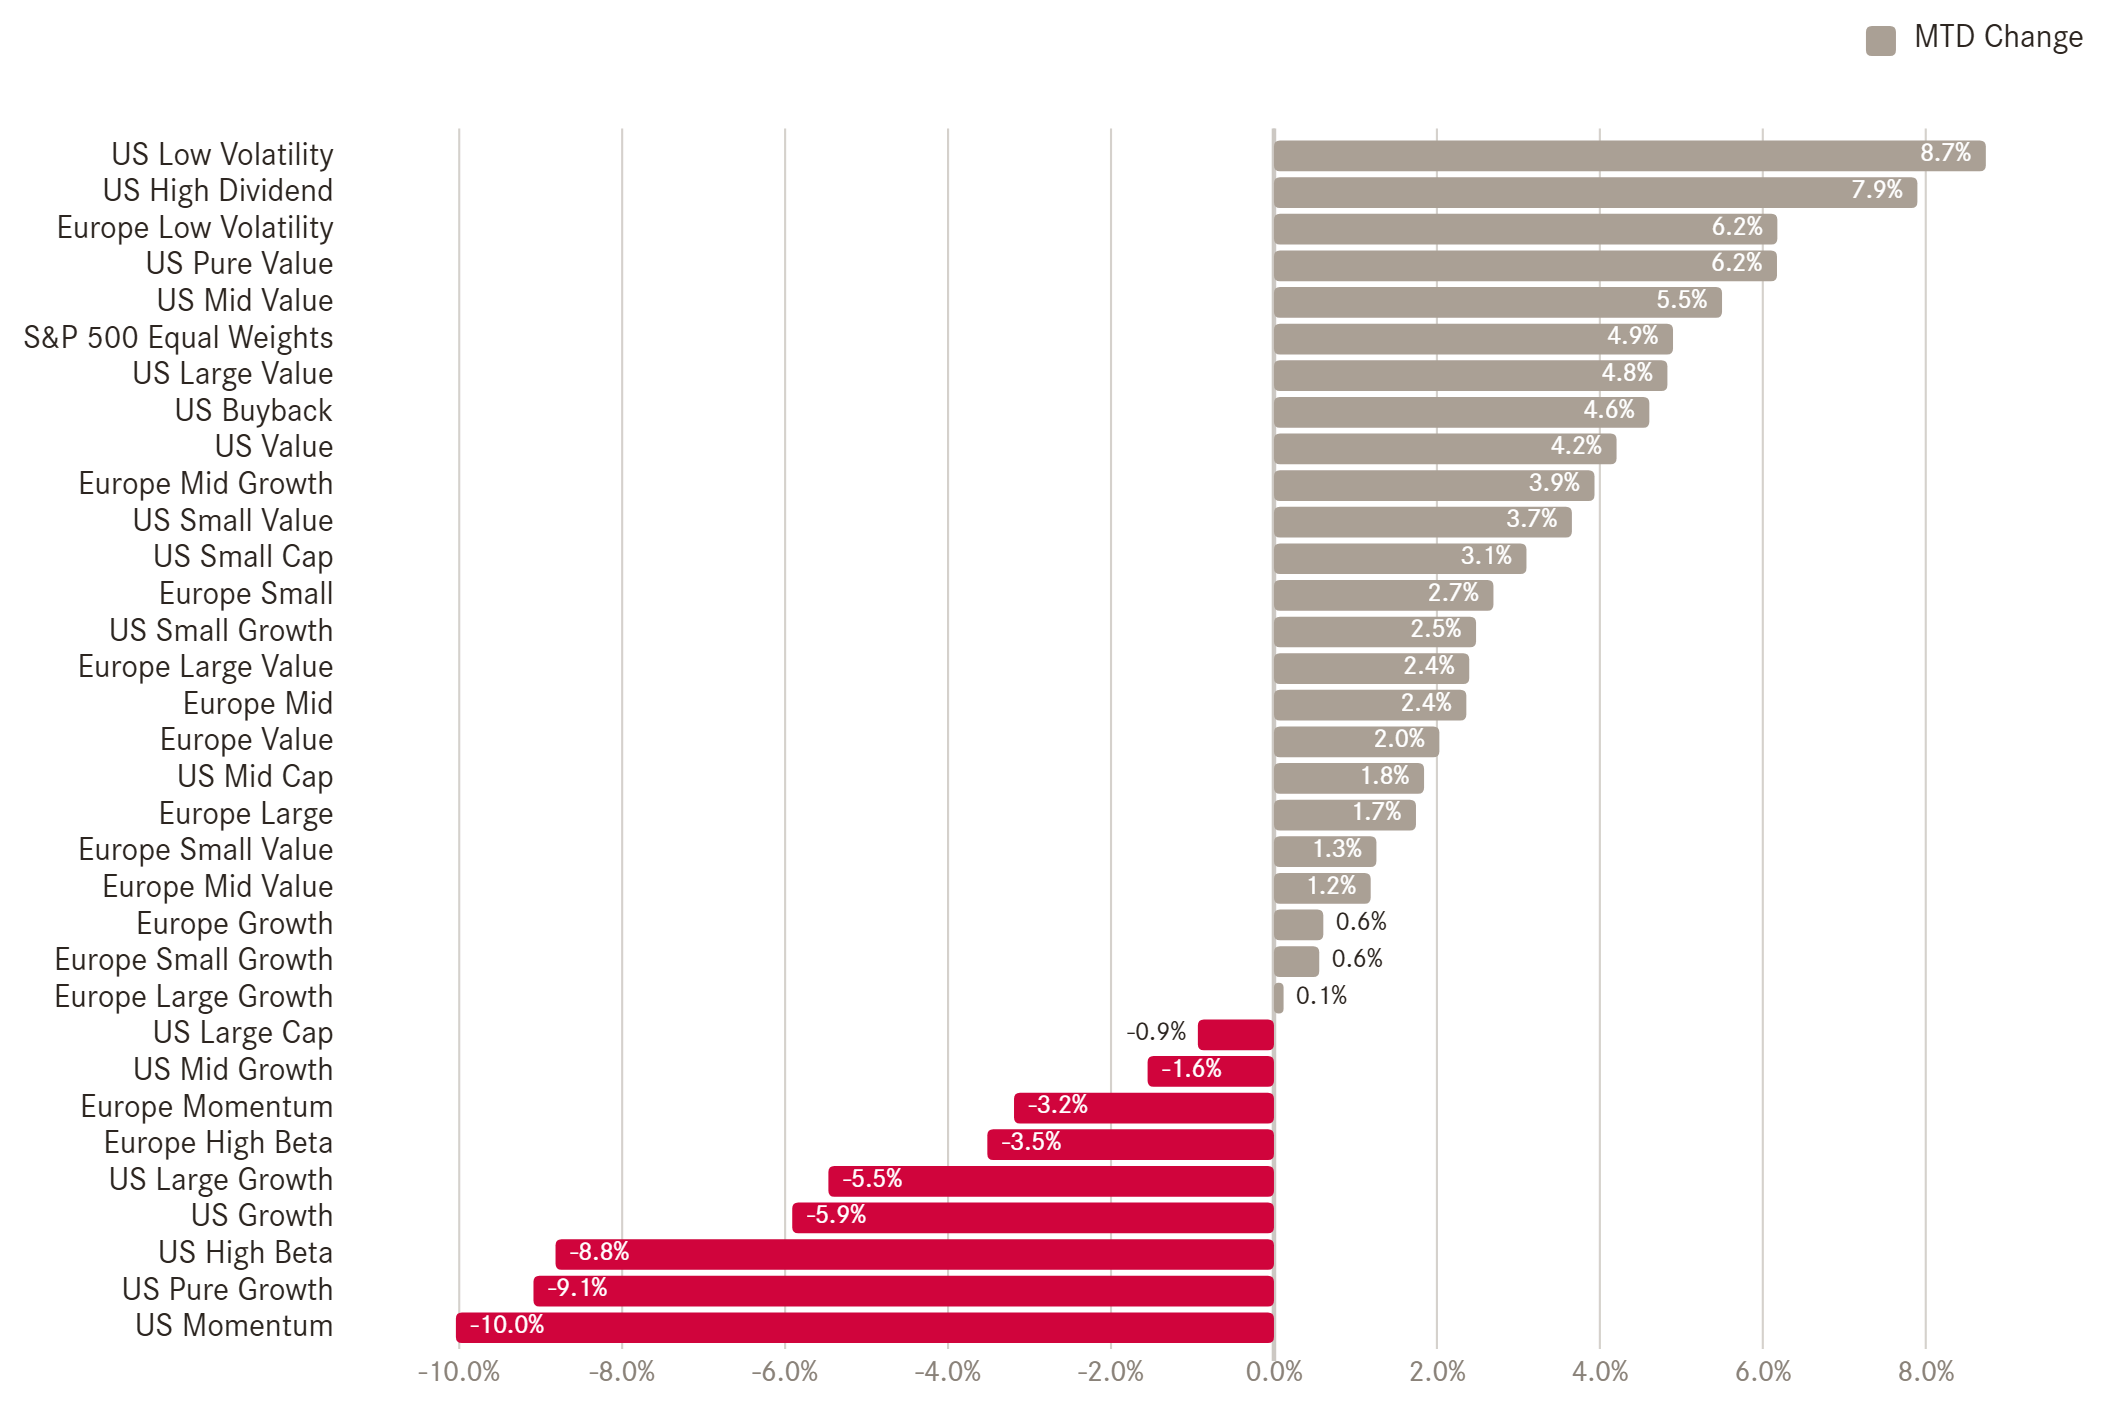
Factor performance also exhibits a tilt toward defensive in October:
FIXED INCOME
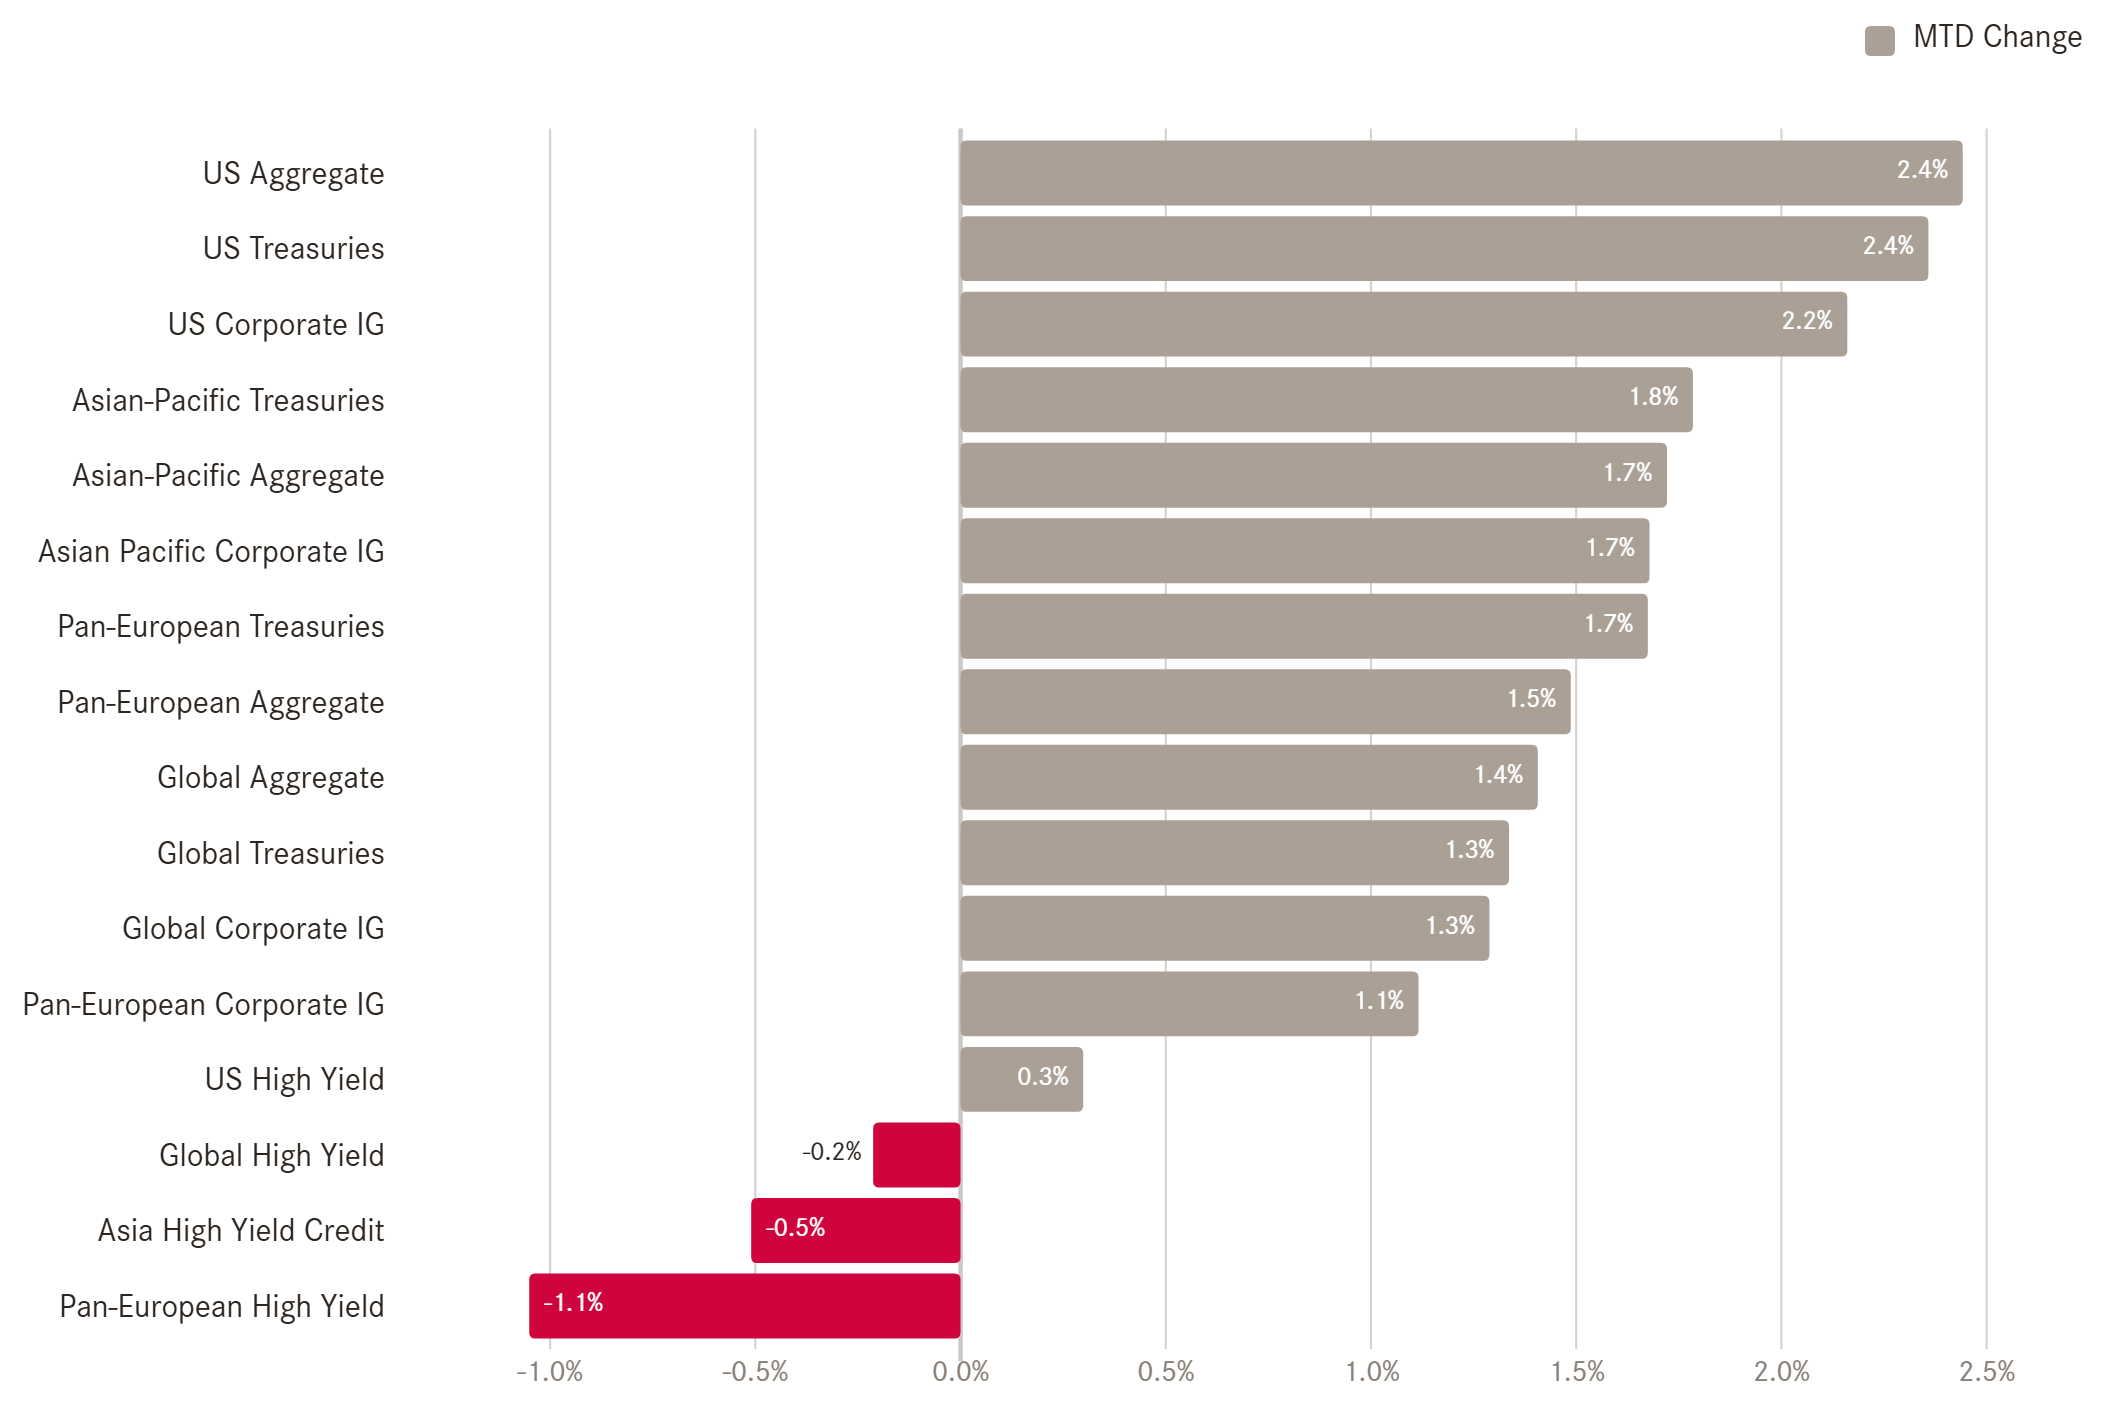
Fixed income markets were largely positive, especially the duration and higher quality segments:
US (10Y) treasury yields reversed some of their upside of the previous month:
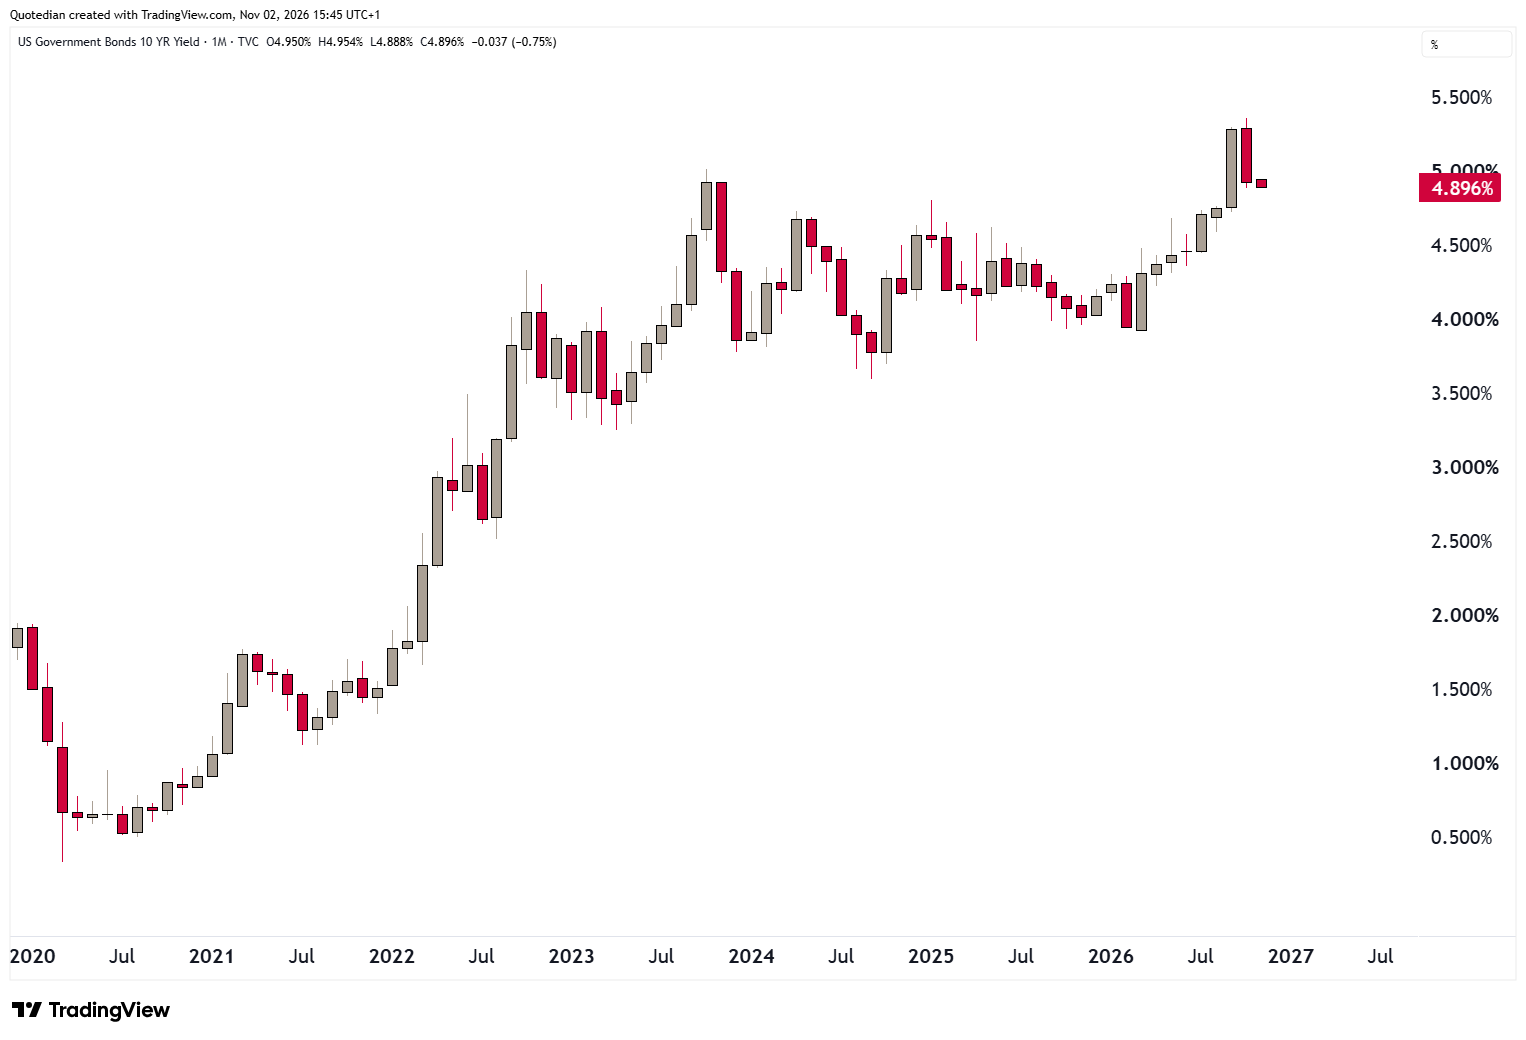
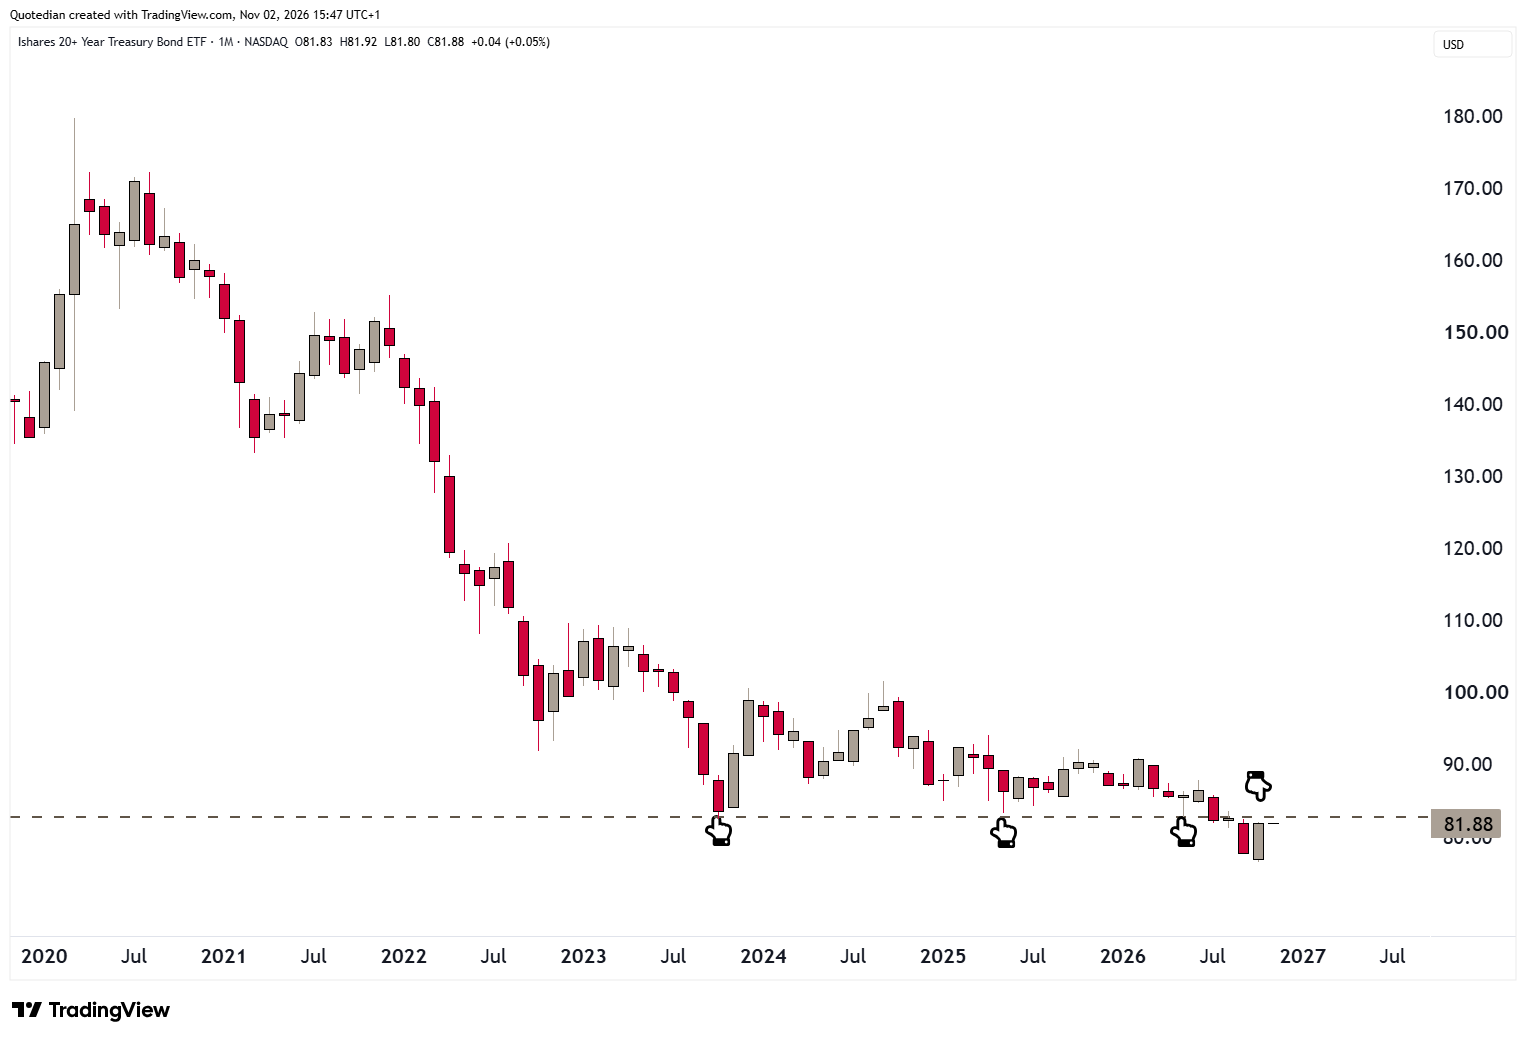
Hence, longer-duration plays such as the iShares 20+ year Treasury ETF (TLT) rose more than five percent (but still trades below the support-turned-resistance level):
CURRENCIES
The US Dollar shows a very mixed picture for the month of October:
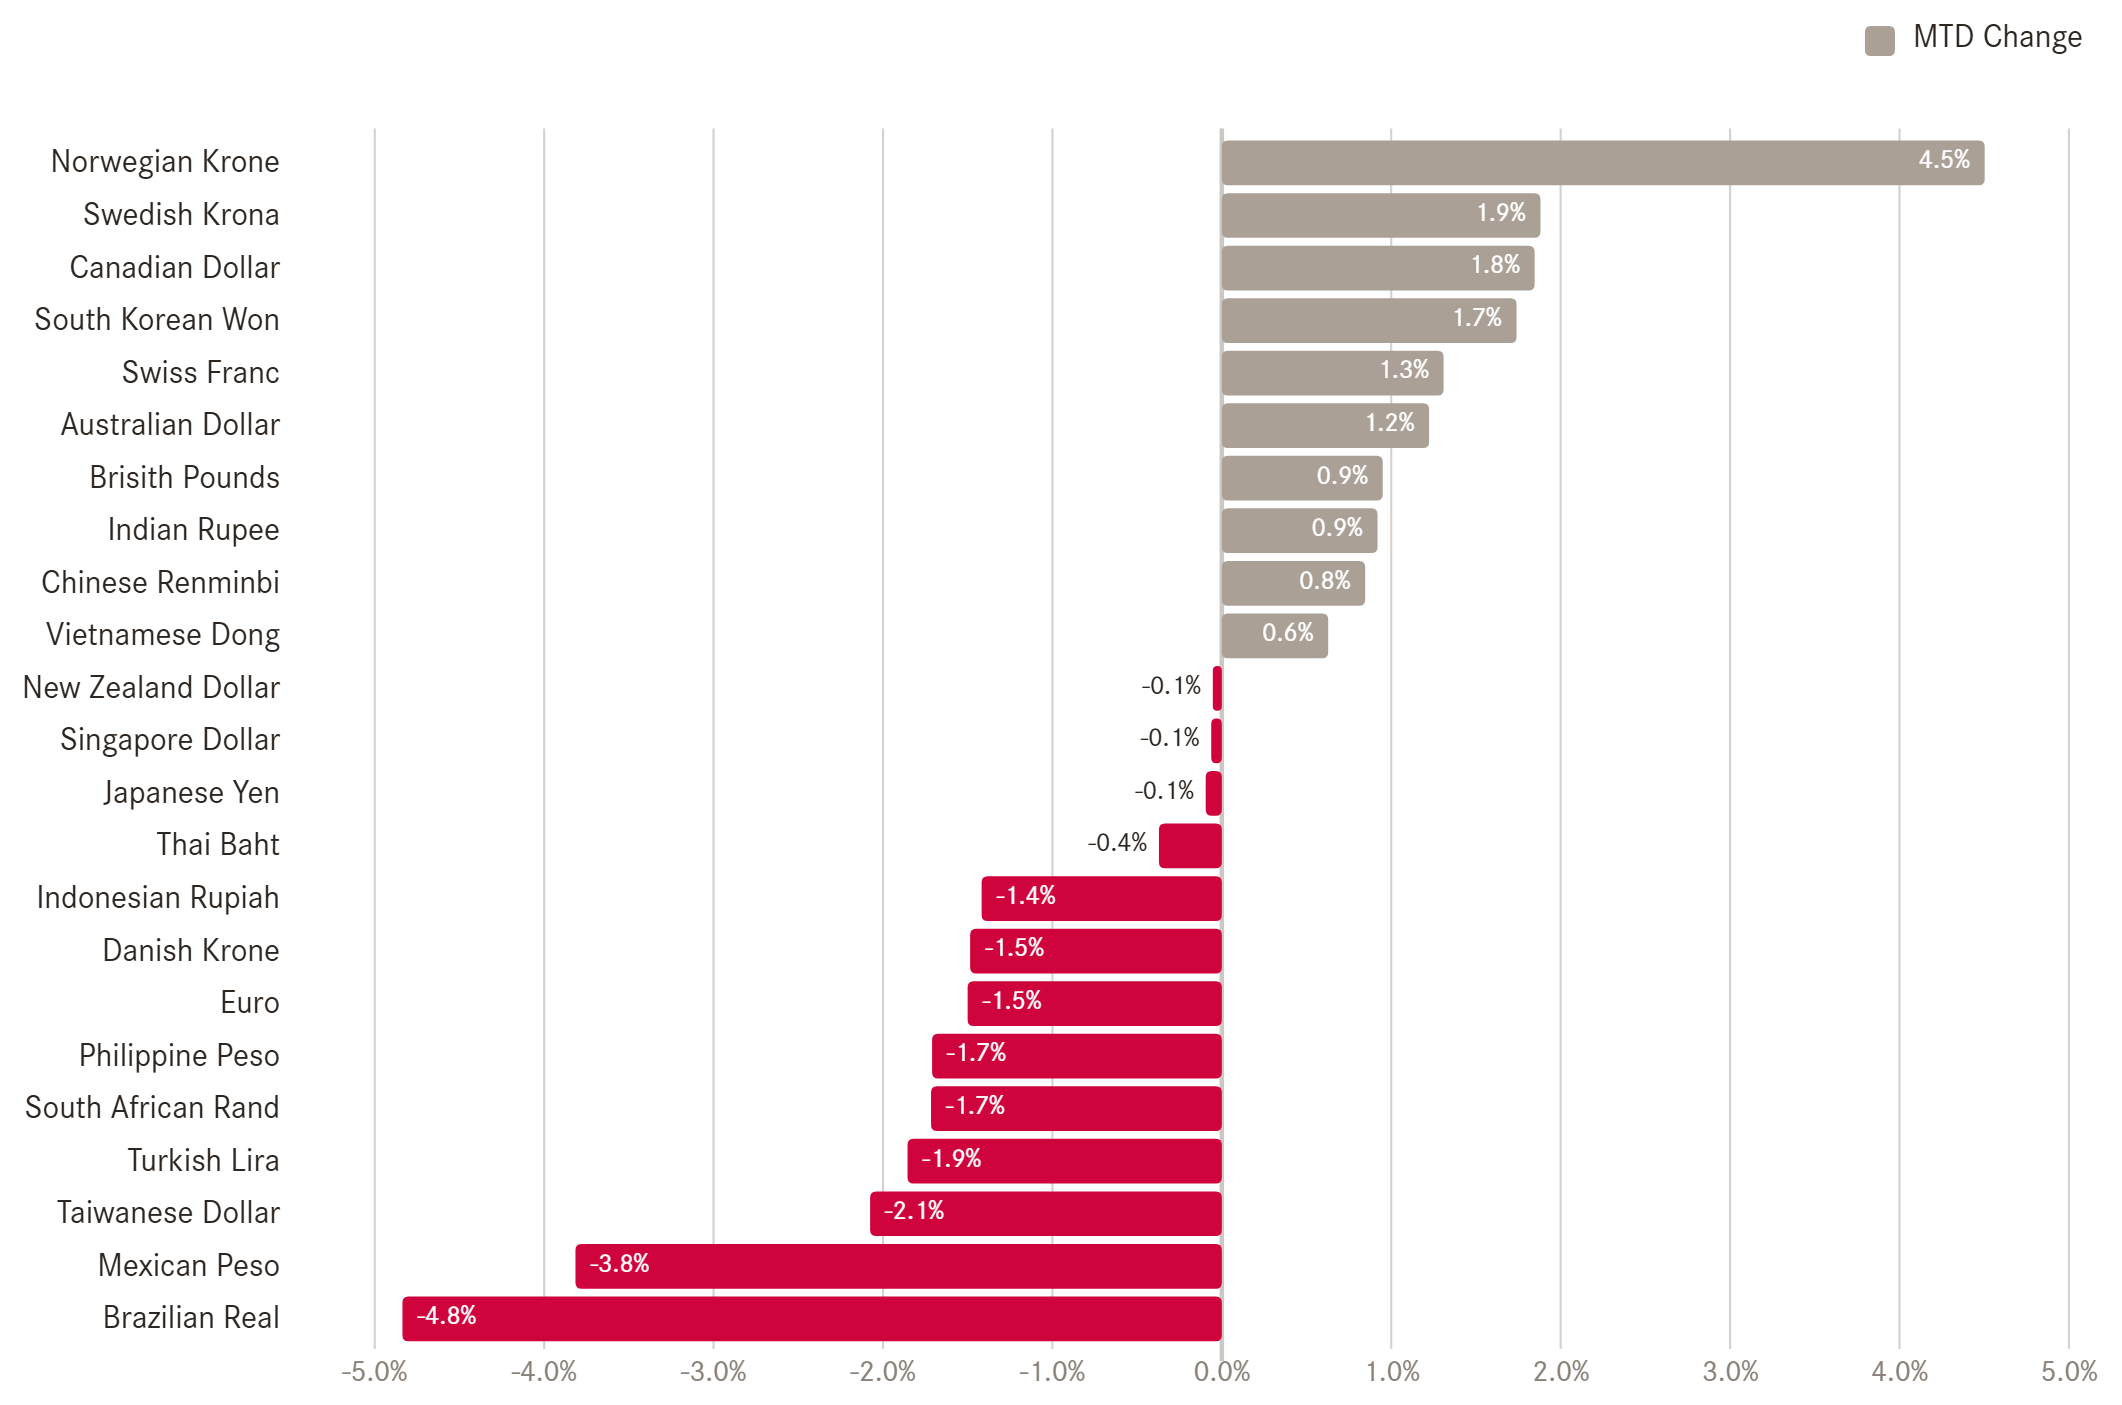
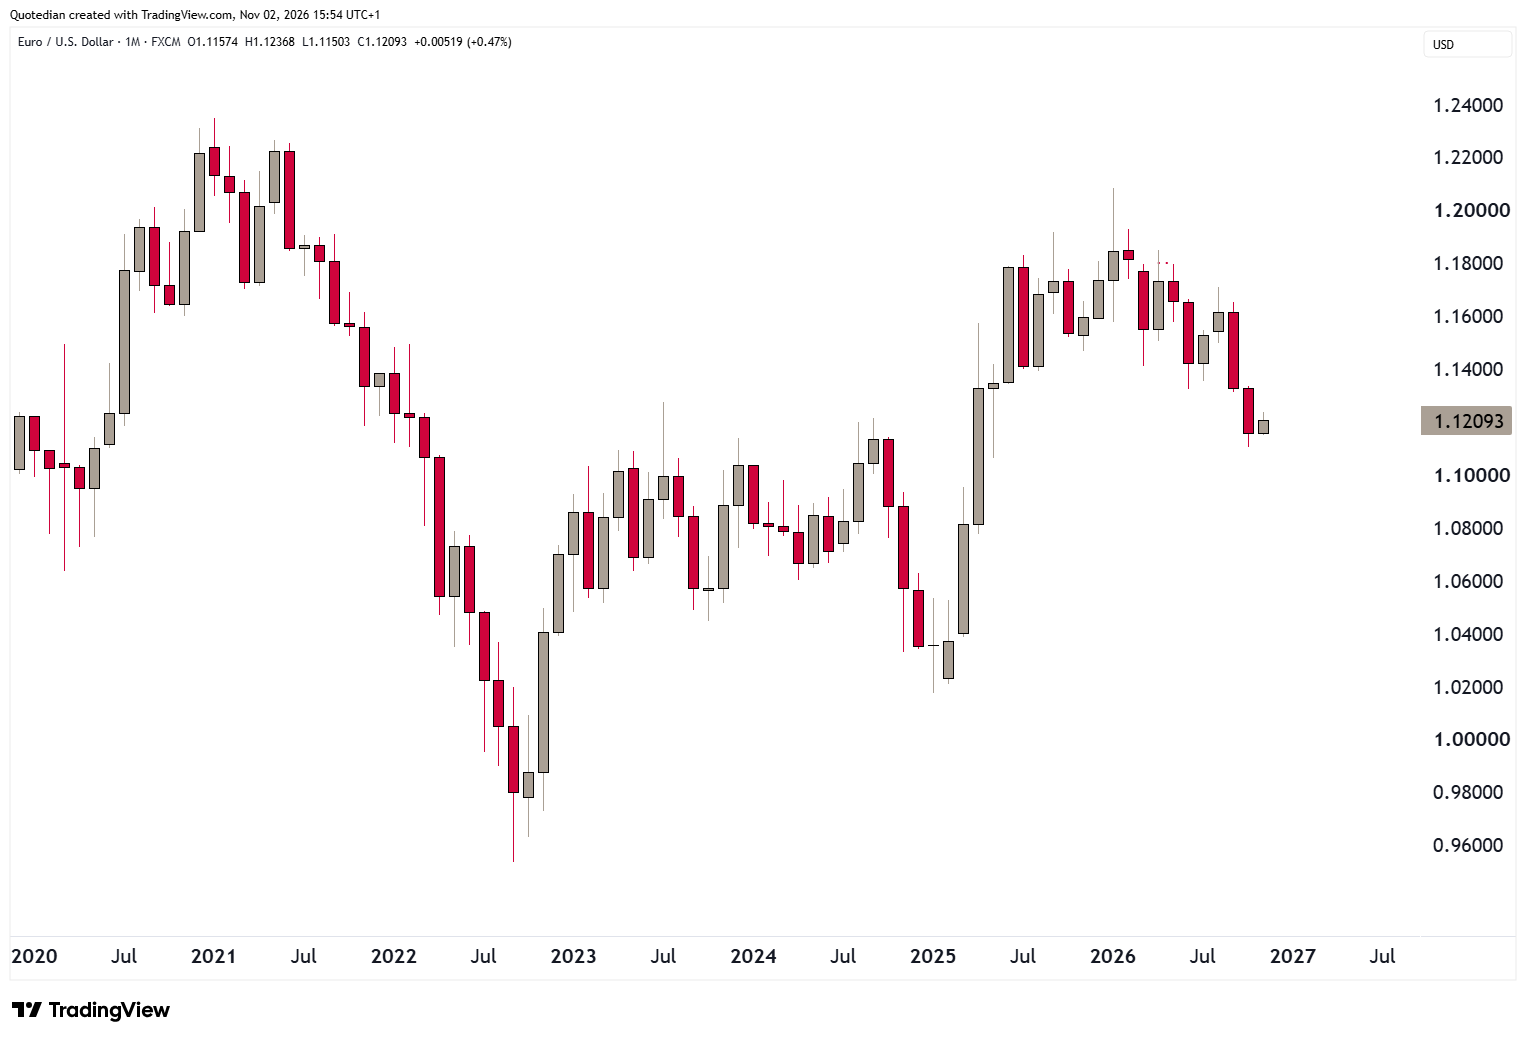
The Euro was one of the weaker components versus the greenback:
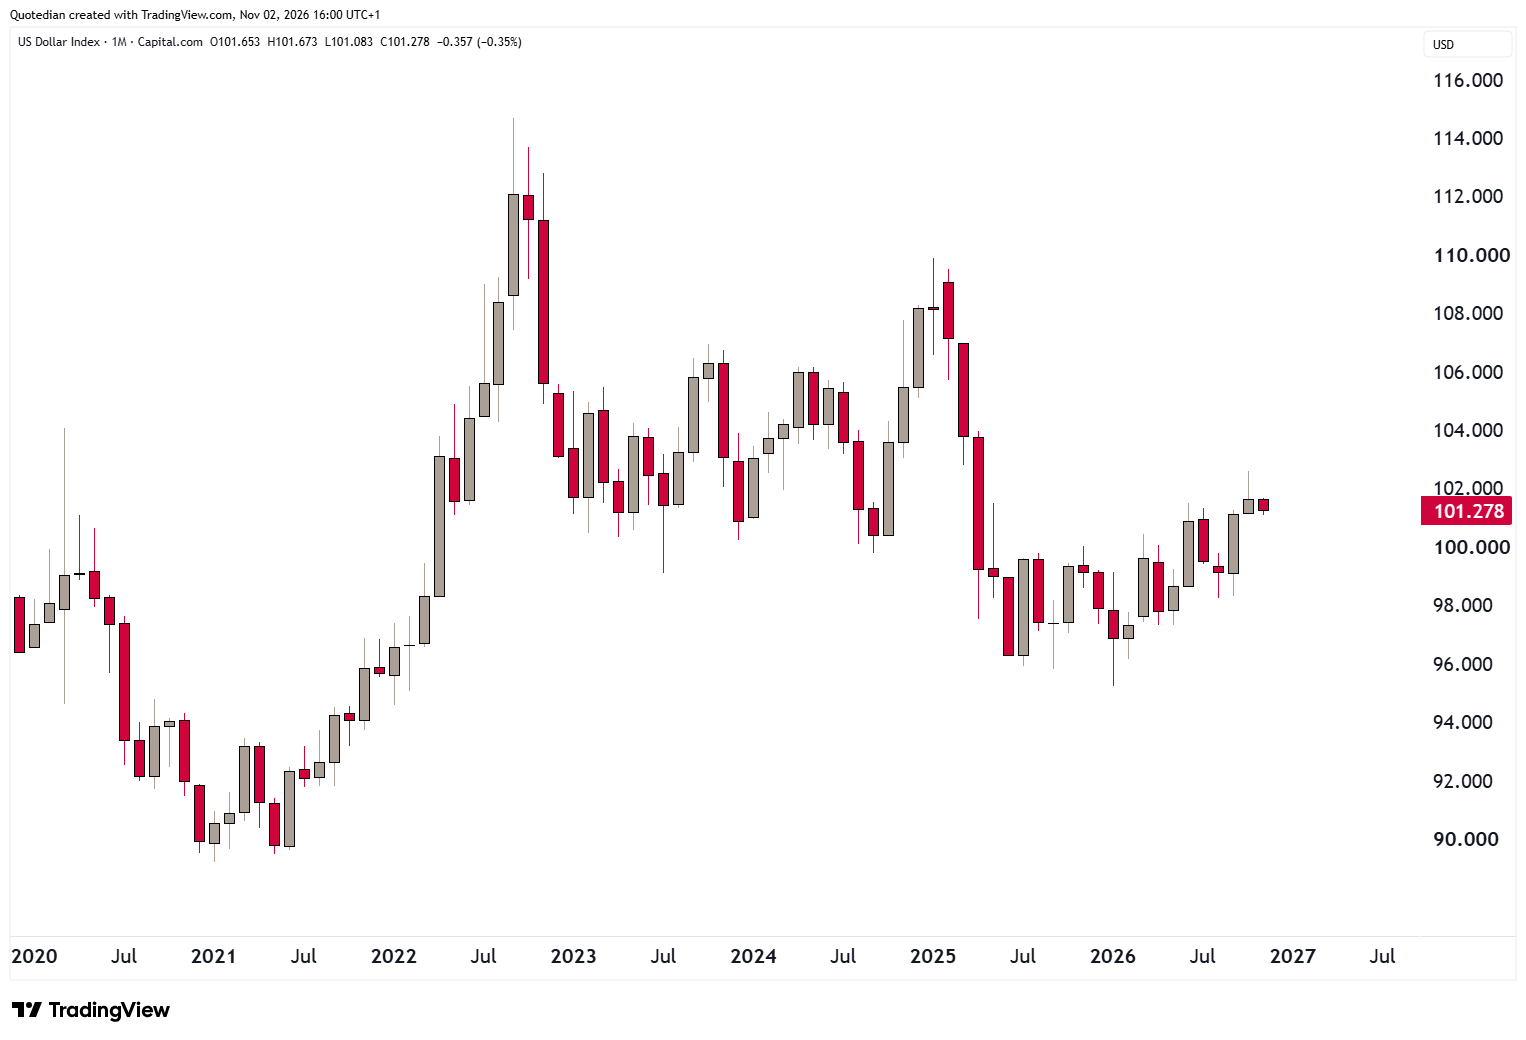
However, I cannot find too much $-bullishness in the broader USD Index (DXY) monthly chart:
One of the better trades has been EUR/JPY short:
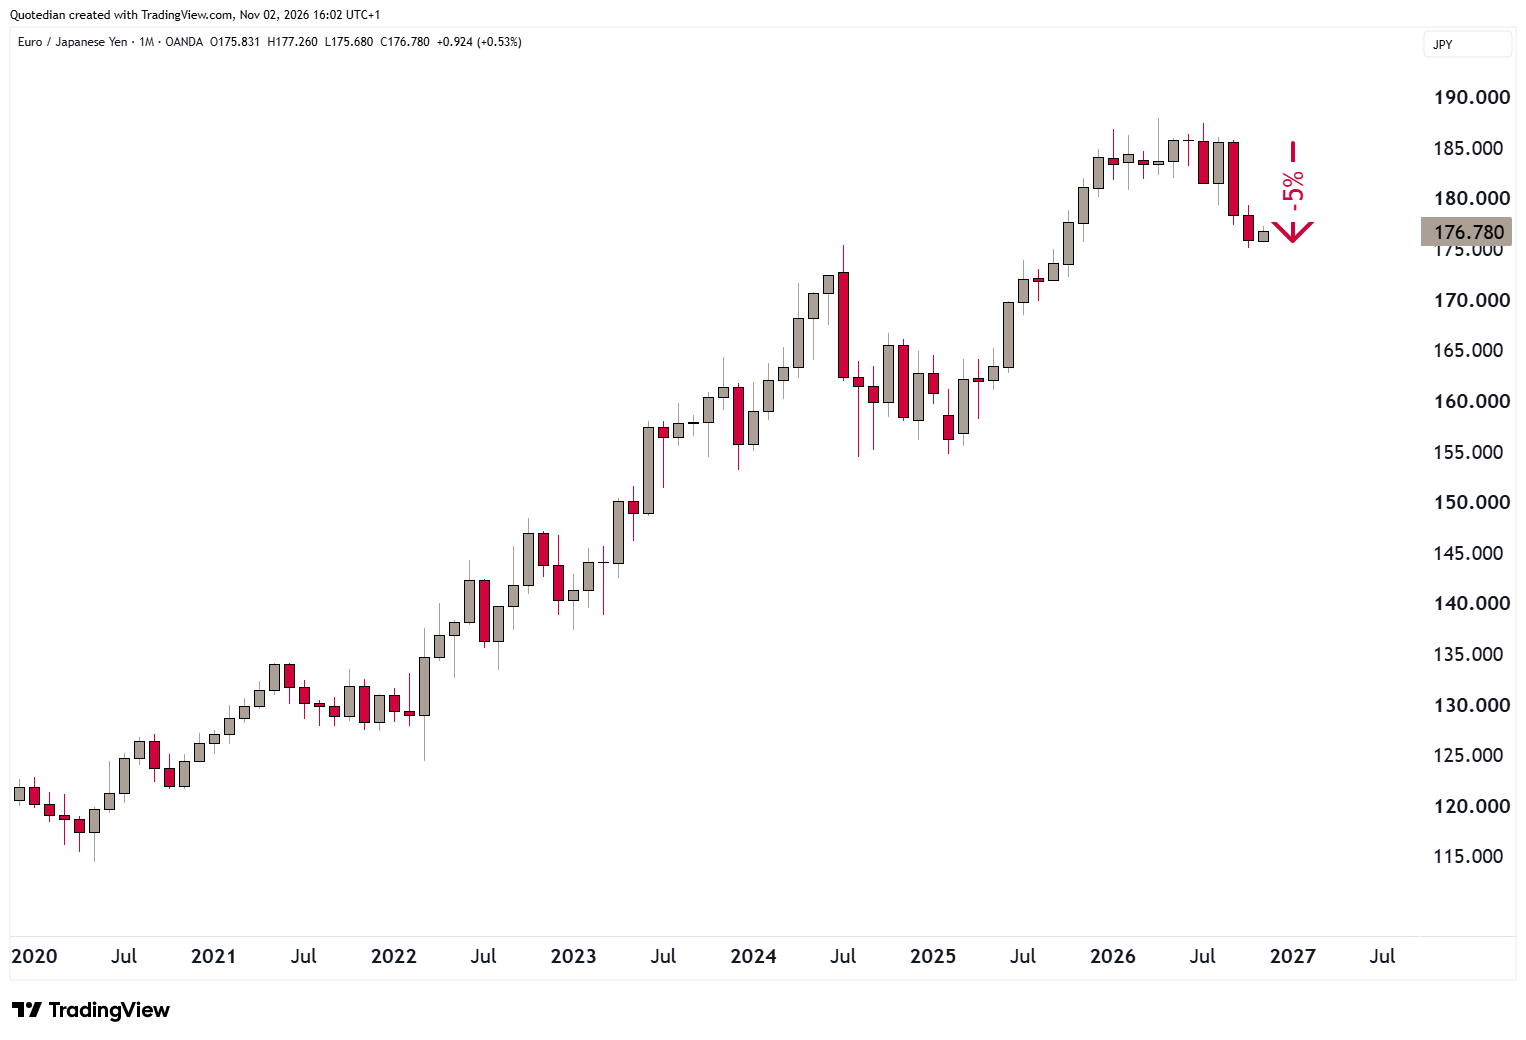
Stick with it.
COMMODITIES
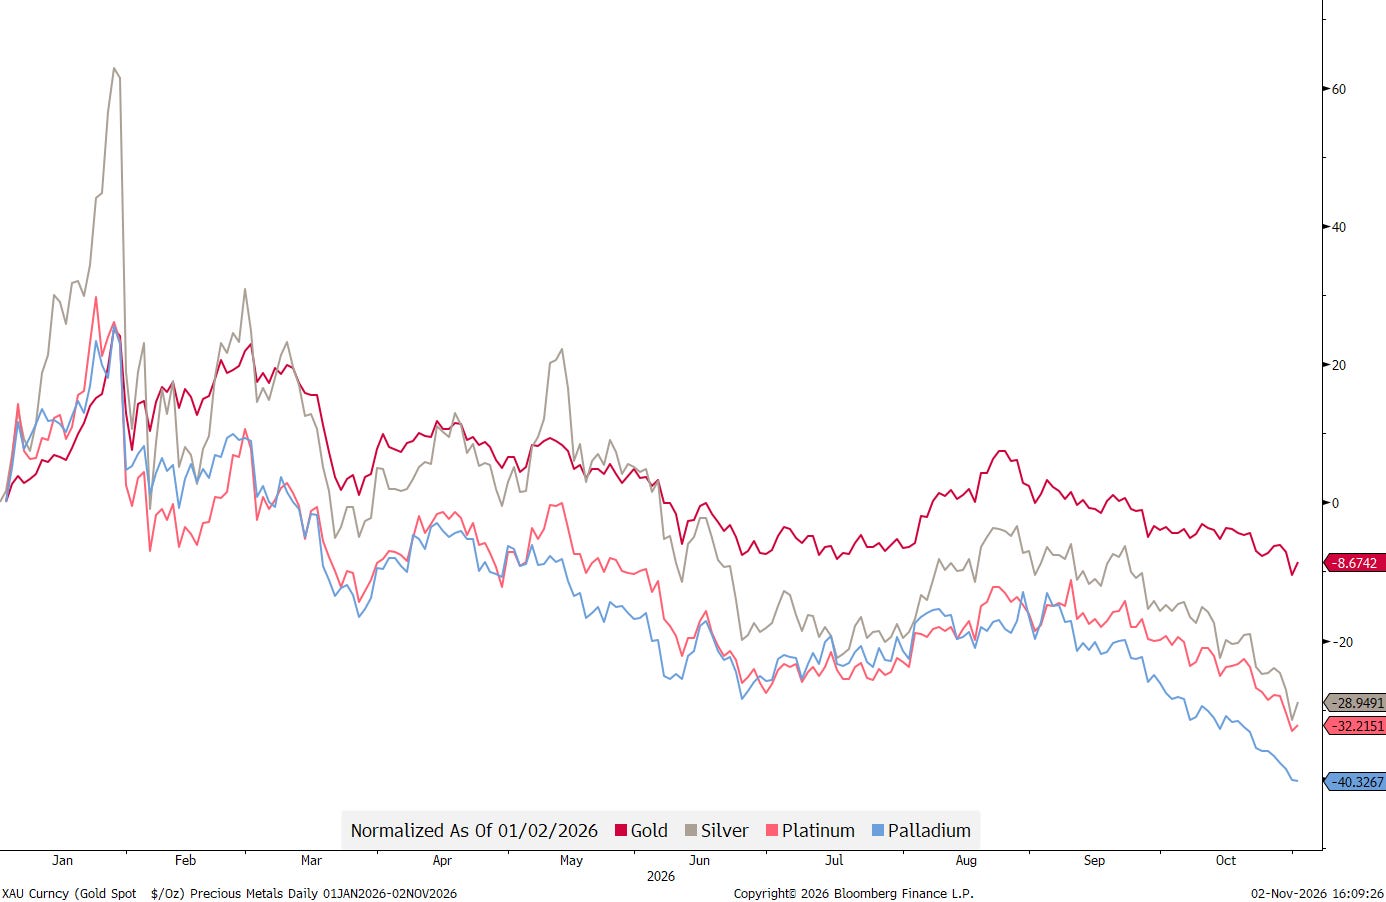
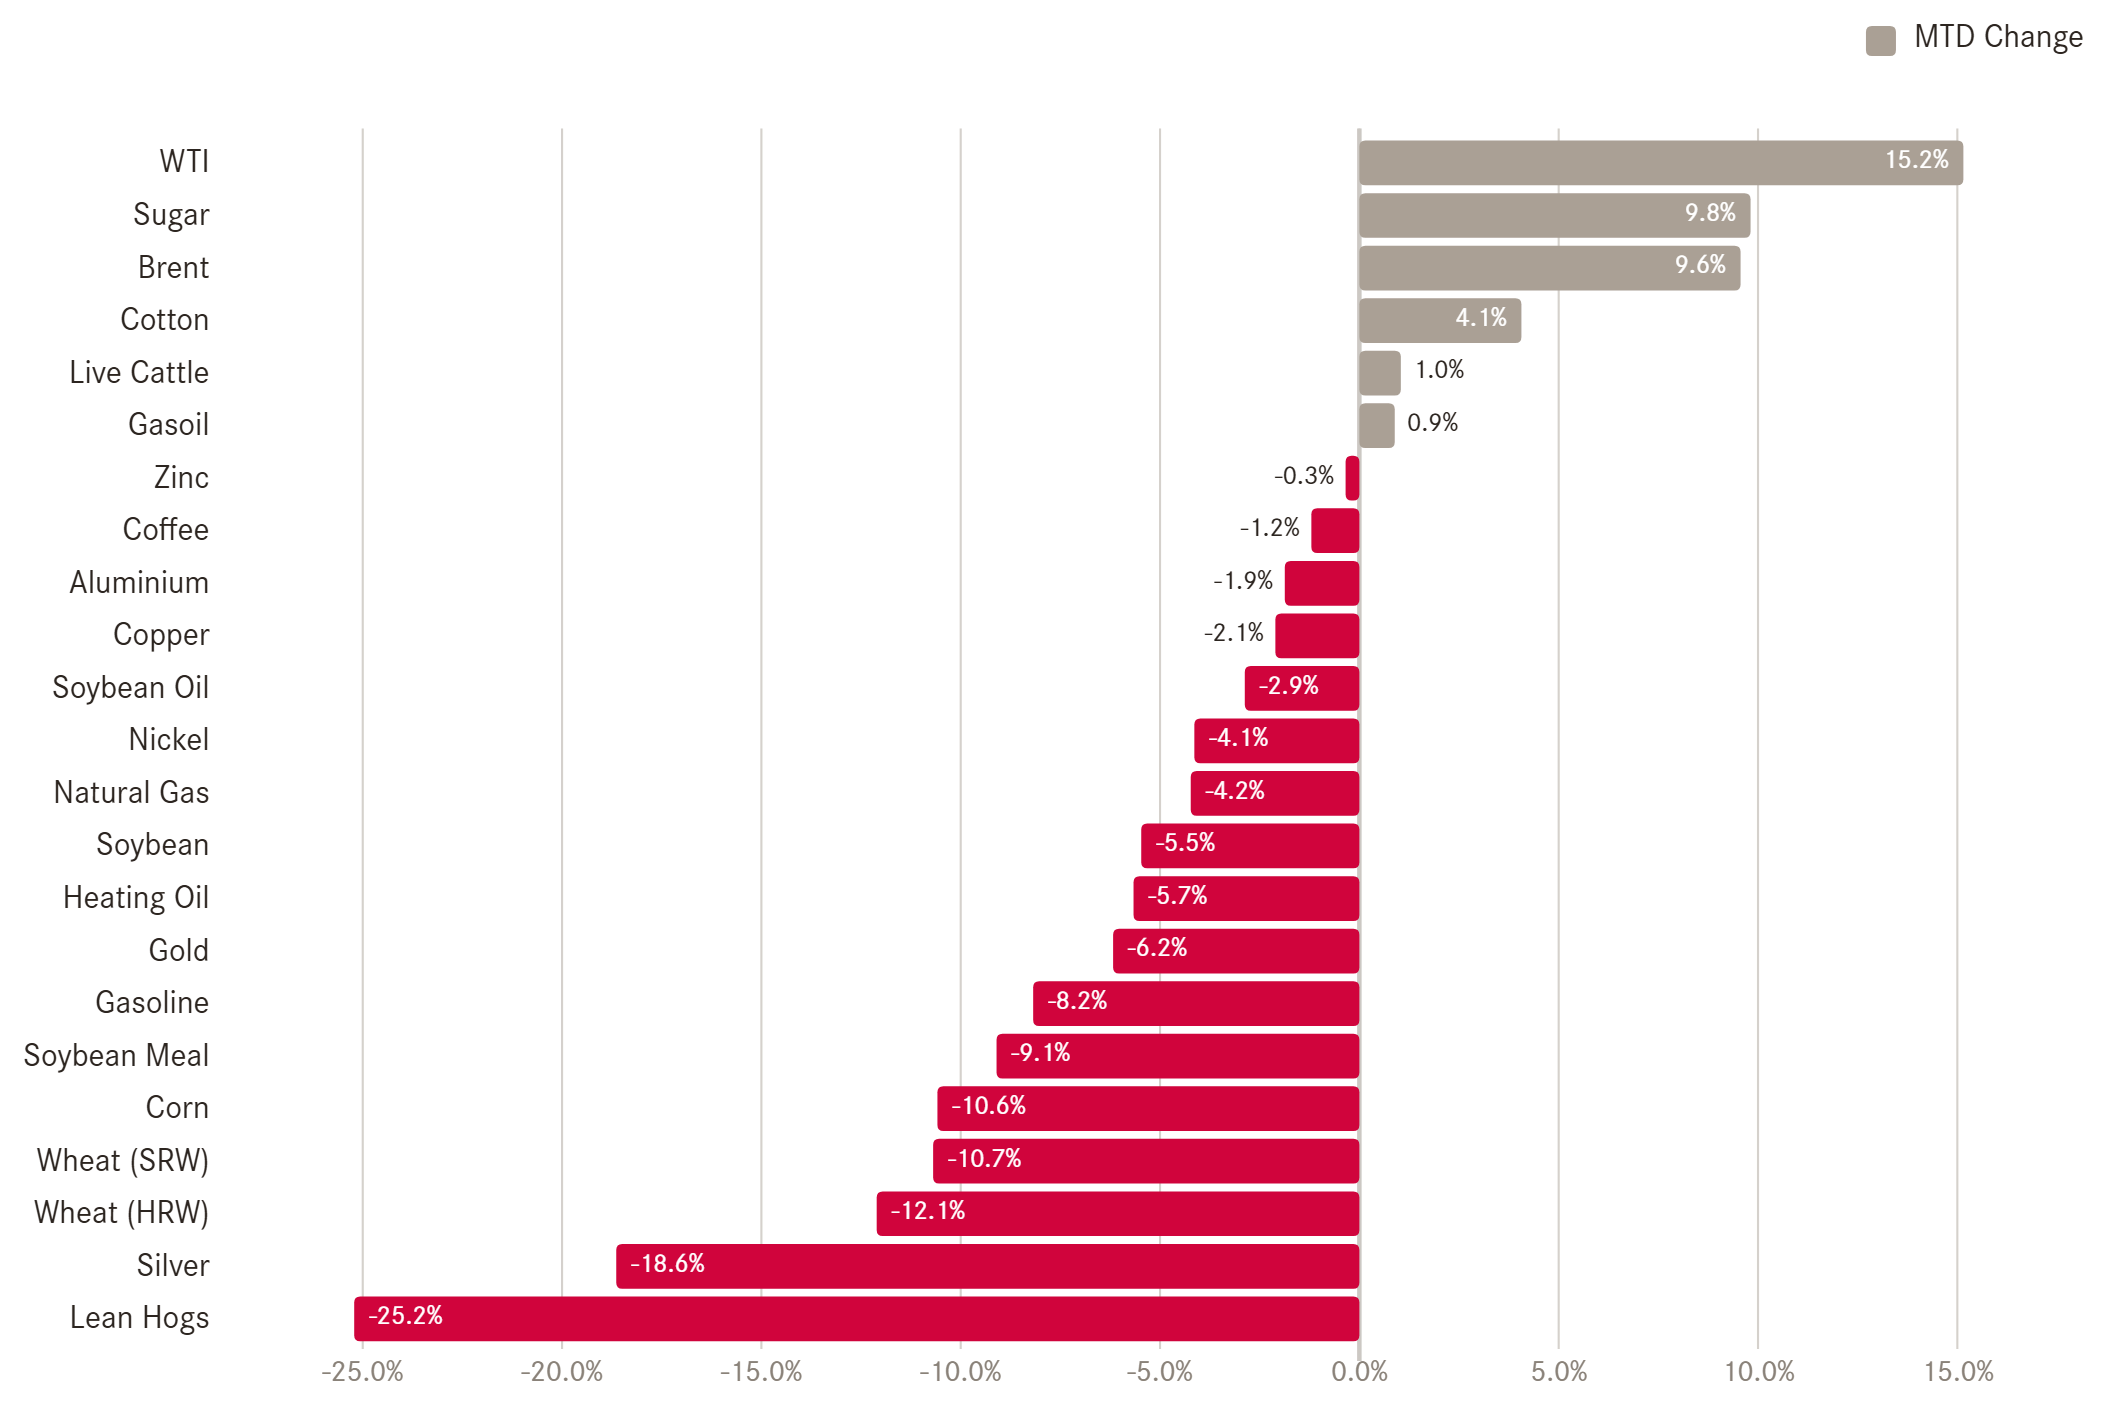
It has been a horrible month for precious metals and grains:
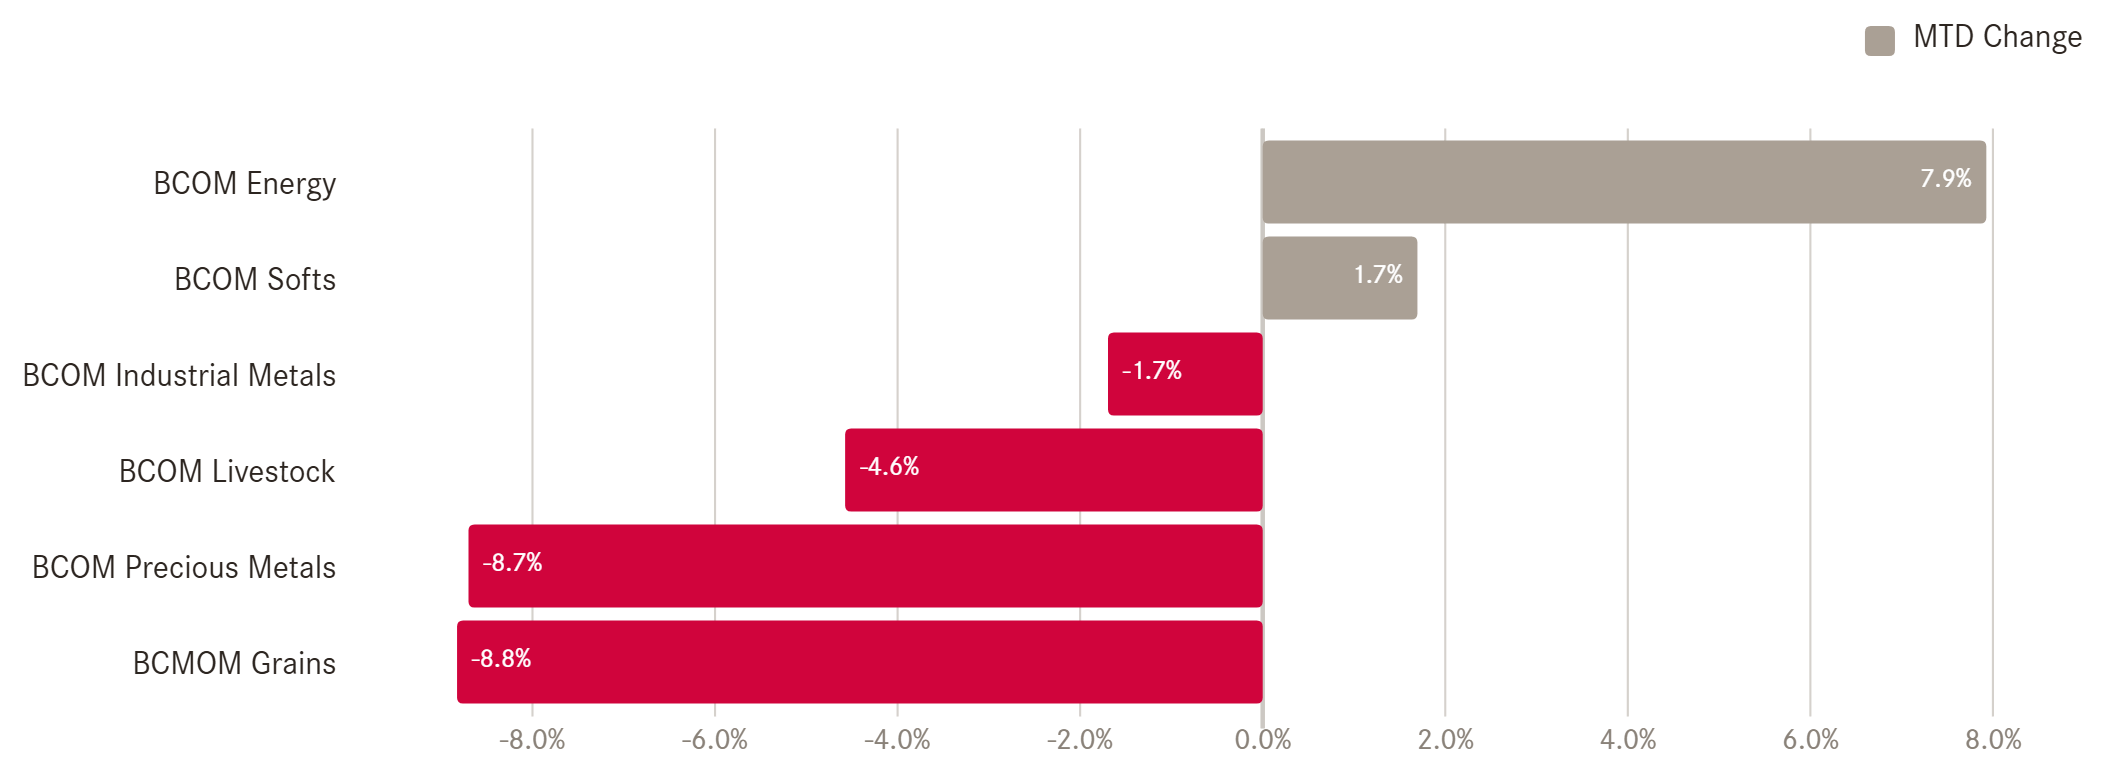
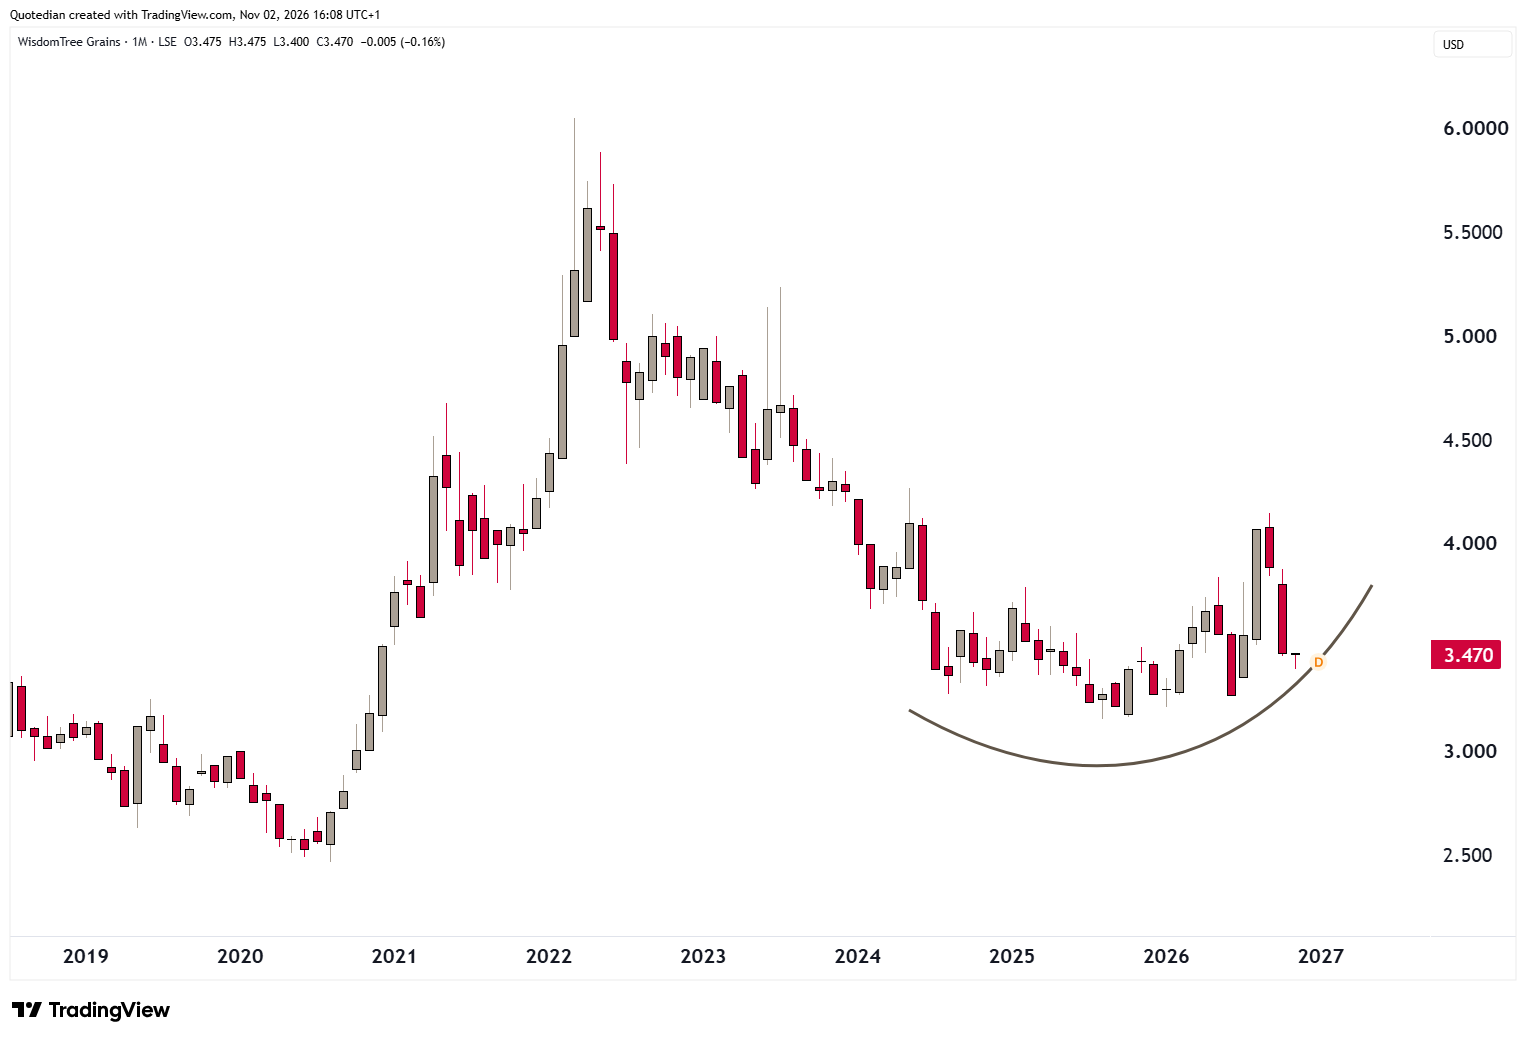
Given the ongoing blockage in the Strait of Hormuz and the effects of ‘El Niño’ on crop yields, I think a buying opportunity may be offering itself in the latter (grains).
Not for the faint of heart, but a position in the WisdomTree Grains ETF (AIGG) may be of consideration:
What definitely has been painful is the exposure to precious metals in any portfolio:
What has performed much better, but is also painful, just in another way than via your portfolio, are energy commodities…
And that’s already it for this week!
Make sure to poll and …
… May the Trend be with You!
André

The Important One:
Everything in this document is for educational purposes only (FEPO)
Nothing in this document should be considered investment advice
Investing real money can be costly; don’t do stupid shit
Leave politics at the door—markets don’t care.
Past performance is hopefully no indication of future performance
The views expressed in this document may differ from the views published by NPB Neue Privat Bank AG
The Legal One: